Navigating the CT600I: Understanding its Role in Corporation Tax Management
For businesses operating in the UK, compliance with tax regulations is paramount, particularly when it comes to Corporation Tax. One specific form that plays a critical role in this process is the Corporation Tax: supplementary charge in respect of ring fence trades (CT600I). This form is not just a piece of paperwork; it is a crucial element for companies engaged in ring fence trades to accurately report their profits and comply with tax obligations. Let us delve deeper into the significance of the CT600I and how it fits into the broader context of Corporation Tax reporting.
The Distinct Functionality of the CT600I
While the CT600 form serves as the main Company Tax Return, the CT600I acts as a supplementary page specifically designed for companies involved in certain industries, primarily oil and gas exploration. The CT600I is tailored to capture the unique aspects of taxation related to ring fence trades, distinguishing it from other forms that may be relevant to general Corporation Tax calculations.
What Constitutes a Ring Fence Trade?
Ring fence trades refer to activities in the oil and gas industry where profits and taxation are handled differently than in standard commercial operations. The idea behind the ring fence is to protect revenue derived from these trades specifically, allowing for a more specialized tax treatment.
Key Differences from Other Supplementary Pages
- Focus on Ring Fence Activities: Unlike other supplementary pages, such as those for research and development (R&D) tax credits, the CT600I is strictly for ring fence trades.
- Supplementary Charge Calculation: The CT600I includes specific lines to report not just profits, but also adjustments related to financing costs, losses carried forward, and decommissioning costs.
Filling Out the CT600I: A Step-by-Step Guide
Completing the CT600I can appear daunting due to the level of detail required. However, breaking it down into manageable steps can help ensure accuracy. Each accounting period starting on or after April 1, 2015, requires careful attention to the form's various sections.
Crucial Steps to Complete the Form
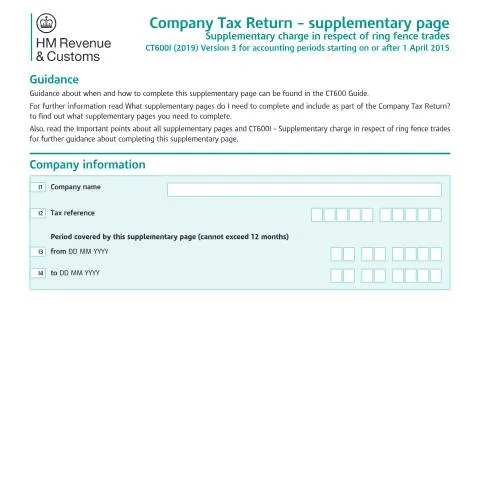
- Company Information: Begin by providing the basic details of your company, including its name and tax reference number. Specify the period covered by the CT600I, ensuring it does not exceed 12 months.
- Net Ring Fence Trade Reporting: Enter the figure for net ring fence trade profits. This should be reported net of any allowable deductions.
- Supplementary Charge Tax: Calculate and report the supplementary charge tax that applies to the net ring fence profits calculated earlier.
- Adjustments for Financing Costs: Detail any disallowed financing costs and adjustments for decommissioning to arrive at the revised ring fence profits.
- Losses and Transfers: If applicable, report any losses arising in the period and indicate elections related to transferring tax history.
Submitting the Form: Channels and Guidelines
After meticulously completing the CT600I, companies must choose the best method to submit the form. Understanding the different channels available for submission can make this process more efficient.
Available Submission Channels
- Online Submission: Most companies choose to submit their CT600 and supplementary pages electronically through HMRC’s online services. This method offers faster processing times and immediate acknowledgment of receipt.
- Paper Submission: Alternatively, businesses can choose to fill out a paper version of the CT600I. However, it is important to note that processing times may be significantly longer with this method.
- Agent Submission: If your company uses an accountant or tax advisor, they can also submit the CT600I on your behalf. Be sure to grant them the necessary permissions through HMRC.
Understanding the Regulatory Framework Behind the CT600I
To truly appreciate the importance of the CT600I, one must consider the regulatory backdrop against which it operates. The Corporation Tax Act and associated legislation outline the requirements and stipulations for reporting ring fence trades.
Key Legislative Elements
- Data Protection: The submission of the CT600I is governed by the Data Protection Act 2018 and UK GDPR, ensuring that personal and corporate data is handled correctly.
- Accounting Periods: The form applies exclusively to accounting periods beginning on or after 1 April 2015, reflecting specific tax rules applicable to those dates.
This legislative framework reinforces the need for consistency and compliance in reporting, ensuring the integrity of the tax system.
Post-Submission: What to Expect from HMRC
Once the CT600I is submitted, companies may wonder about the subsequent steps and how to track the progress of their submission. Understanding HMRC's processing timeline and response protocol is crucial for managing expectations.
Following Up on Your Submission
- Processing Time: Generally, if submitted online, HMRC may take several weeks to process your return. Keep an eye on your online account for updates.
- Acknowledgments: Upon processing, HMRC typically sends an acknowledgment. If you do not receive one, consider reaching out to confirm receipt.
- Further Information Requests: Be prepared to provide additional information if HMRC requests it. This may include supporting documents or clarifications about the figures reported.
Addressing Issues: Errors, Refusals, and Missing Information
Even with diligent care, mistakes can occur during the completion and submission of the CT600I. It is essential to know how to handle these situations effectively.
Correcting Mistakes
If you discover an error after submission, you have the option to amend your CT600I. Here’s how:
- Identify the Error: Clearly understand the nature of the mistake, whether it concerns figures reported or missing data.
- Prepare the Amendment: Complete a CT600I with corrected information and highlight it as an amendment.
- Resubmit: Submit the amended form through your chosen channel, ensuring to reference the original submission.
Handling Refusals and Additional Queries
- Contact HMRC: If your submission is rejected, contact HMRC directly for clarification on the reasons behind the refusal.
- Respond Promptly: Address any queries or concerns from HMRC swiftly to avoid delays in processing your tax return.
Conclusion: The CT600I as an Integral Component of Tax Compliance
The CT600I form may be viewed as just another bureaucratic document, but its role extends far beyond that. For companies engaged in ring fence trades, it serves as a critical tool for managing tax liabilities, enabling businesses to report their financial standing accurately and in accordance with legal requirements.
Whether you are filling out your first CT600I or you are a seasoned professional, understanding its nuances is essential for maintaining compliance and optimizing your tax position. By being diligent in the completion and submission of this form, businesses not only adhere to regulatory demands but also foster a positive relationship with HMRC, paving the way for smoother operations and financial stability.
Understanding Ring Fence Trades and Their Relevance to Corporation Tax
In the context of Corporation Tax, ring fence trades refer specifically to certain activities within the oil and gas sector that are subject to unique taxation rules. This distinction is crucial since these trades operate separately from the taxpayer's other income-generating activities. The concept of ring fencing was introduced to ensure that companies engaged in these trades contribute fairly to the public revenue, particularly considering the substantial profits that can be generated from natural resources.
Ring fence trades are primarily related to the extraction of oil and gas in the UK continental shelf. The intention behind this legislation is to prevent losses from other business activities from offsetting profits made from oil and gas extraction, thus ensuring that the profits from these resources are taxed appropriately. Companies involved in such trades must be aware of the specific rules and regulations, including how the supplementary charge is applied.
When completing your CT600I form, it's essential to accurately identify your ring fence profits. The supplementary charge applies at a rate of 30% on these profits, but only after the deduction of allowances. Understanding how allowances work in this context can be critical for effective tax planning. For instance, companies can claim capital allowances on qualifying expenditure incurred on ring fence assets, which helps to alleviate the tax burden. However, the rules surrounding these allowances can be intricate and may differ from those applicable to non-ring fence activities.
Navigating the Supplementary Charge Calculations
Calculating the supplementary charge can be complex, as it involves various factors that must be meticulously considered. Companies should start by determining their qualifying ring fence profits. This means identifying all income derived from ring fence activities and ensuring that any expenses claimed are allowable under HM Revenue and Customs (HMRC) guidelines.
Once the profits have been calculated, the next step is to apply any relevant deductions. Companies can claim relief for capital expenditures through the Annual Investment Allowance (AIA) or other capital allowances, which can significantly lower the taxable profits. However, it is important to note that the rules for AIA are distinct within the context of ring fence trades. For example, companies need to be aware that the AIA limit for ring fence trades can differ from the standard limits applied to other businesses.
Moreover, attention to detail is crucial when keeping records and supporting documents that justify the calculations made on the CT600I. Proper record-keeping is mandated under the Data Protection Act 2018 and UK GDPR, ensuring that all personal and business data is handled appropriately during this process.
Particular care should be taken regarding the deadlines for submitting your CT600I return. The typical Corporation Tax return must be filed within 12 months following the end of the accounting period. However, if there are delays in determining ring fence profits or supplementary charges, it is advisable to consider requesting extensions or making preliminary payments to avoid accruing penalties from HMRC.
Common Pitfalls and How to Avoid Them
Filing the CT600I and calculating the supplementary charge on ring fence trades can be fraught with challenges. One common pitfall is the misclassification of income or expenses related to ring fence activities. Companies may inadvertently include income from non-ring fence trades in their calculations, leading to inaccuracies that could result in penalties or increased scrutiny from HMRC.
Another common issue arises from the misunderstanding of the specific allowances that can be claimed. For instance, failing to accurately apply capital expenditure allowances can result in a higher tax liability than necessary. It's crucial for companies to take the time to familiarize themselves with the specific rules surrounding capital allowances in the context of ring fence trades. Consulting with tax professionals who understand the nuances of Corporation Tax and ring fence regulations can provide significant advantages.
Additionally, businesses should be aware of the implications of changes in tax legislation affecting ring fence trades. The oil and gas sector can be highly volatile, with fluctuations in market prices affecting profitability. Consequently, it is advisable to keep abreast of any legislative changes that could impact their tax position, including potential new allowances or changes to existing reliefs that could arise.
Another potential pitfall is inadequate financial forecasting and cash flow planning based on the anticipated tax liabilities. Companies should not only prepare for expected profits but also create strategies for managing their tax obligations effectively. This could include making advance payments towards Corporation Tax liabilities or setting aside reserves to cover potential tax bills related to supplementary charges.