Navigating the CT600I: A Comprehensive Guide for Your Corporation Tax Needs
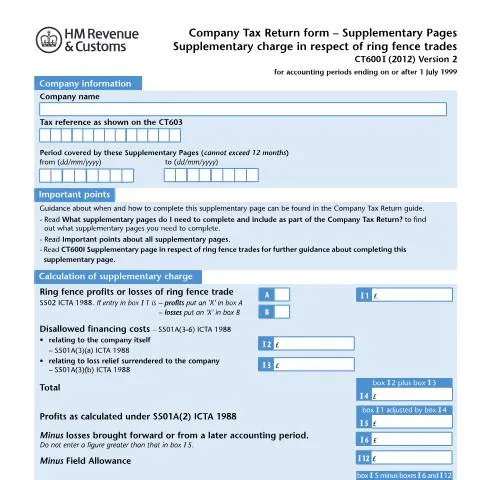
When businesses engage in ring fence trades—activities involving oil and gas extraction, for instance—they often encounter the necessity of submitting the CT600I (2012) Version 2 form. This document, a supplementary page for the Corporation Tax return, is crucial for accurately reporting supplementary charges related to these specific trades. Understanding its role, who needs to submit it, and how to fill it out properly can significantly impact your corporation’s tax obligations.
Understanding the Ring Fence Trade Concept
Ring fence trades are defined under the Income and Corporation Taxes Act 1988 (ICTA 1988). The legislation aims to ensure that profits or losses from activities such as oil or gas exploration and extraction are treated distinctly for taxation purposes. This separation is vital to prevent cross-subsidisation from other profitable business activities, thus maintaining fairness in taxation levels across various sectors.
- Why Ring Fence? The rationale behind the ring fence is to isolate the financial performance of these industries from other commercial undertakings, ultimately leading to a more equitable tax system.
- Who is Affected? Companies engaged primarily in ring fence trades, including those involved in oil and gas extraction, are required to report their activities through this form.
Who Must Submit the CT600I?
Only specific companies are required to file the CT600I supplementary charge form. Here are some examples to illustrate:
- Oil and Gas Companies: Those engaged in extraction and production must include this form as part of their tax reporting duties.
- Partnerships: If a partnership operates a ring fence trade, it may also need to complete this form.
- Exceptions: Companies not involved in any ring fence activities are exempt from submitting the CT600I.
Determining Your Company’s Status
It’s essential to ascertain whether your corporation is considered a ‘ring fence trade’ entity. If your business is involved in any activities related to oil or gas extraction, you likely fall under this category. Refer to the HM Revenue & Customs (HMRC) guidelines for further clarity on your obligations.
Completing the CT600I: Step-by-Step Guidance
Filling out the CT600I can seem daunting due to its specific requirements. However, by breaking down the sections, the process becomes more manageable.
Key Sections of the Form
The form consists of several critical sections that require careful attention:
- Company Information: Fill in the company name, tax reference, and the period covered by the supplement. Ensure accuracy as this establishes your official record with HMRC.
- Profit or Loss Reporting: Here, you’ll indicate whether you’re reporting profits (mark box A) or losses (mark box B). It’s crucial to ensure the number you report aligns with the calculations specified under Section 501A ICTA 1988.
- Adjustments and Charges: Various adjustments may be needed based on financing costs or losses from previous periods. Be attentive to these details as they will affect your total taxable income.
- Final Calculations: This section is where you compute the net profits subject to the supplementary charge. All deductions must be carefully accounted for to achieve accurate figures. Double-check your numbers, especially when moving them to the main CT600 form.
Submission Channels: Digital vs. Paper
In the era of digital transformation, HMRC provides multiple avenues for submitting your CT600I. Understanding the differences between them can affect the speed and efficiency of your submission.
Online Submission
Filing your CT600I online provides several benefits:
- Instant Confirmation: You receive immediate feedback upon submission, allowing you to rectify any errors promptly.
- Accessible at All Times: Online systems are typically available 24/7, allowing you to submit at your convenience.
- Lower Chance of Errors: The digital format often includes checks to prevent common errors during submission.
Paper Submission
While many prefer the ease of online filing, some businesses may opt to submit a paper form. Consider the following:
- Longer Processing Time: Paper submissions can take significantly longer to process, which may delay any tax refunds.
- Risk of Loss: Physical forms may be lost in transit, leading to complications in your filing record.
What Happens After Submission?
Upon successful submission of your CT600I, several potential pathways can arise:
- HMRC Review: HMRC may conduct a review of your submission to ensure compliance with tax regulations, which could lead to requests for further information.
- Calculating Tax Liabilities: Your reported figures will be used to determine your corporation tax liabilities. Accurate reporting is essential to avoid overpayment or issues with underpayment.
- Potential Audits: If discrepancies are noted either during the submission process or in subsequent reviews, your corporation may be subject to an audit.
Points of Caution
Be mindful of deadlines. Corporation tax is due nine months after the end of your accounting period, and the CT600I is generally due at the same time. Missing deadlines could incur penalties.
Dealing with Errors or Missing Information
It’s not uncommon for businesses to encounter issues such as errors or missing information when completing the CT600I. Here’s how to manage these situations effectively:
Correcting Errors
If you discover an error after submission, you have options:
- Amend Your Submission: You can submit an amended return online through your HMRC account, provided you do so within the relevant time limits.
- Documentation: Maintain detailed documentation to support your corrections, as HMRC may request further verification.
Handling Missing Information
If you find that you've overlooked a section or piece of information:
- Immediate Action: Contact HMRC as soon as possible to notify them of the issue. Transparency is critical.
- Follow-Up: Ensure that any missing information is submitted in a timely manner to prevent complications with your corporation tax obligations.
Understanding Supplementary Charges
The supplementary charge is a crucial component of the CT600I. This charge applies to net profits from ring fence trades after taking account of specific deductions and adjustments.
Calculation Methodology
To compute the supplementary charge, follow these steps:
- Start with your total profits as calculated under Section 501A(2) of ICTA 1988.
- Subtract any losses carried forward or incurred in later accounting periods.
- Deduct the field allowance where applicable.
- Finally, apply the supplementary charge rate to the resulting net profits.
The Importance of Timely and Accurate Submission
Submitting your CT600I accurately and on time not only ensures compliance with HMRC regulations but can also impact your corporation’s financial health. Late or inaccurate submissions can lead to penalties, interest charges, and potential audits, all of which may distract from normal business operations.
To optimise your filing process:
- Regular Monitoring: Keep a regular check on your reporting obligations and deadlines to avoid last-minute stress.
- Engage Professionals: Consider hiring tax professionals familiar with the intricacies of ring fence trades and the CT600I form to assist in accurately preparing your tax return.
Concluding Thoughts on Managing Your Corporation Tax Responsibilities
Successfully navigating the complexities of the CT600I requires diligence and a thorough understanding of your corporation’s financial landscape, especially for those engaged in ring fence trades. By being proactive in your approach to submission, corrections, and deadlines, your business can not only comply with HMRC requirements but also leverage the potential benefits of accurate tax reporting.
For further guidance on the specifics of completing the CT600I, consult the Company Tax Return Guide and ensure that you remain updated on any changes to tax regulations affecting ring fence trades.
Understanding the Supplementary Charge on Ring Fence Trades
The supplementary charge for ring fence trades is a critical aspect of Corporation Tax that companies operating in the oil and gas sector need to navigate. The concept of a ring fence ensures that profits from oil and gas extraction activities in the UK Continental Shelf are taxed at a higher rate compared to other corporate profits. This is due to the substantial profits and the temporary nature of these resources, which often entail significant financial risks and large capital investments.
The supplementary charge applies to companies that engage in the exploration and extraction of oil and gas, and its rate can vary depending on prevailing economic conditions and government fiscal policies. It is important for such companies to be aware of the additional computations required when filling out the CT600I form. Specifically, the charge is applied to profits after the standard Corporation Tax has been calculated, and must be detailed separately on the tax return.
To accurately calculate the supplementary charge, businesses should first determine their total profits from ring fence activities, then assess the allowable capital allowances and any relevant deductions. The main elements that can affect the calculation include exploration costs, development expenditures, and the specific tax rules that apply to the capital investment in qualifying assets. Understanding these variables is essential to ensure compliance with HM Revenue & Customs (HMRC) regulations and to avoid potential penalties for incorrect filings.
Navigating Exemptions and Reliefs Available
When determining the tax liabilities related to the supplementary charge, it is imperative to explore various exemptions and reliefs that may be applicable to ring fence trades. These reliefs can significantly reduce the effective tax burden for businesses in the oil and gas sector. Here are some of the key exemptions and reliefs available:
- Investment Allowance: Companies may benefit from an investment allowance which allows them to claim relief on a portion of their capital expenditure on qualifying assets. This allowance can reduce the taxable profits derived from oil and gas extraction activities, thus lowering the supplementary charge.
- Field Allowance: Introduced to incentivize investment in economically challenging fields, this allowance permits companies to receive a deduction from their profits, effectively reducing the charge applied. Field allowances are generally determined by the economic viability of the extraction field and government discretion.
- Relief for Decommissioning Costs: Companies can claim relief for decommissioning costs that are incurred when an oil or gas field is no longer economically viable. This relief can be particularly valuable as decommissioning can amount to substantial financial outlays.
It is crucial for companies to maintain thorough records and documentation concerning all claims for reliefs and exemptions. The relevant details must be submitted alongside the CT600I form to justify the calculations made and ensure compliance with tax regulations. Engaging a tax advisor with expertise in the oil and gas sector can also provide additional insight into maximising potential reliefs.
Filing Requirements and Best Practices for Compliance
Filing the CT600I (2012) version 2 requires attention to the specifics of the supplementary charge for ring fence trades. Companies must ensure that they are not only completing the form accurately but also adhering to the deadlines set by HMRC. The general filing deadline for Corporation Tax returns is 12 months after the end of the accounting period, but any supplementary charges or adjustments must be filed by the same deadline as the main return.
Here are some best practices for ensuring compliance and a smooth filing process:
- Maintain Accurate Records: Companies should maintain meticulous records of all transactions, including income from ring fence activities, allowable expenses, and any capital investments. These records will substantiate the figures reported in the CT600I form and any claims for reliefs.
- Stay Informed on Legislative Changes: Tax laws and regulations governing Corporation Tax, including supplementary charges, can change. Companies should stay informed about any legislative updates or policy changes that could affect their tax liabilities.
- Consult Professionals: Engaging with tax professionals or advisors who specialize in Corporation Tax and the oil and gas sector can provide invaluable guidance. These experts can assist in navigating complex tax rules, maximizing relief opportunities, and ensuring compliance with HMRC requirements.
By following these best practices, companies involved in ring fence trades can effectively manage their tax obligations, minimize risks, and foster a more robust financial position within the oil and gas market.