When Corporate Governance Meets Legal Aid: Navigating the CIV MEANS 1C Declaration
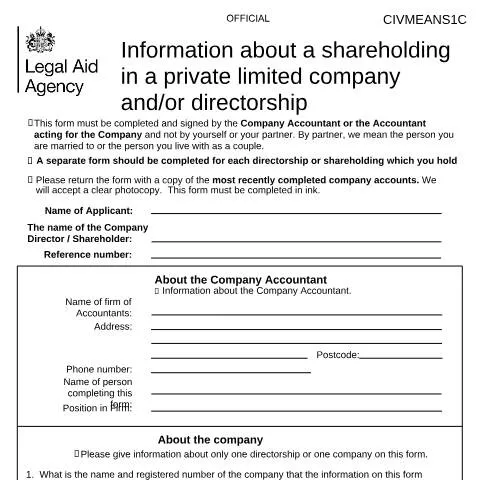
Company directors and shareholders seeking legal aid in civil matters face a unique challenge: their business interests must undergo rigorous financial scrutiny through the CIV MEANS 1C form. This specialised document, administered by the Legal Aid Agency, serves as a comprehensive financial assessment tool that delves deep into the complex relationship between personal finances and corporate holdings. Unlike straightforward employment income declarations, this form requires detailed disclosure of directorial remuneration, shareholding benefits, and intricate financial arrangements between individuals and their companies.
The form's significance extends beyond simple income verification. It examines the true financial capacity of applicants whose wealth may be intertwined with corporate assets, ensuring that legal aid eligibility assessments capture the full picture of available resources. This includes scenarios where directors have loaned money to their companies, received benefits in kind, or maintain complex dividend arrangements that could affect their means test outcome.
Mandatory Third-Party Completion: The Accountant's Central Role
One of the most distinctive features of the CIV MEANS 1C form is its mandatory completion by a qualified accountant rather than the applicant themselves. This requirement reflects the Legal Aid Agency's recognition that corporate financial structures often require professional interpretation to ensure accurate disclosure.
The designated accountant must be either the company's official accountant or an accountant acting for the company in a professional capacity. Personal accountants or family members with accounting qualifications cannot fulfil this role unless they are formally engaged by the company. This restriction ensures independence and professional accountability in the completion process.
Accountant Responsibilities and Verification Requirements
The completing accountant assumes significant responsibility for the accuracy of all disclosed information. They must provide comprehensive firm details, including registration address, contact information, and their specific position within the practice. The form requires completion in ink, emphasising the formal nature of the declaration and the accountant's professional liability for the information provided.
Crucially, the accountant must attach the most recently completed company accounts as supporting documentation. The Legal Aid Agency accepts clear photocopies, but these must be comprehensive and include all relevant schedules and notes that demonstrate the company's financial position and the director's or shareholder's interest within it.
Detailed Corporate and Personal Financial Integration
The CIV MEANS 1C form systematically examines multiple layers of financial connection between the individual and their company, recognising that corporate structures can both enhance and disguise personal wealth.
Directorial Remuneration Analysis
The form requires precise details of directorial compensation across multiple dimensions. Current tax year gross salary must be declared alongside the specific pay period last processed, whether weekly or monthly. This granular approach allows the Legal Aid Agency to assess both historical earnings patterns and current income flow.
Previous financial year earnings provide context for assessing typical income levels, while bonus and commission payments reveal additional compensation elements that might not appear in regular salary calculations. The form specifically requests that benefits in kind be detailed separately, recognising that company cars, accommodation, health insurance, and other perquisites represent genuine financial advantages that affect overall means.
Complex Loan Arrangements and Financial Flows
Perhaps the most sophisticated aspect of the assessment concerns loans and financial advances between directors and their companies. The form examines bidirectional lending arrangements, recognising that these can significantly impact both parties' financial positions.
| Loan Direction | Assessment Focus | Documentation Required |
|---|---|---|
| Director to Company | Outstanding balance and repayment capacity | Loan terms, interest arrangements, repayment schedule |
| Company to Director | Amount borrowed and recent repayments | Loan agreement and repayment history |
| Allocated but Unpaid | Money owed to director by company | Board resolutions or allocation decisions |
The form requires documentary evidence for all loan arrangements, including detailed terms of repayment and any interest provisions. This prevents artificial arrangements designed to obscure available resources from either party.
Shareholding Assessment and Dividend Distribution
Share ownership analysis extends beyond simple percentage calculations to examine the practical financial benefits derived from corporate ownership. The form requires disclosure of total issued shares, providing context for understanding the significance of individual holdings.
Both the applicant's direct shareholding and their spouse or partner's interests must be declared, recognising that family unit resources may be accessible regardless of formal ownership structures. Recent dividend payments for the last financial year provide evidence of actual income derived from ownership, while changes in shareholding over the previous twelve months reveal dynamic ownership patterns that might affect future income potential.
Voting Control Beyond Direct Ownership
The assessment recognises that effective corporate control may exceed formal share ownership through various arrangements such as proxy voting, trust structures, or informal agreements. Directors or their partners who control voting shares beyond their direct holdings must declare these arrangements, as they represent potential influence over dividend policies and corporate decisions affecting personal financial benefit.
Cross-shareholdings in other companies also require disclosure, as these may represent additional income sources or asset bases that could theoretically be accessed to fund legal proceedings.
Property Holdings and Asset Accessibility
Corporate property ownership represents another potential source of personal benefit that the form examines systematically. Companies may own or lease property that provides accommodation or other benefits to directors, or property investments that could be liquidated if necessary.
The form's approach to property assessment recognises that corporate assets, while not directly owned by individuals, may nonetheless represent accessible resources through various mechanisms such as asset distribution, sale proceeds, or rental income allocation.
Submission Process and Supporting Documentation
The CIV MEANS 1C form operates within a strict documentation framework that ensures comprehensive verification of all declared information. Each directorship or shareholding requires a separate form, preventing the confusion that might arise from attempting to aggregate multiple corporate interests within a single declaration.
Essential supporting documents include the most recent company accounts, which must be complete and current. For directors receiving benefits in kind, the most recent P11D form must accompany the submission to verify previously reported benefits and ensure consistency with current declarations.
Processing Timeline and Legal Aid Integration
Once submitted, the CIV MEANS 1C form undergoes detailed analysis by Legal Aid Agency assessors who specialise in corporate financial structures. The information provided directly feeds into the means test calculation, with particular attention paid to available resources that might not be immediately apparent from standard employment or self-employment income.
The assessment considers both current financial flows and potential future access to corporate resources, recognising that directorial or shareholder positions may provide financial flexibility that affects the appropriateness of public funding for legal proceedings.
Strategic Considerations for Corporate Legal Aid Applications
Directors and shareholders must carefully consider the timing of their legal aid applications in relation to corporate financial cycles. Dividend declarations, salary adjustments, and loan arrangements undertaken shortly before or during the application process will be scrutinised for their impact on declared means.
The form's comprehensive approach means that artificial arrangements designed to reduce apparent wealth are likely to be identified and challenged. The requirement for accountant completion provides an additional layer of professional oversight that helps ensure authentic disclosure.
Understanding the CIV MEANS 1C requirements enables corporate directors and shareholders to prepare thoroughly for legal aid applications, ensuring that all necessary documentation is available and that corporate financial arrangements are clearly documented and defensible. The form's detailed approach, while complex, ultimately serves to ensure that legal aid resources are allocated fairly based on genuine financial need rather than apparent poverty created through corporate structures.
Qualifying Conditions for CIV MEANS 1C Status
The CIV MEANS 1C classification isn't automatically assigned to every company director or shareholder. Specific qualifying conditions must be met, and these vary depending on the type of civil proceedings and the nature of your role within the company structure.
For company directors, eligibility typically requires you to hold an active directorship registered with Companies House at the time of application. This includes executive directors with day-to-day operational responsibilities and non-executive directors who participate in board decisions. However, shadow directors—those who exercise significant influence without formal appointment—may face additional scrutiny regarding their actual control over company finances.
The shareholding threshold varies considerably across different legal aid schemes. In most civil matters, holding any percentage of shares may trigger CIV MEANS 1C classification, but the assessment focuses heavily on your actual financial benefit from those shares. For instance, holding 100 shares in a company with issued capital of 1,000,000 shares carries different implications than holding the same number in a smaller enterprise where you effectively control decision-making.
Particular attention is paid to beneficial ownership arrangements. If you hold shares through nominee arrangements, trust structures, or family members, the Legal Aid Agency will examine the substance of your control rather than just the formal legal title. This includes situations where you may not appear on the company's register of members but exercise significant influence through other family members or business partners who do hold registered shares.
For dormant companies or those in administration, your CIV MEANS 1C status may be reviewed differently. If the company has ceased trading and holds minimal assets, the assessment may focus more on your personal financial resources rather than potential company benefits. However, you'll need to provide comprehensive evidence of the company's dormant status, including recent accounts filed with Companies House and confirmation of cessation of business activities.
Companies House filing history becomes crucial evidence in establishing your qualifying status. Late filing penalties, overdue confirmation statements, or gaps in submitted accounts may indicate either active involvement in company management or, conversely, a lack of genuine control over company affairs. The Legal Aid Agency examines these filing patterns alongside your stated role to verify the accuracy of your CIV MEANS 1C classification.
Financial Assessment Procedures and Company Asset Evaluation
The financial assessment process for CIV MEANS 1C applicants involves a detailed examination of both your personal finances and your potential access to company resources. This dual assessment recognises that company directors and shareholders may have financial capabilities beyond their immediate personal assets.
Your personal financial disclosure follows standard civil legal aid requirements, covering income, savings, property ownership, and regular expenditure. However, additional scrutiny applies to transactions between you and your company, including director's loans, dividend payments, salary arrangements, and any benefits in kind. The Legal Aid Agency will request bank statements covering at least three months, but may extend this period if significant transactions with your company are identified.
The company asset evaluation examines the business's financial position to determine what resources might reasonably be available for legal costs. This includes reviewing the most recent filed accounts, management accounts if available, and current bank balances. For companies with substantial assets or cash reserves, you may be expected to consider whether the company could fund the litigation directly, particularly in matters that benefit the business interests.
Particular complexity arises with intercompany transactions and group structures. If you're involved in multiple companies with cross-shareholdings or shared directorships, the assessment considers the overall financial picture across the entire business network. Transfer pricing between related companies, management charges, and consolidated cash flow positions all factor into the evaluation of your true financial capacity.
For companies trading at a loss or with limited liquid assets, the assessment focuses on contingent liabilities and personal guarantees you may have provided. Director's loan accounts in credit may be treated as readily accessible funds, while overdrawn positions might indicate limited company resources but potential personal liability for repayment.
The timing of your application relative to company financial cycles can significantly impact the assessment outcome. Applications submitted shortly after dividend distributions, major asset disposals, or significant capital injections receive enhanced scrutiny. The Legal Aid Agency may request additional documentation covering extended periods to establish patterns of financial management and resource availability.
Professional valuations may be required for companies holding significant property assets, intellectual property, or specialised equipment. Where company accounts show assets at historical cost that may have appreciated substantially, you might need to provide current market valuations to complete the financial assessment accurately.
Common Challenges and Resolution Strategies
CIV MEANS 1C applications frequently encounter specific challenges that require careful navigation and strategic preparation. Understanding these common obstacles and their resolution approaches can significantly improve your application's success rate and reduce processing delays.
One persistent challenge involves demonstrating separation between personal and business finances, particularly in smaller companies where directors often blur these boundaries. The Legal Aid Agency scrutinises situations where company funds appear to be used for personal expenses, or where personal assets have been used to support business operations. Maintaining clear documentation of all transactions, including formal loan agreements for any personal funds advanced to the company, becomes essential for a successful assessment.
Disputes over beneficial ownership frequently arise in family businesses or partnerships where formal shareholdings don't reflect actual control or financial benefit. For example, you might hold shares nominally on behalf of family members, or conversely, family members might hold shares while you retain operational control. Resolving these situations requires comprehensive documentation including trust deeds, family arrangements, and evidence of who actually receives dividends or makes business decisions.
The timing of company formation or share transfers relative to legal proceedings can raise suspicions about asset protection strategies. If you've recently transferred shares to family members, wound up companies, or restructured business arrangements shortly before legal action commenced, expect additional scrutiny. The Legal Aid Agency examines whether these transactions represent genuine commercial decisions or attempts to minimise assessed financial capacity.
Companies with international elements present particular complexities, especially those incorporated offshore or with overseas subsidiaries. You'll need to provide equivalent documentation for foreign entities, potentially requiring certified translations and confirmations of regulatory compliance in other jurisdictions. The assessment considers global business interests, not just UK-based activities, which can significantly complicate the financial evaluation process.
Resolution strategies for these challenges typically involve proactive disclosure and comprehensive documentation. Rather than waiting for specific requests, successful applicants often provide detailed explanations of complex arrangements upfront, including professional opinions from accountants or solicitors where business structures are particularly sophisticated. This approach demonstrates transparency and can expedite the assessment process.
For ongoing companies facing cashflow difficulties or seasonal trading patterns, timing your application strategically can influence the assessment outcome. Submitting applications during periods when company bank balances are at their lowest legitimate levels, supported by evidence of cyclical trading patterns, may result in more favourable evaluations than applications during peak cash positions.
Where initial assessments prove unfavourable, the review and appeal processes offer opportunities to present additional evidence or clarifications. However, these processes operate within strict timeframes, and gathering additional company documentation can be time-consuming. Planning for potential challenges and preparing comprehensive supporting evidence from the outset proves more effective than attempting to remedy deficiencies during review procedures.