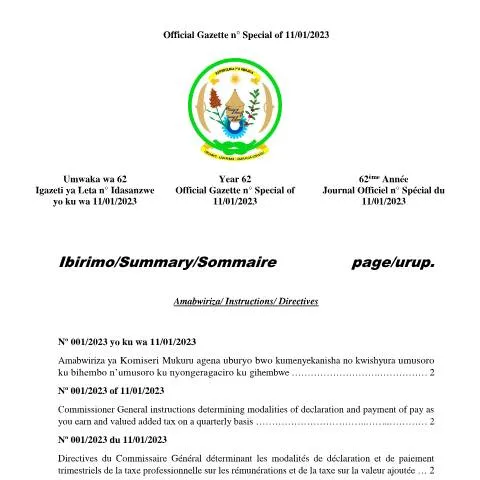
Official Gazette Notice: Regulations on Quarterly Tax Declarations and Payments in Rwanda
The official gazette publication dated 11th January 2023 introduces important directives issued by the Commissioner General of Rwanda Revenue Authority (RRA) concerning the modalities for declaring and paying taxes on remuneration and value-added tax (VAT) on a quarterly basis. These regulations are essential for taxpayers operating within Rwanda’s fiscal framework, especially those subject to PAYE (Pay As You Earn) and VAT obligations.
Context and Scope of the Regulations
This directive, numbered 001/2023, aims to streamline the tax declaration and payment processes, ensuring compliance with the legal provisions set forth in Law No. 026/2019 of 18th September 2019 on Tax Procedures and Law No. 37/2012 of 9th November 2012 establishing the VAT framework. The instructions are designed to facilitate the timely and efficient management of tax obligations for businesses and individuals, contributing to Rwanda’s broader fiscal policy objectives.
Who is Affected by These Regulations?
The directives primarily target taxpayers whose annual turnover is less than or equal to 200 million Rwandan Francs (FRW). This includes small and medium-sized enterprises (SMEs), self-employed individuals, and other entities subject to PAYE and VAT. These taxpayers are required to adhere to the quarterly declaration and payment schedule outlined in the directives, unless they opt for monthly declarations under specific conditions.
Key Provisions and Requirements
Declaration and Payment Schedule
Taxpayers with a turnover of up to 200 million FRW are mandated to declare and settle their PAYE and VAT obligations within 15 days following the end of each quarter. The specific deadlines are as follows:
- First quarter: Declaration and payment due by 15th April
- Second quarter: Due by 15th July
- Third quarter: Due by 15th October
- Fourth quarter: Due by 15th January of the following year
Failure to meet these deadlines may result in penalties or interest charges, emphasizing the importance of timely compliance.
Optional Monthly Declaration
Taxpayers with annual turnover not exceeding 200 million FRW may choose to declare and pay their taxes monthly instead of quarterly. However, this option requires prior registration and approval from the Rwanda Revenue Authority, ensuring proper monitoring and adherence to tax obligations.
Procedures for Declaration
Tax declarations are to be submitted via the electronic platform provided by the Rwanda Revenue Authority, known as Irembo. This digital service facilitates convenient, paperless submission of tax returns, aligning with Rwanda’s commitment to digital government services. Taxpayers must ensure that their declarations are complete and accurate to avoid penalties.
Legal and Administrative References
The directives are grounded in the legal framework provided by Law No. 026/2019 on Tax Procedures, particularly Article 21, which governs the modalities for tax declaration and payment. Additionally, Law No. 37/2012, especially Article 25, establishes the legal basis for VAT declarations. These laws, along with the provisions of the official gazette, reinforce the administrative procedures outlined in this directive.
Implementation and Enforcement
The Rwanda Revenue Authority is responsible for overseeing the implementation of these regulations. Taxpayers are advised to regularly consult official communications and utilize the Irembo platform to ensure compliance. Non-compliance may lead to administrative sanctions, including fines or other penalties as stipulated by law.
Conclusion
The January 2023 directives mark a significant step towards enhancing Rwanda's tax administration, promoting transparency, and encouraging timely compliance among taxpayers. By adhering to these regulations, taxpayers contribute to the stability and development of Rwanda’s fiscal system, supporting national efforts for economic growth and good governance.