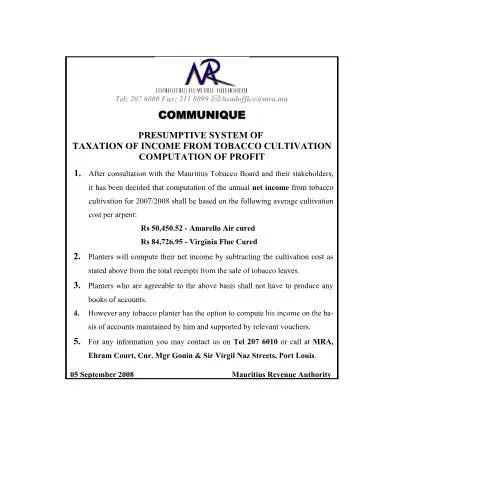
Official Notice on the Taxation of Income from Tobacco Cultivation in Mauritius
This official communication issued by the Mauritius Revenue Authority (MRA) on 5 September 2008 provides essential guidance for tobacco planters regarding the computation of their income for taxation purposes for the fiscal year 2007/2008. It aims to clarify the method of calculating taxable income from tobacco cultivation, highlighting the presumptive taxation system adopted following consultations with the Mauritius Tobacco Board and relevant stakeholders.
Scope and Purpose of the Notice
The primary objective of this notice is to inform tobacco growers about the simplified process for determining their net income from tobacco cultivation, which is subject to taxation under the prevailing legal framework managed by the Mauritius Revenue Authority. It specifies the approved methodology for calculating profit, thereby facilitating compliance and streamlining the tax assessment process for planters involved in tobacco farming.
Applicable Cultivation Costs for the 2007/2008 Tax Year
According to the notice, the computation of net income will be based on an average cultivation cost per arpent, a traditional local unit of land measurement. The prescribed costs are as follows:
- Rs 50,450.52 for Amarello Air Cured tobacco
- Rs 84,726.95 for Virginia Flue Cured tobacco
These figures have been established after consultations with the Mauritius Tobacco Board and are intended to reflect typical cultivation expenses for the respective tobacco types during the specified period.
Methodology for Computing Income
Standard Calculation Approach
Planters are required to determine their taxable income by subtracting the applicable cultivation cost from the total proceeds obtained from the sale of tobacco leaves. This straightforward calculation simplifies the process by eliminating the need for detailed bookkeeping for those who accept the presumptive basis.
Option for Detailed Accounting
While the presumptive system offers a simplified method, tobacco planters retain the option to compute their income based on actual accounts maintained by them. In such cases, they must support their calculations with relevant vouchers and documentation, ensuring transparency and accuracy in their tax declarations.
Implications for Tobacco Planters
This notice provides clarity on the administrative procedures for tobacco farmers, emphasizing that those willing to adopt the presumptive system will not be required to produce detailed books of accounts. Conversely, planters who prefer or are required to maintain detailed records can do so, provided they can substantiate their income calculations with appropriate vouchers and supporting documents.
Contact and Further Information
For additional guidance or clarification regarding the taxation process, planters are encouraged to contact the Mauritius Revenue Authority directly. The contact details are as follows:
- Telephone: 207 6010
- Location: MRA, Ehram Court, Corner of Mgr Gonin and Sir Virgil Naz Streets, Port Louis
Official correspondence can also be directed via email to [email protected] for further assistance.
Legal and Administrative Context
This notice aligns with the legal framework governing taxation in Mauritius, particularly under the provisions of the Mauritius Revenue Authority Act and related fiscal regulations. It reflects an administrative approach that balances simplicity with flexibility, allowing tobacco planters to choose between a presumptive system and detailed accounting, depending on their circumstances.
By providing clear guidelines and establishing standardized costs, the Mauritius Revenue Authority aims to facilitate compliance, reduce administrative burdens for small-scale planters, and ensure fair taxation based on the actual income derived from tobacco cultivation.
Summary of Key Points
- The taxation system for tobacco cultivation income for 2007/2008 is based on an average cultivation cost per arpent.
- Planters can opt for a presumptive calculation method or maintain detailed accounts supported by vouchers.
- Contact details are provided for further assistance or inquiries.
- This initiative supports transparency and administrative efficiency in tax collection from tobacco growers.