Official Notice on the Taxation of Income from Sugar Cane Cultivation in Mauritius
Introduction and Context
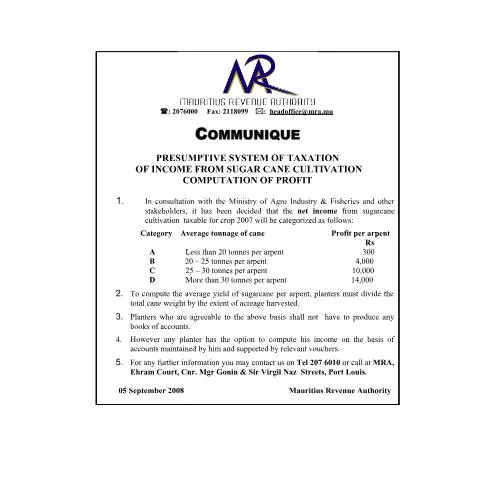
This official communication, issued by the Mauritius Revenue Authority (MRA) on 5 September 2008, provides guidance to sugarcane planters regarding the taxation of income derived from sugar cane cultivation for the crop year 2007. It aims to clarify the computation method for taxable income based on a presumptive system, which simplifies the tax reporting process for farmers and cultivators engaged in sugarcane farming.
Scope and Purpose of the Notice
The notice is intended for all sugarcane planters operating within Mauritius who are subject to income tax obligations. It establishes a standardized framework for calculating taxable income, thereby streamlining the assessment process and reducing the administrative burden on individual cultivators. The document also emphasizes the collaborative approach taken with stakeholders, including the Ministry of Agro Industry & Fisheries, to develop a practical and equitable taxation method.
Key Provisions and Computation Method
The core of this notice lies in the categorization of net income based on the average yield of sugarcane per arpent, a traditional measurement unit in Mauritius. The calculation is straightforward and relies on the following parameters:
| Category | Average Tonnage of Cane per Arpent | Profit per Arpent (Rs) |
|---|---|---|
| A | Less than 20 tonnes | 300 |
| B | 20 – 25 tonnes | 4,000 |
| C | 25 – 30 tonnes | 10,000 |
| D | More than 30 tonnes | 14,000 |
To determine the average yield, planters must divide the total weight of harvested cane by the extent of the cultivated area, measured in arpents. This calculation facilitates the classification into one of the four categories, which then determines the taxable profit per arpent.
Options for Taxpayers
Planters who agree with this presumptive basis for calculation are not required to maintain detailed books of accounts. This provision significantly simplifies compliance, especially for smallholders. However, the notice also offers an alternative: cultivators may choose to compute their taxable income based on their own maintained accounts, supported by relevant vouchers and documentation. This option provides flexibility for those who prefer or are able to substantiate their income through detailed record-keeping.
Contact and Further Information
For additional guidance or clarification, planters and stakeholders are encouraged to contact the Mauritius Revenue Authority directly. The official contact details are as follows:
- Telephone: 207 6010
- Physical Address: Ehram Court, Corner of Mgr Gonin and Sir Virgil Naz Streets, Port Louis
- Email: [email protected]
It is important for all sugarcane cultivators to adhere to this guidance to ensure compliance with the tax regulations applicable to the crop year 2007. The MRA remains committed to facilitating a fair and transparent taxation process, balancing administrative efficiency with taxpayer rights.
Legal and Administrative References
This notice is issued under the authority of the Mauritius Revenue Authority and is part of the broader fiscal framework established by the country's tax laws. It aligns with the Government's efforts to promote a simplified taxation system for agricultural income, consistent with the legal provisions contained in the Mauritius Revenue Authority Act and related fiscal legislation.