Overview of the Taxation Notice on Income from Tobacco Cultivation in Mauritius
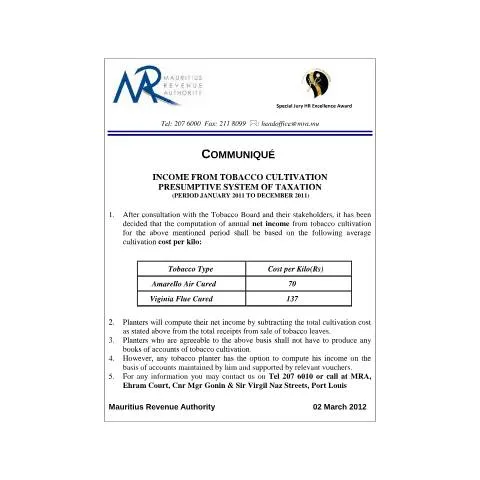
This official notice issued by the Mauritius Revenue Authority (MRA) on 2 March 2012 provides essential guidance for tobacco planters regarding the taxation of income derived from tobacco cultivation for the fiscal year covering January to December 2011. It aims to clarify the method of income calculation, the applicable costs, and the options available to planters for reporting their income, thereby ensuring compliance with the tax regulations under the Mauritian legal framework.
Context and Scope of the Notice
The notice addresses tobacco growers operating within Mauritius, outlining the presumptive system of taxation applicable to their income from tobacco cultivation. This system was established following consultations with the Tobacco Board and relevant stakeholders to streamline the taxation process and reduce administrative burdens for planters. It covers the income derived from the sale of tobacco leaves during the specified period and provides a simplified approach to calculating taxable income based on standardized cultivation costs.
Who Is Affected by This Notice?
This communication is intended primarily for tobacco planters registered with the Mauritius Revenue Authority who cultivate tobacco for commercial purposes. It also serves tax professionals and auditors involved in the assessment and verification of income declarations related to tobacco cultivation activities. The notice applies to all planters for the fiscal year ending 30 June 2012, with the relevant period being January to December 2011.
Key Provisions and Procedures
Calculation of Income Using Presumptive Costs
Planters are instructed to determine their net income from tobacco cultivation by subtracting predefined cultivation costs from their total sales receipts. The prescribed costs per kilogram are as follows:
- Amarello Air Cured: Rs 70 per kilo
- Virginia Flue Cured: Rs 137 per kilo
This approach simplifies the process by eliminating the need for detailed books of accounts for those who accept this method.
Options for Income Computation
- Presumptive System: Planters who agree to use the standardized cultivation costs can compute their net income by deducting these costs from their total sales receipts. They are not required to produce detailed records or vouchers to substantiate their expenses.
- Actual Accounts: Alternatively, planters may choose to maintain their own books of accounts, supported by relevant vouchers, to calculate their income based on actual expenses incurred. This option provides flexibility for those who prefer detailed record-keeping or have expenses differing from the standard costs.
Implications for Tobacco Planters
Adopting the presumptive system offers a simplified tax reporting process, reducing administrative burdens and facilitating compliance. However, planters retain the right to opt for detailed accounting if they believe it will result in a more accurate reflection of their income. The choice should be made considering the individual circumstances of each planter and their record-keeping capacity.
Contact and Further Information
For additional guidance or clarifications regarding this notice, planters and stakeholders are encouraged to contact the Mauritius Revenue Authority directly. The designated contact numbers are Tel: 207 6000 for general inquiries and Tel: 207 6010 for specific questions related to tobacco cultivation taxation. The MRA office is located at Ehram Court, at the corner of Mgr Gonin and Sir Virgil Naz Streets, Port Louis.
Legal and Administrative References
This notice is issued under the authority of the Mauritius Revenue Authority, which administers tax regulations in accordance with the provisions of the Mauritius Revenue Authority Act and relevant fiscal laws. It provides official guidance to ensure that tobacco planters adhere to the legal requirements for income declaration and tax payment for the specified period.
Planters are advised to keep abreast of any updates or amendments issued by the MRA, especially as the government continues to promote digital services and e-filing through the govmu.org portal, aligning with the national objectives for modernized tax administration.