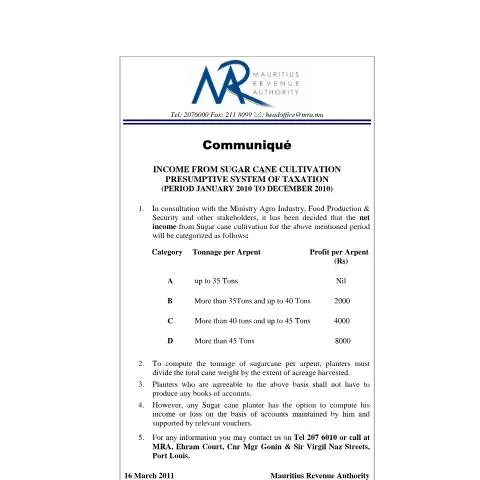
Official Notice on the Taxation of Sugarcane Cultivation in Mauritius
This official communication issued by the Mauritius Revenue Authority (MRA) provides essential guidance to sugarcane planters regarding the presumptive taxation system applicable for the period from January 2010 to December 2010. It aims to clarify how income derived from sugarcane cultivation will be assessed and the options available to planters for reporting their income for tax purposes.
Objective and Scope of the Notice
The primary purpose of this notice is to inform sugarcane cultivators about the categorization of their net income based on the tonnage of sugarcane harvested per arpent. It establishes a simplified, presumptive taxation framework designed to ease compliance for planters and streamline the tax assessment process. The notice applies to all registered sugarcane growers who cultivated sugarcane during the specified period and are subject to income tax regulations under the jurisdiction of the Mauritius Revenue Authority.
Taxation Categories Based on Tonnage
The notice classifies sugarcane producers into four distinct categories, each associated with a different profit threshold per arpent, depending on the amount of sugarcane harvested. This classification simplifies the calculation of taxable income by associating specific profit levels with measurable quantities of cane, thereby reducing the administrative burden on both the taxpayer and the tax authorities.
Details of the Categorization
| Category | Tonnes per Arpent | Profit per Arpent (Rs) |
|---|---|---|
| A | Up to 35 Tons | Nil |
| B | More than 35 and up to 40 Tons | 2,000 |
| C | More than 40 and up to 45 Tons | 4,000 |
| D | More than 45 Tons | 8,000 |
This classification allows planters to estimate their taxable income based on measurable harvest quantities, facilitating a straightforward approach to tax reporting.
Methodology for Calculating Tonnage
To determine the amount of sugarcane harvested per arpent, planters are instructed to divide the total weight of the cane harvested by the size of the cultivated area in arpents. This calculation is essential for categorizing the income and applying the relevant profit threshold under the presumptive system.
Options for Taxpayers: Presumptive vs. Actual Accounts
Planters who agree with the presumptive categorization and profit thresholds are not required to maintain detailed books of accounts. This option simplifies compliance and reduces administrative efforts. However, the notice also provides an alternative for planters who prefer to compute their income or loss based on actual accounts maintained with supporting vouchers and relevant documentation.
In such cases, the taxpayer must maintain proper accounting records and supporting vouchers to substantiate their income and expenses. This option offers flexibility for planters with more complex financial arrangements or those who believe their actual income exceeds the presumptive figures.
Contact and Further Information
For additional guidance or clarification regarding the taxation procedures, planters are encouraged to contact the Mauritius Revenue Authority directly. The official contact details are as follows:
- Telephone: 207 6010
- Physical Office: Ehram Court, Corner of Mgr Gonin & Sir Virgil Naz Streets, Port Louis
- Email: [email protected]
It is recommended that planters stay informed about updates to taxation policies and ensure compliance with the prescribed procedures to avoid penalties or discrepancies during tax assessments.
Conclusion
This notice emphasizes the Mauritius Revenue Authority’s commitment to facilitating tax compliance among sugarcane growers through simplified, transparent procedures. By adopting the presumptive system based on harvest tonnage, the MRA aims to streamline tax collection, reduce administrative burdens, and promote fair taxation practices within the sugarcane sector.