Official Notice on the Taxation of Income from Sugar Cane Cultivation in Mauritius
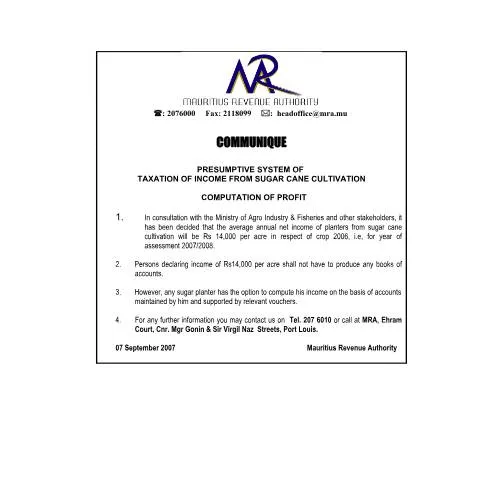
This official communication from the Mauritius Revenue Authority (MRA), dated 7 September 2007, provides crucial guidance on the taxation framework applicable to income generated from sugar cane cultivation during the fiscal year 2006/2007. It aims to clarify the presumptive taxation system introduced for planters and to outline the procedures for calculating taxable income, thereby ensuring compliance with the tax laws in Mauritius.
Scope and Application of the Presumptive Taxation System
The notice specifically addresses sugar cane planters operating within Mauritius and establishes a simplified method for determining taxable income from sugar cane cultivation. This system is designed to streamline tax compliance for small to medium-scale planters by applying a standard income figure, thereby reducing the administrative burden associated with detailed record-keeping and book maintenance.
According to the communication, the presumptive income is set at an average of Rs 14,000 per acre for the crop year 2006, which corresponds to the assessment year 2007/2008. This standard figure is intended to reflect a reasonable estimate of net income derived from sugar cane cultivation, based on consultations with the Ministry of Agro Industry & Fisheries and other relevant stakeholders.
Key Provisions and Options for Planters
Declaration of Income
Planters who declare an income of Rs 14,000 per acre for the relevant assessment year will benefit from a simplified tax process. Specifically, they will not be required to produce detailed books of accounts or supporting vouchers, thereby easing their compliance obligations.
Option for Actual Income Computation
Despite the standard presumptive income, planters retain the right to opt for a more detailed approach. They may choose to compute their taxable income based on their maintained accounts and supported by relevant vouchers and receipts. This flexibility allows larger or more organized planters to declare income reflective of their actual expenses and revenues, potentially resulting in a different taxable amount.
Implications for Sugar Cane Planters
This notice signifies a shift towards a simplified taxation process for sugar cane growers, especially those with smaller or less formal operations. By providing a clear, standardized income figure, the Mauritius Revenue Authority aims to facilitate compliance, reduce administrative costs, and promote transparency within the sector.
Planters are encouraged to review their income declarations carefully and consider whether the presumptive system aligns with their actual income. Those opting for the standard Rs 14,000 per acre will benefit from a straightforward process, while those with more complex financial records can choose to declare income based on their books.
Contact and Further Information
For additional guidance or clarifications regarding the presumptive taxation system, planters and stakeholders are advised to contact the Mauritius Revenue Authority. The relevant contacts are:
- Telephone: 207 6010
- Physical Office: Ehram Court, Corner of Mgr Gonin and Sir Virgil Naz Streets, Port Louis
- Email: [email protected]
It is important for all sugar cane growers to stay informed about tax obligations and to ensure their declarations are in compliance with the relevant legal provisions. The MRA remains committed to supporting taxpayers through clear communication and accessible services.
Conclusion
This official notice underscores the Mauritian government’s efforts to simplify the taxation process for the agricultural sector, particularly sugar cane cultivation. By establishing a presumptive income system, the authorities aim to promote compliance, reduce administrative burdens, and support sustainable growth within the sector. Planters are advised to assess their options carefully and seek guidance if necessary to ensure proper adherence to the tax regulations for the assessment year 2007/2008.