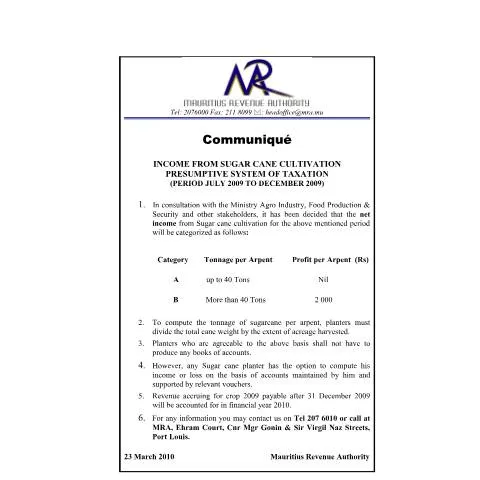
Official Notice: Presumptive Tax System for Sugarcane Cultivation (July 2009 – December 2009)
This official communication from the Mauritius Revenue Authority (MRA), dated 23 March 2010, provides essential guidance to sugarcane planters concerning the presumptive taxation system applicable to the income derived from sugarcane cultivation during the period from July 2009 to December 2009. It aims to clarify the categorization of income based on the tonnage of sugarcane harvested per arpent, thereby simplifying the tax calculation process for eligible planters.
Context and Scope of the Presumptive Taxation System
The Mauritius Revenue Authority, in collaboration with the Ministry of Agro-Industry, Food Production & Security and other stakeholders, has established a simplified tax regime for sugarcane cultivators for the specified crop cycle. This measure seeks to streamline tax compliance and reduce administrative burdens for small-scale planters, while ensuring fair taxation based on actual production levels.
The system applies exclusively to sugarcane cultivated during the crop year from July 2009 to December 2009. It introduces a presumptive approach where income is estimated based on the tonnage harvested, rather than detailed accounting records, although options for detailed accounting remain available.
Who is Affected by This Notice?
- Small and medium-scale sugarcane planters operating within the designated period.
- Planters who choose to opt into the presumptive system by accepting the categorization criteria outlined in this notice.
- Any sugarcane farmer wishing to maintain detailed accounts may do so, provided they support their calculations with relevant vouchers and documentation.
Key Provisions and Calculation Methodology
The notice delineates two income categories based on the tonnage of sugarcane harvested per arpent:
| Category | Tonnage per Arpent | Profit per Arpent (Rs) |
|---|---|---|
| A | Up to 40 Tons | Nil |
| B | More than 40 Tons | 2,000 |
To determine the tonnage per arpent, planters must divide the total weight of harvested cane by the number of arpents harvested. This calculation provides the basis for categorizing the income and applying the corresponding tax liability.
Options for Planters and Record-Keeping
Planters who accept the presumptive system as outlined above are not required to maintain detailed books of accounts. However, they may opt to compute their income or loss based on actual accounts, supported by relevant vouchers. This alternative provides flexibility for those who prefer a more precise calculation of their taxable income.
Tax Payment and Fiscal Year Considerations
Income generated from sugarcane cultivation for the crop year 2009, payable after 31 December 2009, will be recorded in the fiscal year 2010. This aligns with the government’s fiscal calendar, which runs from 1 July to 30 June each year.
Contact and Further Information
For additional guidance or clarification regarding the presumptive taxation system, planters and stakeholders are encouraged to contact the Mauritius Revenue Authority at the following:
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
- Telephone: 207 6010
- Visit: MRA, Ehram Court, Corner of Mgr Gonin & Sir Virgil Naz Streets, Port Louis
Alternatively, inquiries can be directed via email to [email protected].
Summary and Implications
This notice underscores Mauritius’s efforts to facilitate tax compliance among sugarcane farmers through a simplified presumptive system. By categorizing income based on harvest tonnage, the system aims to balance administrative efficiency with equitable taxation. Planters are advised to assess whether to accept the presumptive basis or maintain detailed records, depending on their individual circumstances.
It remains essential for all affected parties to stay informed of official directives and to ensure accurate reporting within the stipulated periods, thereby supporting the country’s broader fiscal and agricultural policies.