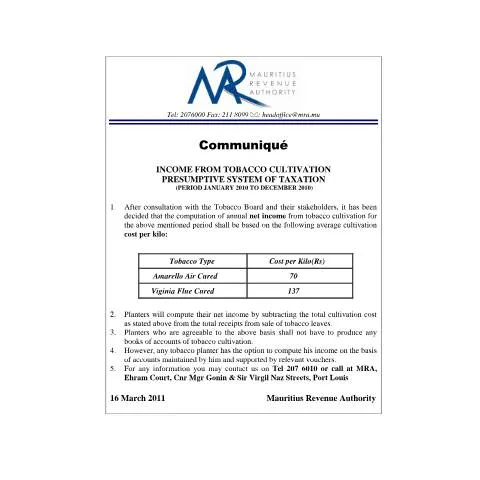
Official Notice on Tobacco Taxation in Mauritius
This official communication, issued by the Mauritius Revenue Authority (MRA) on 16 March 2011, provides essential guidance to tobacco cultivators regarding the taxation system applicable to income derived from tobacco cultivation for the fiscal year 2010. It aims to clarify the presumptive taxation method adopted following consultations with the Tobacco Board and relevant stakeholders, ensuring transparency and ease of compliance for tobacco planters across the country.
Scope and Purpose of the Notice
The primary objective of this notice is to inform tobacco farmers about the new presumptive system of taxation introduced for the period from January 2010 to December 2010. It delineates the calculation method for assessing taxable income based on standardized cultivation costs, thereby simplifying the tax reporting process for planters and reducing administrative burdens. This initiative aligns with the government's broader efforts to promote formalization and compliance within the agricultural sector, particularly for tobacco cultivation.
Application of the Presumptive Taxation System
The system applies specifically to tobacco planters who cultivate the two main types of tobacco recognized under this scheme:
- Amarello Air Cured
- Virginia Flue Cured
For these categories, the taxation approach involves calculating the net income by using an average cultivation cost per kilogram, which has been standardized for the period in question. This method is intended to streamline tax calculations and reduce the need for detailed bookkeeping for those who accept the presumptive basis.
Calculation Method and Key Provisions
Standardized Cultivation Costs
The prescribed average costs per kilogram are as follows:
| Tobacco Type | Cost per Kilo (Rs) |
|---|---|
| Amarello Air Cured | 70 |
| Virginia Flue Cured | 137 |
Income Computation
Planters opting for this presumptive system are required to determine their net income by subtracting the total cultivation costs—calculated using the above averages—from the gross receipts obtained from the sale of tobacco leaves. This approach simplifies the process by eliminating the need for detailed accounting records for those who agree to the presumptive basis.
Options for Taxpayers
While the presumptive system offers a simplified calculation method, tobacco planters retain the option to compute their income based on actual accounts maintained throughout the cultivation period. Such account-based calculations must be supported by relevant vouchers and documents, allowing for a more precise assessment should the taxpayer choose this route.
Implications for Tobacco Planters
This notice significantly impacts tobacco farmers by providing a clear, standardized method for calculating taxable income. Farmers who accept the presumptive system benefit from a streamlined process, reducing the administrative effort involved in tax reporting. Conversely, those who prefer to maintain detailed accounts retain the flexibility to do so, ensuring that all taxpayers can choose the approach best suited to their circumstances.
Contact and Further Information
For any inquiries or clarifications regarding the taxation procedures or to obtain additional guidance, tobacco planters are encouraged to contact the Mauritius Revenue Authority. The official contact points include:
- Telephone: 207 6010
- Physical Office: Ehram Court, Corner Mgr Gonin & Sir Virgil Naz Streets, Port Louis
- Email: [email protected]
This communication underscores the government’s commitment to supporting the agricultural sector through clear, accessible, and equitable tax policies, fostering compliance while simplifying administrative processes for tobacco cultivators across Mauritius.