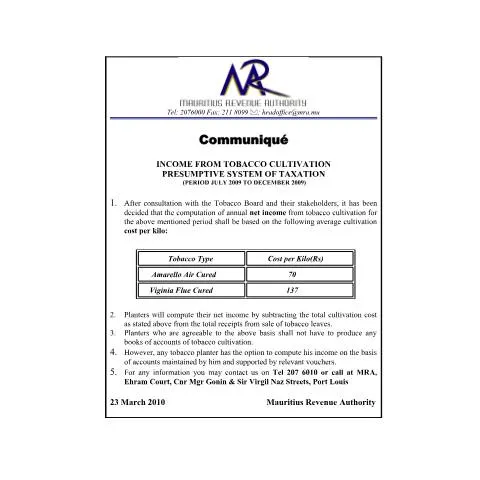
Official Notice on the Presumptive Taxation System for Tobacco Cultivation in Mauritius
This official communication, issued by the Mauritius Revenue Authority (MRA) on 23 March 2010, provides important guidance regarding the taxation method applicable to tobacco cultivators for the period from July 2009 to December 2009. It aims to clarify the approach adopted for calculating taxable income based on a presumptive system, which simplifies the tax reporting obligations for eligible tobacco planters.
Context and Scope of the Notice
In Mauritius, the cultivation of tobacco is subject to specific taxation regulations, designed to streamline compliance and ensure fair revenue collection. Recognizing the diverse scale of tobacco farming operations, the MRA, after consultation with the Tobacco Board and relevant stakeholders, has implemented a presumptive system of taxation for the specified period. This system is intended to facilitate ease of compliance for planters, particularly small-scale farmers, by establishing a standardized basis for income calculation, thereby reducing the administrative burden associated with detailed bookkeeping.
Who Is Affected by This Notice?
This notice primarily concerns tobacco cultivators who engaged in tobacco farming during the second half of 2009. These include planters who sell tobacco leaves and are subject to income tax under the provisions applicable to tobacco cultivation. The guidance is relevant for those who wish to benefit from the simplified presumptive system as well as for those who prefer to maintain detailed accounts.
Key Provisions and Operational Details
Calculation of Income Based on Presumptive Costs
According to the notice, the taxable income for tobacco farmers will be computed by applying a standard cost per kilogram to their total sales receipts. The prescribed costs are as follows:
| Tobacco Type | Cost per Kilogram (Rs) |
|---|---|
| Amarello Air Cured | 70 |
| Virginia Flue Cured | 137 |
Farmers will determine their net income by subtracting the total cultivation costs, calculated using these standard rates, from their total revenue obtained from the sale of tobacco leaves.
Options for Taxpayers
- Planters who agree to utilize this presumptive basis are not required to produce detailed books of accounts or supporting vouchers for their cultivation expenses.
- However, farmers retain the option to compute their income based on detailed accounts maintained by themselves, supported by relevant vouchers and documentation. This alternative method is available for those who prefer a more detailed approach or wish to claim actual costs.
Implications for Tobacco Planters
This notice simplifies the tax process for eligible tobacco farmers by providing a clear, standardized method for income calculation. It encourages compliance by reducing administrative burdens and offering flexibility. Farmers must decide whether to adopt the presumptive system or maintain detailed accounts, based on their individual circumstances.
Contact and Further Information
For additional guidance or clarification regarding the presumptive taxation system for tobacco cultivation, planters are advised to contact the Mauritius Revenue Authority at the following:
- Telephone: 207 6010
- Physical Address: Ehram Court, Corner Mgr Gonin & Sir Virgil Naz Streets, Port Louis
- Email: [email protected]
This communication underscores the MRA’s commitment to facilitating tax compliance through clear, accessible procedures, aligned with the national fiscal policies and aimed at supporting the agricultural sector.