Introduction to the Presumptive System of Taxation for Sugar Cane Cultivation in Mauritius
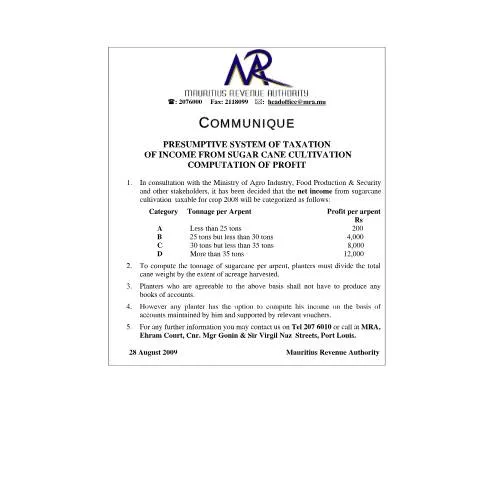
The Mauritius Revenue Authority (MRA) has issued a formal notice concerning the implementation of a presumptive taxation system specifically designed for income derived from sugar cane cultivation for the crop year 2008. This initiative aims to streamline the taxation process for planters and ensure a fair and simplified method of calculating taxable income, in collaboration with relevant governmental bodies such as the Ministry of Agro Industry, Food Production & Security.
Scope and Purpose of the Notice
This official communication outlines the criteria and procedures for determining the taxable net income from sugarcane farming, based on a presumptive system that categorizes planters according to their harvest tonnage per arpent of cultivated land. The primary goal is to facilitate compliance and reduce administrative burdens by providing clear, standardized income computation methods tailored to different levels of production.
Who Is Affected by This System?
The notice primarily concerns all sugarcane planters operating within Mauritius for the crop year 2008. These individuals or entities engaged in sugarcane cultivation are encouraged to adopt the prescribed presumptive basis for income calculation, although they retain the option to maintain detailed accounts if they prefer a different method.
Key Provisions and Income Categories
The system classifies planters into four categories based on their annual harvest per arpent, with corresponding profit estimates as follows:
| Category | Tonnage per Arpent | Profit per Arpent (Rs) |
|---|---|---|
| A | Less than 25 tons | 200 |
| B | 25 tons but less than 30 tons | 4,000 |
| C | 30 tons but less than 35 tons | 8,000 |
| D | More than 35 tons | 12,000 |
To determine the tonnage of sugarcane produced per arpent, planters are instructed to divide the total weight of their harvest by the extent of the cultivated land. This calculation forms the basis for categorizing their production and applying the corresponding profit level.
Options for Taxpayers and Record-Keeping
- Simplified Approach: Planters who agree to adopt the above presumptive method are not required to maintain detailed books of accounts. This simplifies compliance and reduces administrative overhead.
- Alternative Method: Alternatively, planters may choose to compute their taxable income based on their own maintained accounts supported by relevant vouchers and documentation. This option allows for a more precise calculation if desired.
Implementation and Contact Information
This presumptive taxation system is effective for the crop year 2008, with the official notice issued on 28 August 2009. For further clarification or assistance regarding the application of these provisions, planters and stakeholders are encouraged to contact the Mauritius Revenue Authority at the following:
- Telephone: 207 6010
- Physical Office: Ehram Court, Corner of Mgr Gonin and Sir Virgil Naz Streets, Port Louis
- Email: [email protected]
Legal and Administrative Context
This notice is issued under the authority of the Mauritius Revenue Authority and aligns with the legal framework governing taxation and agricultural activities in Mauritius. It reflects a collaborative effort with the Ministry of Agro Industry, Food Production & Security to promote fair taxation practices and support the agricultural sector through simplified compliance mechanisms.
Conclusion
The presumptive system introduced for sugar cane cultivation represents a significant step towards modernizing tax administration for farmers in Mauritius. By categorizing income based on harvest volume and offering simplified procedures, the system aims to foster transparency, reduce compliance costs, and ensure equitable taxation for all stakeholders involved in sugarcane farming during the 2008 crop year.