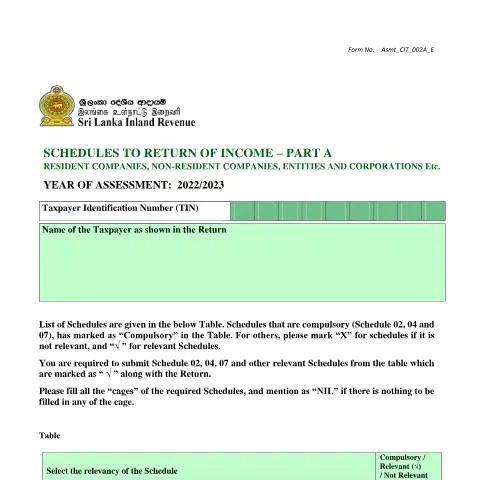
The Integral Role of the Schedules to Return of Income – Part A
The Schedules to Return of Income – Part A (Form Code: Asmt_CIT_002A_E) holds significant importance in the realm of taxation for both Resident and Non-Resident Companies, Entities, and Corporations in Sri Lanka. This document serves as a comprehensive tool for the accurate declaration of income and tax liabilities for a given year of assessment, specifically for the year 2022/2023.
Taxpayers utilize this form to provide detailed insights into their financial activities, helping the Inland Revenue Department (IRD) assess their tax obligations. The schedules included within this form not only clarify the nature of various incomes but also ensure compliance with the provisions outlined in the Inland Revenue Act.
The completion and submission of the Schedules to Return of Income is essential for accurate tax calculation, potentially influencing tax credits and the overall liability of the company or entity involved. Each section presents distinct requirements that align with specific tax regulations, thereby fostering transparency and accountability in the financial reporting process.
Understanding the Submission Process: Hierarchy and Dependencies
Filling out the Schedules to Return of Income is not an isolated task; it is a pivotal step within a broader framework of tax compliance. Taxpayers must first obtain a valid Taxpayer Identification Number (TIN) and ensure that all mandatory schedules are accurately filled out before submission. The schedules can be categorized as compulsory or optional based on their relevance to the taxpayer's financial circumstances.
The compulsory schedules—namely Schedule 02, Schedule 04, and Schedule 07—must be submitted alongside the main return. These forms act as the foundation upon which the rest of the filing rests. In contrast, other schedules may be marked as “relevant” or “not relevant,” depending on the taxpayer's specific situation.
Failure to submit the required schedules or errors within them can lead to significant repercussions, including fines or increased scrutiny from the IRD. Therefore, understanding the hierarchy of schedules and their dependencies is crucial for a successful submission.
Navigating Submission Channels: Digital vs. Physical
In today’s digital era, the IRD in Sri Lanka has emphasized the importance of online submissions through its designated portal, which allows taxpayers to file their returns electronically. This method streamlines the process, reduces paperwork, and ensures quicker processing times.
However, there are still provisions for submitting physical copies at designated IRD offices. Taxpayers opting for this route must ensure that all required documents are organized and complete, as manual submissions may be subject to additional scrutiny. Below is a comparison of both submission methods:
| Submission Method | Advantages | Disadvantages |
|---|---|---|
| Online Submission |
|
|
| Physical Submission |
|
|
Choosing the right submission method is contingent upon the taxpayer’s capabilities and preferences, though the online submission is increasingly becoming the norm due to its efficiency.
Differentiating Between Related Documents: What Sets This Form Apart?
Within the landscape of taxation forms in Sri Lanka, the Schedules to Return of Income are often conflated with other related documents, such as the annual financial statements or the simplified income tax return. However, the specificities of the Asmt_CIT_002A_E form serve distinct purposes.
While annual financial statements provide a comprehensive overview of a company’s financial performance and position, the Schedules to Return of Income focus explicitly on income reporting and associated tax liabilities. The following points elucidate the distinctions:
- Purpose: The Schedules aim to summarize assessable income for tax reporting, whereas financial statements offer a broader view of financial health.
- Structure: The Schedules contain dedicated sections for various income types and losses, requiring careful categorization depending on the taxpayer’s circumstances.
- Regulatory Compliance: The Schedules are mandated under specific provisions of the Inland Revenue Act, while financial statements are governed by international accounting standards.
Taxpayers must be cognizant of these differences when preparing their submissions to the IRD, ensuring they meet all tax obligations promptly and accurately.
A Deep Dive into the Form's Sections: Filling Out Each Cage
The form consists of multiple sections, each designed to capture specific financial information pertinent to tax obligations. A thorough understanding of each section is critical to avoid misrepresentation or errors that could lead to penalties.
Let’s explore the key sections of the Schedules to Return of Income, highlighting necessary information and common pitfalls:
Schedule 01: Exempt Amounts, Gains & Profits or Exempt Losses
This section allows taxpayers to declare any exempt amounts or losses that may affect their overall tax liability. It's crucial to categorize these accurately, as misreporting can lead to significant tax implications.
Common mistakes in this section include:
- Failing to accurately identify exempt amounts under the Third Schedule of the Inland Revenue Act, No. 24 of 2017.
- Inaccurate reporting of exempt losses, which can skew taxable income calculations.
Schedule 02: Summary of Assessable Income
This compulsory schedule serves as a summary of all assessable income, including business, investment, and other income types. Taxpayers must ensure that all gains and profits are comprehensively listed.
Taxpayers often overlook the importance of:
- Accurate classification of income types, as this affects applicable tax rates.
- Including all forms of income, especially those sourced internationally, which may require separate disclosure under Section 74 of the IR Act.
Schedule 04: Tax on Taxable Income
This schedule is crucial for determining the tax payable on the declared taxable income. Taxpayers need to ensure that all computations are based on the latest tax rates and regulations.
When completing this section, it is essential to:
- Keep abreast of any changes in tax rates that might affect current assessments.
- Review all income declarations for accuracy to prevent over or underpayment of taxes.
Schedule 07: Tax Credits
Here, taxpayers claim any credits they may have accrued, which will offset their tax liabilities. This section can significantly reduce the overall tax burden if filled out correctly.
To optimize this section, ensure that:
- All documentation supporting claims for tax credits is compiled and up-to-date.
- Any foreign tax credits are reported accurately, adhering to the relevant stipulations of the Inland Revenue Act.
Preparing Supporting Documents: A Comprehensive Checklist
Along with the Schedules to Return of Income, taxpayers must submit supporting documents to substantiate their claims. Below is a categorized checklist to ensure thorough preparation:
Documentation for Resident Companies
- Business registration details
- Financial statements for the reporting year
- Evidence of exempt amounts or losses claimed
Documentation for Non-Resident Companies
- Proof of income sources
- Tax residency certificates, if applicable
- Any agreements under the BOI Act if relevant
Handling Complex Situations: Special Cases and Urgency
Not all submissions are straightforward; taxpayers may sometimes encounter unique situations requiring careful navigation. Here are some special considerations:
- Foreign Entities: Non-resident companies must adhere to additional regulations regarding sourced income. Collect necessary documentation to substantiate foreign income declarations.
- Minors: Corporations owned by minors may require special considerations under local laws, ensuring proper guardianship and representation.
- Urgent Submissions: For taxpayers facing impending deadlines, electronic submissions may offer a quicker resolution. It is advisable to prepare prior documentation well in advance to minimize last-minute issues.
Addressing Refusals and Rectifications: What to Do When Issues Arise
In the event of submission refusals or requests for further information from the IRD, taxpayers must act promptly to rectify the situation. Here’s a structured approach:
- Review any correspondence from the IRD to understand the basis of refusal.
- Gather the requisite documentation or information requested, ensuring it is accurate and complete.
- Submit the additional information through the recommended channels, whether digitally or physically.
- Keep records of all communications and submissions for future reference.
Understanding the Importance of Schedules to Return of Income
The Schedules to Return of Income, particularly Part A (Asmt_CIT_002A_E), play a crucial role in the context of corporate taxation in Sri Lanka. These schedules ensure that companies and corporate entities adhere to the requirements set forth by the Department of Inland Revenue (DIR). They form an integral part of the annual income tax return process, allowing the DIR to assess the income, expenditures, and other financial data of corporations accurately.
Part A specifically focuses on capturing a comprehensive overview of the taxpayer's income sources, deductions, and credits applicable during the financial year. This detailed information assists the government in formulating fiscal policies, thereby impacting public spending and economic growth. Furthermore, proper completion of these schedules can expedite the review process, minimizing the likelihood of audits and reducing the time taken to receive tax assessments.
Key Obligations for Submission of Schedules Part A
Filing the Schedules to Return of Income is not merely a formality for companies operating in Sri Lanka; it is a statutory obligation under the Income Tax Act No. 58 of 1961. All entities, including Resident and Non-Resident Companies, must adhere to strict submission deadlines, which typically coincide with the end of the financial year, i.e., March 31. However, understanding common pitfalls is vital for ensuring compliance.
One significant requirement is the accurate reporting of all income derived from various sources, including, but not limited to, business operations, investments, and other revenue streams. Companies must provide detailed breakdowns of these incomes, reflecting not just totals but also the nature of the income, which can have implications for tax treatment. Additionally, entities need to substantiate their deductions with appropriate documentation, as the DIR may request proof during an audit.
Furthermore, companies must declare any tax credits and incentives they have availed themselves of or are entitled to claim. This is particularly relevant for companies in sectors favored by government policies, such as renewable energy or information technology. Misreporting or failing to report can lead to significant penalties, including interest on unpaid taxes and potential criminal liability for tax evasion.
Common Challenges and Best Practices for Completing Schedules Part A
While the process of completing the Schedules to Return of Income - Part A can be straightforward, companies often face several challenges. These challenges can stem from complex financial transactions, discrepancies in financial reporting, and the evolving nature of tax regulations in Sri Lanka. Understanding these complexities is essential for accurate submission.
One common hurdle is reconciling financial statements prepared under different accounting standards. Multinational companies, for instance, might prepare financial statements in accordance with International Financial Reporting Standards (IFRS) while needing to report in accordance with local tax regulations. This inconsistency can lead to confusion and errors in reported income and allowable deductions.
To mitigate these challenges, companies should engage in regular training for their accounting and finance teams to stay updated on local tax legislation and changes in financial reporting standards. Additionally, implementing robust internal controls and utilizing integrated accounting systems can reduce the likelihood of errors, ensuring that all financial data is accurately captured for tax reporting purposes.
Moreover, early preparation of the schedules can significantly reduce last-minute rushes and allow time for thorough reviews before submission. Companies should establish a timeline for collecting necessary documentation and completing the schedules, which can further streamline the compliance process.