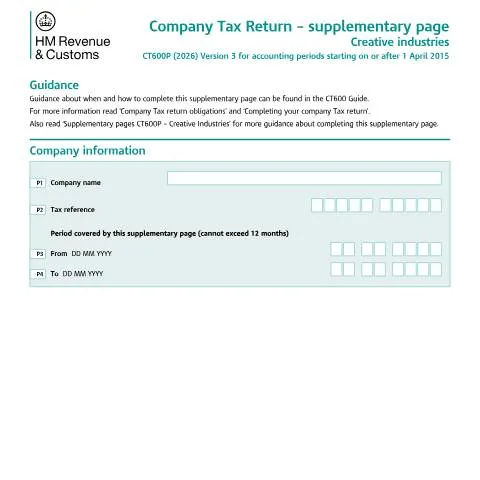
Understanding Creative Industries Corporation Tax Relief Through Form CT600P
When your company operates within the creative sectors—producing films, developing video games, or creating animated content—the UK tax landscape offers substantial financial incentives through specialised expenditure credits. The CT600P supplementary page serves as the gateway to claiming these creative industry reliefs, transforming qualifying production costs into tangible tax benefits that can significantly impact your company's cash flow.
This specialised supplement to the main CT600 Corporation Tax return handles two distinct relief schemes: the Audio-Visual Expenditure Credit (AVEC) covering film, television, and animation productions, and the Video Games Expenditure Credit (VGEC) for qualifying interactive entertainment projects. Unlike standard business expenses that merely reduce taxable profits, these credits can generate actual cash payments from HMRC, making them particularly valuable for production companies with fluctuating revenues.
Qualifying Creative Enterprises: Beyond Traditional Business Categories
The CT600P applies to companies engaged in specific creative activities that meet stringent technical and cultural criteria. Film production companies can claim relief on feature films, documentaries, and short films that pass the British Film Institute's cultural test or qualify under international co-production treaties. The minimum budget threshold varies: £500,000 for general films, though independent films benefit from more accessible criteria.
Television production splits into three distinct categories with different qualification requirements. High-end television programmes must have a minimum slot length of 30 minutes and production costs exceeding £1 million per broadcast hour. Children's television programmes face lower thresholds—£10,000 per slot minute—reflecting the sector's economics. Animation productions, whether for cinema or television, follow separate criteria focusing on the proportion of animation work completed in the UK.
Video games developers enter a different qualification framework entirely. The game must be intended for supply to the general public, certified as British by the British Film Institute, and have qualifying development expenditure exceeding £25,000. Importantly, the relief covers development costs rather than ongoing operational expenses, distinguishing it from traditional business deductions.
| Production Type | Minimum Threshold | Key Requirement | UK Spend Minimum |
|---|---|---|---|
| General Film | £500,000 total | Cultural test passage | 10% of total costs |
| Independent Film | No minimum | Cultural test passage | 10% of total costs |
| High-end TV | £1m per broadcast hour | 30+ minute slot length | 10% of total costs |
| Children's TV | £10,000 per slot minute | Target audience under 18 | 10% of total costs |
| Video Games | £25,000 development | BFI certification | 25% of total costs |
Navigating the Multi-Stage Calculation Framework
The CT600P employs a sophisticated six-step calculation process that determines how your creative industry credits interact with existing tax liabilities and generate potential cash payments. This framework ensures credits are applied in the most tax-efficient manner while preventing abuse through artificial arrangements.
Step 1 addresses immediate Corporation Tax liability offset. Your calculated AVEC or VGEC first reduces any Corporation Tax due for the current accounting period, after accounting for income tax already deducted from profits. This primary application often eliminates Corporation Tax liability entirely for production companies with significant qualifying expenditure.
The Pre-step 1 restriction mechanism handles brought-forward credits from previous periods or amounts surrendered from group companies. These historical credits take priority over current-period claims, ensuring systematic application across multiple accounting periods. Companies must carefully track these carried-forward amounts to maximise their utilisation.
Steps 2 and 3 introduce notional tax charges and restriction mechanisms. The system calculates a theoretical Corporation Tax charge on the expenditure credit itself, creating a restriction that carries forward to subsequent periods. This prevents companies from claiming credits indefinitely without generating corresponding economic activity. Step 3 allows offset against outstanding Corporation Tax liabilities from other accounting periods, providing flexibility for companies with irregular tax positions.
Group Company Interactions and Surrender Mechanisms
Step 4 enables credit surrender to other group companies, facilitating tax planning within corporate structures. The surrendering company cannot benefit from credits it cannot utilise, while recipient companies can apply surrendered credits against their own Corporation Tax liabilities. This mechanism requires careful documentation, with the CT600P capturing full details of surrender arrangements including recipient company names, tax references, and amounts transferred.
Companies must complete the detailed surrender schedule when utilising boxes P205 or P160, providing HMRC with complete visibility of intra-group credit movements. The legislation prevents credit trading outside genuine group relationships, maintaining the reliefs' intended scope.
Expenditure Classification and the UK Spend Requirement
Successfully completing the CT600P requires precise expenditure categorisation across five distinct columns. Column A captures relevant global expenditure—all production costs that could theoretically qualify for relief, regardless of where incurred. This includes above-the-line talent costs, production expenses, and post-production activities directly attributable to the qualifying project.
Column B narrows focus to UK expenditure within the global total. The legislation defines UK expenditure as costs paid to UK residents for services performed in the UK, or costs for goods consumed or services used in the UK. This includes payments to non-UK residents for UK-based work, but excludes overseas location costs even when paid through UK entities.
The qualifying expenditure in Column C represents the relief-eligible portion after applying cultural and technical tests. For most audio-visual projects, this equals UK expenditure provided the 10% UK spend threshold is met. Video games face a higher 25% threshold, reflecting policy intentions to ensure substantial domestic economic benefit.
Columns D and E calculate the actual credit claims. Standard rates apply 25% to qualifying expenditure, though enhanced rates benefit specific activities. Visual effects work on audio-visual productions attracts an additional credit, recognising the UK's competitive advantage in this technical specialisation.
Special Considerations for Visual Effects Enhancement
The visual effects additional credit represents a targeted incentive for high-value technical work. Qualifying visual effects expenditure receives enhanced treatment, with the additional credit calculated separately in Column E. Companies must distinguish between standard production costs and specific visual effects work, requiring detailed cost allocation systems.
This enhancement reflects the UK's strategic positioning in global visual effects markets, supporting domestic facilities competing against international alternatives. The additional credit applies only to audio-visual productions, with video games excluded from this enhanced treatment despite potentially involving similar technical processes.
Interaction with Broader Corporation Tax Obligations
The CT600P integrates seamlessly with the main CT600 Corporation Tax return, with specific figures transferring between forms. Box P245 on the supplementary page feeds directly into box 541 on the main return, ensuring consistent reporting across your complete tax submission. Similarly, payable credits from box P190 transfer to box 886, enabling HMRC's systems to process refund claims efficiently.
Companies must maintain detailed supporting records beyond the CT600P submission. HMRC expects comprehensive documentation proving expenditure qualification, including contracts, invoices, timesheets, and cultural test certificates. The legislation imposes specific record-keeping requirements, with penalties for inadequate documentation during compliance reviews.
Timing considerations significantly impact credit claims. The CT600P covers accounting periods up to 12 months, with expenditure attributed to periods when economic activity occurs rather than when payments are made. This accruals-based approach requires careful period-end cut-offs, particularly for productions spanning multiple accounting periods.
Managing Multi-Period Productions
Long-term productions present particular challenges for CT600P completion. Companies must allocate expenditure across relevant accounting periods, potentially submitting multiple supplementary pages for single projects. The legislation provides specific guidance on expenditure attribution, generally following accepted accounting principles while recognising creative industry peculiarities.
Productions beginning in one accounting period and completing in another require careful expenditure tracking. The cultural tests apply to completed productions, meaning provisional claims may require subsequent adjustment once final cultural certification is obtained.
Administrative Processing and HMRC Interaction
HMRC processes CT600P submissions alongside main Corporation Tax returns, with specialised creative industries teams handling complex technical queries. The department maintains dedicated guidance specifically for creative industry reliefs, regularly updated to reflect legislative changes and practical interpretation issues.
Processing times vary depending on claim complexity and supporting documentation quality. Straightforward claims with complete documentation typically process within standard Corporation Tax timescales, while complex multi-company arrangements or novel expenditure categories may require extended review periods.
Compliance activity in creative industries focuses on expenditure qualification and UK spend verification. HMRC's approach balances supporting genuine creative activity against preventing abuse through artificial arrangements. Companies should expect periodic reviews, particularly for large claims or unusual expenditure patterns.
The department's compliance strategy emphasises education over penalty, recognising that creative industry taxation involves complex technical requirements. However, deliberate non-compliance or persistent failure to maintain adequate records will attract standard penalty provisions.
Advance Clearance and Technical Guidance
Companies facing uncertainty about expenditure qualification can seek advance clearance from HMRC before incurring costs. This non-statutory process provides confidence for investment decisions while reducing subsequent compliance risks. HMRC generally responds positively to clearance requests demonstrating genuine commercial activity within the reliefs' policy objectives.
The clearance process requires detailed expenditure projections and cultural test assessments, enabling HMRC to provide specific guidance on borderline cases. While clearances are not legally binding, they establish HMRC's position and reduce audit risks for compliant taxpayers.
Strategic Integration Within Creative Industry Tax Planning
The CT600P operates within a broader creative industry tax landscape encompassing various reliefs and incentives. Companies may simultaneously claim multiple reliefs, requiring careful coordination to optimise overall tax positions while maintaining compliance with anti-avoidance provisions.
Research and Development tax credits may apply alongside creative industry reliefs where productions involve qualifying technical innovation. However, the legislation prevents double relief on identical expenditure, requiring precise allocation between different claim categories. Companies must maintain clear audit trails demonstrating appropriate expenditure attribution.
International considerations become relevant for co-productions or companies with overseas operations. The UK's creative industry reliefs operate alongside various international incentives, creating opportunities for enhanced returns through careful structuring. However, anti-avoidance provisions prevent artificial arrangements designed solely to maximise relief claims.
Corporate structure decisions significantly impact creative industry relief accessibility. The legislation's group company provisions enable flexible credit utilisation within genuine commercial arrangements, while preventing credit trading between unconnected entities. Companies should consider relief implications when establishing production structures or acquiring creative businesses.
The CT600P represents more than a mere tax form—it embodies the UK's strategic commitment to supporting creative industries through targeted fiscal incentives. Successful navigation requires understanding both technical compliance requirements and broader commercial implications, positioning creative industry reliefs as integral components of business strategy rather than administrative afterthoughts.
Specific Creative Industry Sectors and Their CT600P Implications
Different creative sectors face distinct challenges when completing the CT600P supplement, as each industry operates under unique business models and regulatory frameworks. Understanding these sector-specific nuances ensures accurate tax compliance and optimal utilisation of available reliefs.
Film and Television Production Companies
Film and television production companies encounter particularly complex CT600P requirements due to the project-based nature of their operations. These businesses typically work with substantial upfront investments, lengthy production cycles, and irregular revenue patterns that span multiple accounting periods.
Production companies must carefully track costs across different projects, distinguishing between qualifying expenditure for film tax relief and general business expenses. The CT600P requires detailed breakdowns of production costs, including above-the-line expenses (cast, director, producer fees), below-the-line costs (crew, equipment, post-production), and completion costs. Companies often maintain separate cost centres for each production to ensure accurate allocation.
Revenue recognition presents another complexity, particularly for companies involved in co-productions or international distribution deals. The CT600P must reflect the correct timing of income recognition, whether through minimum guarantee payments, distribution advances, or ongoing royalty streams. Companies working across multiple territories need to consider how foreign tax credits and withholding taxes impact their UK Corporation Tax liability.
Animation studios face additional considerations around intellectual property development and exploitation. The CT600P must capture both the costs of creating animated content and the ongoing licensing revenue from character merchandising, format licensing, and international sales. Studios developing original IP often benefit from R&D tax credits alongside creative industry reliefs, requiring careful coordination in the CT600P submission.
Publishing and Media Houses
Publishing companies, whether focused on books, magazines, or digital content, must navigate unique CT600P considerations around rights acquisition, royalty payments, and digital transformation costs. Traditional publishers increasingly operate hybrid models combining physical and digital distribution channels.
Rights and royalties management significantly impacts CT600P completion. Publishers must track advance payments to authors, ongoing royalty obligations, and rights reversion clauses. The supplement requires detailed reporting of intellectual property assets, including acquired manuscripts, translation rights, and digital adaptation rights. Publishers working with international authors need to consider withholding tax obligations and double taxation treaty benefits.
Digital transformation initiatives often qualify for various tax reliefs beyond traditional creative industry schemes. Publishers investing in content management systems, digital distribution platforms, or reader engagement technologies may claim R&D tax credits or capital allowances. The CT600P must clearly distinguish between qualifying digital infrastructure investments and general business software purchases.
Magazine and newspaper publishers face additional complexity around subscription revenue recognition and circulation-based advertising income. The CT600P requires careful treatment of deferred revenue from multi-year subscriptions and accurate reporting of circulation audit costs, which directly impact advertising rate cards and revenue streams.
Music Industry Enterprises
Record labels, music publishers, and artist management companies operate in an industry characterised by long-term investment cycles and complex rights structures. The CT600P must accurately reflect these unique business dynamics while capturing available tax reliefs.
Artist development costs represent a significant CT600P consideration for record labels. These companies invest heavily in talent scouting, recording advances, marketing campaigns, and tour support, often years before generating revenue. The supplement requires careful classification of these costs between immediate business expenses and capitalised artist development investments that may qualify for specific reliefs.
Music publishing companies face particular complexity around catalogue acquisition and rights management. The CT600P must reflect the acquisition cost of music catalogues, ongoing writer advances, and the complex web of performance, mechanical, and synchronisation rights. Publishers working with international repertoire need to consider foreign withholding taxes and collection society arrangements across multiple territories.
Streaming revenue allocation presents modern challenges for CT600P completion. Labels and publishers must track revenue from multiple digital service providers, each with different payment terms, currency considerations, and reporting lag times. The supplement requires accurate reflection of accrued streaming income and associated collection costs.
Integration with Other UK Tax Regimes and Compliance Frameworks
Creative industry companies completing the CT600P supplement must consider how their tax position integrates with broader UK tax regimes and compliance requirements. This holistic approach ensures optimal tax efficiency while maintaining full regulatory compliance across all applicable frameworks.
VAT Considerations for Creative Businesses
VAT treatment significantly impacts creative industry businesses, particularly those operating across multiple territories or offering both goods and services. The CT600P must reflect the VAT implications of various creative activities, as these directly affect the company's Corporation Tax position.
Digital services present particular VAT complexity for creative businesses. Companies providing streaming services, digital downloads, or online gaming must navigate the digital services VAT rules, which affect where VAT is charged and collected. The CT600P should reflect any VAT adjustments that impact the company's profit calculation, particularly where VAT recovery positions change due to exempt supplies or partial exemption calculations.
Cultural VAT exemptions create additional considerations for certain creative businesses. Museums, galleries, and cultural institutions may benefit from VAT exemptions on admission charges and related activities. However, commercial activities within these organisations remain subject to standard VAT rules, requiring careful separation in both VAT returns and CT600P submissions.
International creative collaborations often involve complex VAT considerations around place of supply rules. Co-productions, international touring, and cross-border licensing arrangements must be carefully analysed to determine correct VAT treatment. The CT600P should reflect any VAT adjustments arising from these international activities, particularly where reverse charge procedures apply.
Employment Tax Integration
Creative industry businesses typically employ a diverse workforce including permanent staff, freelancers, and project-based contractors. The CT600P must accurately reflect employment costs while considering the interaction with PAYE, National Insurance, and off-payroll working rules.
IR35 and off-payroll working rules significantly impact many creative businesses that rely heavily on freelance talent. The CT600P should reflect any additional employment tax liabilities arising from status determinations, particularly where companies are required to operate PAYE on payments to personal service companies. These additional costs directly impact the company's Corporation Tax calculation.
The Apprenticeship Levy affects larger creative businesses with annual pay bills exceeding £3 million. The CT600P should reflect both the levy cost and any apprenticeship training expenditure, which may qualify for additional tax reliefs. Creative businesses often benefit from apprenticeship programmes in technical roles such as sound engineering, digital effects, or production management.
Creative businesses operating internationally must consider employment tax implications for staff working abroad or international talent working in the UK. The CT600P should reflect any additional costs arising from work permit requirements, visa sponsorship, or social security coordination agreements. These costs often qualify as legitimate business expenses but require careful documentation.
Capital Gains and Asset Disposal Considerations
Creative businesses frequently deal with intellectual property assets that may be subject to capital gains treatment upon disposal. The CT600P must accurately reflect the interaction between Corporation Tax and capital gains, particularly for companies with substantial IP portfolios.
Substantial shareholdings exemption may apply when creative businesses dispose of trading subsidiaries or significant shareholdings. The CT600P should correctly identify qualifying disposals and ensure appropriate exemption claims are made. This is particularly relevant for media groups restructuring operations or creative businesses expanding through acquisition and subsequent disposal.
Rollover relief considerations apply when creative businesses replace business assets, particularly property or significant equipment purchases. The CT600P should reflect any rollover relief claims, ensuring that deferred gains are properly tracked for future accounting periods. This is especially relevant for businesses investing in new studio facilities or upgrading technical equipment.
Intellectual property disposals often involve complex valuation issues and may qualify for various reliefs depending on the nature of the assets and the disposal circumstances. The CT600P should accurately reflect the tax treatment of IP disposals, whether as trading receipts or capital items, and ensure appropriate documentation supports the chosen treatment.
Future Planning and Strategic Tax Considerations
Successful CT600P completion for creative businesses requires forward-looking strategic tax planning that anticipates industry changes, regulatory developments, and business evolution. Understanding these strategic considerations helps companies optimise their tax position while supporting business growth objectives.
Technology Integration and Digital Transformation
The creative industries are experiencing rapid digital transformation, creating both opportunities and challenges for tax planning. Companies must consider how technological investments impact their CT600P submissions and overall tax strategy.
Artificial intelligence and machine learning investments increasingly feature in creative business operations, from content recommendation algorithms to automated production processes. The CT600P should properly classify these investments, which may qualify for R&D tax credits, capital allowances, or creative industry reliefs depending on their specific application and development characteristics.
Blockchain and NFT activities present emerging tax considerations for creative businesses. Companies involved in creating, trading, or licensing NFTs must carefully consider the tax treatment of these activities. The CT600P should reflect whether NFT activities constitute trading income, capital transactions, or intellectual property licensing, with each classification carrying different tax implications.
Virtual and augmented reality content creation often involves substantial upfront investment in specialised equipment and software development. The CT600P should optimise the tax treatment of these investments through appropriate relief claims while ensuring compliance with evolving HMRC guidance on emerging technologies.
Data analytics and audience measurement technologies increasingly drive creative business decisions. Investment in these systems may qualify for various tax reliefs, and the CT600P should capture both the costs and benefits of data-driven creative strategies. Companies must also consider data protection compliance costs and their tax treatment.
International Expansion and Tax Planning
Creative businesses increasingly operate across multiple territories, requiring sophisticated tax planning that optimises global tax efficiency while maintaining UK compliance. The CT600P plays a crucial role in this international tax strategy.
Double taxation treaties significantly impact creative businesses with international operations. The CT600P should reflect treaty benefits claimed and ensure appropriate documentation supports these claims. Companies must consider how treaty networks affect their global tax rate and cash flow, particularly for businesses with significant international licensing revenue.
Controlled Foreign Company (CFC) rules may apply to creative businesses with overseas subsidiaries, particularly those established in low-tax territories for IP holding or distribution activities. The CT600P should properly account for any CFC charges while ensuring that legitimate international structures receive appropriate tax treatment.
Transfer pricing becomes increasingly important as creative businesses expand internationally. The CT600P should reflect arm's length pricing for intercompany transactions, particularly IP licensing arrangements and cost-sharing agreements. Companies must maintain robust transfer pricing documentation to support their CT600P positions.
Brexit implications continue to evolve for creative businesses with European operations. The CT600P should reflect any additional costs or structural changes arising from new trading arrangements, while companies explore opportunities presented by the UK's independent trade policy and potential new double taxation treaties.
Regulatory Environment and Policy Developments
The creative industries operate within a rapidly evolving regulatory environment that directly impacts tax planning and CT600P completion. Companies must stay informed about policy developments and their potential implications.
Digital services tax considerations affect larger creative businesses operating digital platforms or services. While this operates separately from Corporation Tax, companies must consider how DST impacts their overall tax strategy and cash flow planning. The CT600P should reflect any strategic responses to DST obligations.
Environmental taxation increasingly affects creative businesses, particularly those with significant physical operations or international touring activities. The CT600P should capture environmental tax costs while identifying opportunities for green investment reliefs and sustainability-focused tax incentives.
Content regulation changes, particularly around online safety and platform responsibility, may create additional compliance costs for digital creative businesses. The CT600P should properly classify these regulatory compliance costs while exploring whether any associated system investments qualify for tax reliefs.
Skills levy developments beyond the current Apprenticeship Levy may emerge as government seeks to address creative skills shortages. Companies should monitor policy developments and consider how future skills investments might be incentivised through the tax system, with implications for CT600P planning and completion.