Understanding Your Rights Under Consumer Credit Time Orders
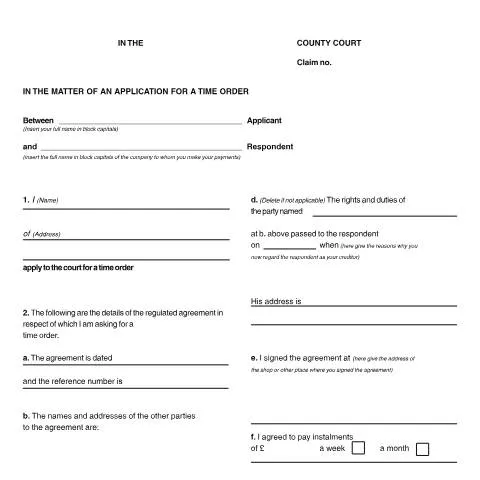
When creditors threaten enforcement action or repossession, many borrowers feel trapped with no viable options. However, the Consumer Credit Act 1974 provides a powerful protective mechanism through time orders, and the N440 application form serves as your gateway to this vital legal remedy. This notice document outlines how debtors and hirers can formally request the county court to intervene when payment difficulties arise under regulated agreements.
The N440 form represents more than just paperwork – it's a structured legal process that can halt aggressive creditor action whilst providing breathing space to reorganise your finances. Understanding the intricacies of this application process can mean the difference between losing your home, car, or other essential assets and securing sustainable repayment terms that work within your actual financial capacity.
Time orders under sections 129-130 of the Consumer Credit Act offer courts discretionary powers to reschedule payments, reduce instalments, or extend repayment periods. The N440 application triggers this judicial intervention, but success depends heavily on presenting your case effectively through this standardised notice format.
Decoding the Legal Framework Behind Time Order Applications
The N440 form operates within a complex regulatory structure designed to balance creditor rights with debtor protection. Regulated agreements under the Consumer Credit Act 1974 include most consumer credit arrangements up to £25,000, hire purchase contracts, and certain business loans where the borrower is an individual or partnership.
Section 129 grants courts authority to make time orders where it appears "just to do so" – a deliberately broad discretion that considers your individual circumstances rather than rigid criteria. The court examines whether your proposals for payment are reasonable given your financial position and whether creditor enforcement would cause undue hardship.
Crucially, time order applications can only proceed after specific creditor notices have been served. These trigger notices include default notices under section 87, termination notices under section 76(1), or demand for earlier payment notices under section 98(1). Without these prerequisite notices, courts lack jurisdiction to consider time order applications.
The timing element proves critical – you must apply for a time order before any court proceedings conclude. Once judgment is entered, the opportunity for time order relief typically passes, though courts retain limited discretion in exceptional circumstances.
Strategic Timing and Procedural Prerequisites
The N440 application process demands careful attention to procedural requirements and strategic timing. Applications must be submitted to the county court that has jurisdiction over your area, typically determined by where you reside or where the agreement was signed.
Before completing the N440 form, ensure you've received one of the qualifying creditor notices mentioned in section 2(i). These notices serve dual purposes – they provide formal warning of intended enforcement action and establish the legal foundation for time order applications. The specific type of notice affects which sections of your N440 application require completion.
| Notice Type | Legal Basis | Typical Scenarios |
|---|---|---|
| Default Notice (s.87) | Breach of payment terms | Missed instalments, arrears accumulation |
| Termination Notice (s.76) | Creditor ending agreement early | Material breach, repeated defaults |
| Demand Notice (s.98) | Acceleration of full balance | Serious breach triggering full repayment |
Service requirements demand strict compliance – your N440 application must be served on all relevant parties, including the creditor (respondent) and any guarantors or sureties. Failure to serve proper notice on all interested parties can invalidate your application entirely.
The court fee for time order applications varies depending on your financial circumstances, with fee remission available for those meeting specific income criteria. Consider applying for Help with Fees using form EX160 if your monthly income falls below prescribed thresholds.
Crafting Compelling Payment Proposals Within Your Financial Reality
Section 2(j) of the N440 form requires you to present realistic payment proposals that demonstrate both your commitment to clearing debts and your genuine financial constraints. Courts scrutinise these proposals carefully, comparing them against your declared income and essential expenditure detailed in the accompanying financial statement.
Successful payment proposals typically follow a two-stage structure: clearing existing arrears over a reasonable period, followed by revised regular instalments that maintain the agreement whilst accommodating your reduced capacity. Avoid proposing token payments that would take unrealistically long to clear the debt – courts prefer meaningful contributions that show good faith.
When calculating sustainable payment levels, factor in all essential expenses including housing costs, utilities, food, transport, insurance, and minimum payments on priority debts like council tax or child maintenance. Non-priority creditors should receive proportionate treatment based on debt size and your available disposable income.
Consider seasonal variations in income or expenditure when structuring proposals. Self-employed applicants might propose higher payments during peak trading periods with reduced instalments during quieter months, provided the overall annual contribution meets reasonable expectations.
Document your proposals thoroughly, explaining the rationale behind specific amounts and demonstrating how they align with your financial capacity. Courts appreciate transparency about your circumstances and realistic assessments of what you can sustain long-term.
Financial Disclosure Requirements and Supporting Evidence
The N440 application references a financial circumstances schedule that forms the evidential backbone of your time order request. This comprehensive disclosure enables courts to assess whether your payment proposals reflect genuine hardship or merely convenient preference for reduced payments.
Complete financial transparency proves essential for credible applications. Courts expect detailed breakdown of all income sources including employment, benefits, pensions, rental income, or family contributions. Similarly, expenditure disclosure should cover all reasonable living costs, existing debt commitments, and necessary expenses for maintaining employment or health.
Supporting evidence strengthens your application significantly. Bank statements, payslips, benefit award letters, and household bills provide objective verification of your declared financial position. Where circumstances have changed recently due to job loss, illness, or family breakdown, medical certificates or redundancy notices help explain the deterioration.
Avoid common pitfalls in financial disclosure:
- Understating income from all sources, including cash payments or irregular earnings
- Overstating expenses with unrealistic or luxury items that courts consider non-essential
- Failing to account for seasonal variations or anticipated changes in circumstances
- Mixing household expenses with personal commitments where multiple adults contribute
Consistency between your financial statement and payment proposals demonstrates credibility and realistic assessment of your position. Significant discrepancies raise questions about accuracy and may undermine your application's prospects.
Navigating Complex Agreement Structures and Multiple Creditors
Modern consumer credit arrangements often involve complex structures with multiple parties, assignment of rights, or consolidated debts that complicate N440 applications. Section 2(d) addresses situations where original creditor rights have transferred to different entities, requiring careful identification of current legal relationships.
Debt assignment scenarios frequently arise with hire purchase agreements, personal loans, or credit card debts where original lenders sell portfolios to specialist collection agencies. Accurate identification of the current creditor proves crucial for valid service of your application and establishing the court's jurisdiction over the correct legal entity.
Where multiple regulated agreements exist with the same creditor, consider whether separate N440 applications are required or whether consolidated applications might be appropriate. Courts can deal with related matters together where this promotes efficient case management and consistent outcomes.
Guarantor involvement adds another layer of complexity, as sureties must receive notice of time order applications that might affect their liability. Joint borrowers require careful consideration of whether both parties support the application or whether individual applications might be more appropriate.
Hire purchase agreements present particular challenges where the creditor retains title to goods until final payment. Time orders can prevent repossession whilst allowing continued use, but courts balance this against the creditor's proprietary rights and the asset's depreciation over extended payment periods.
Court Procedures and Judicial Considerations in Time Order Cases
Once submitted, your N440 application initiates formal court proceedings with specific procedural requirements and judicial discretion parameters. Courts typically list time order applications for initial consideration within 4-6 weeks, though complex cases or busy court schedules may extend these timescales.
Judicial discretion under section 129 encompasses broad powers to modify agreement terms, but courts apply established principles when exercising this discretion. The "just to do so" test considers multiple factors including your conduct as a debtor, the creditor's behaviour, the nature of the breach, and prospects for successful completion under revised terms.
Courts frequently grant interim time orders to maintain status quo whilst full applications are considered. These temporary arrangements prevent enforcement action but require you to maintain proposed payments pending final determination. Breach of interim orders severely prejudices your prospects for permanent relief.
Creditor opposition to time orders typically focuses on:
- Challenging the adequacy of proposed payment levels
- Questioning your financial disclosure accuracy
- Arguing that previous arrangements have failed
- Demonstrating that extended payment periods cause commercial prejudice
Effective response to creditor objections requires thorough preparation and realistic assessment of your position. Courts appreciate honest acknowledgement of past difficulties coupled with credible explanations for improved prospects under revised arrangements.
The court's final order may differ significantly from your original proposals, with judges having power to impose alternative payment structures, vary interest rates, or extend repayment periods beyond your suggestions. Accept that judicial discretion aims to balance competing interests fairly rather than simply granting your preferred outcome.
Long-term Implications and Compliance Obligations
Successful time order applications create binding legal obligations that extend beyond immediate payment relief. Courts retain ongoing jurisdiction to monitor compliance and can vary orders where circumstances change significantly, providing flexibility but requiring continued engagement with formal legal processes.
Credit file implications of time orders vary depending on how credit reference agencies interpret court involvement. While time orders prevent default registration during compliance periods, they may appear as satisfied court judgments once completed, potentially affecting future credit applications for up to six years.
Breach of time order terms carries serious consequences including potential imprisonment for contempt of court, though such extreme measures typically follow persistent non-compliance rather than temporary difficulties. Early communication with creditors and court services when problems arise demonstrates good faith and often enables sympathetic consideration of variation applications.
Consider the broader impact on your financial planning and credit relationships. Time orders provide breathing space but require disciplined budgeting and realistic lifestyle adjustments to ensure sustainable compliance. Professional debt advice services can provide ongoing support throughout extended repayment periods.
Monitor legislative and regulatory changes that might affect your ongoing obligations. Consumer credit law continues evolving, particularly regarding affordability assessments and responsible lending practices that may influence creditor behaviour and court attitudes in future variation applications.
Specific Circumstances Where Time Orders May Be Granted or Refused
Courts exercise considerable discretion when evaluating time order applications, with decisions heavily influenced by the specific circumstances surrounding your financial difficulties. Understanding these nuanced scenarios can significantly improve your prospects of success with Form N440.
Medical and Health-Related Financial Hardship
Serious illness or disability often provides compelling grounds for a time order, particularly where medical conditions directly impact earning capacity. Courts typically view favourably applications supported by medical evidence demonstrating how health issues have affected your ability to meet contractual obligations. This might include chronic conditions requiring ongoing treatment, mental health challenges affecting work performance, or sudden medical emergencies resulting in significant healthcare costs.
When presenting health-related grounds, provide comprehensive medical documentation from registered healthcare professionals. GP letters outlining treatment requirements, consultant reports detailing prognosis, or occupational health assessments demonstrating work limitations all strengthen your application. The court needs clear evidence linking your medical situation to payment difficulties rather than general financial mismanagement.
Employment and Income Disruption Scenarios
Redundancy, company closure, or significant reduction in working hours represent common circumstances where time orders prove successful. However, courts distinguish between temporary setbacks and fundamental changes to earning capacity. Short-term unemployment with realistic prospects of re-employment may warrant different consideration than permanent career changes or age-related employment challenges.
Self-employed applicants face particular scrutiny, as courts recognise the inherent unpredictability of business income. Seasonal traders, freelance professionals, or contractors experiencing client payment delays may find courts more sympathetic when applications demonstrate clear business recovery plans rather than vague hopes for improved circumstances.
Family and Relationship Breakdown Impact
Divorce proceedings, separation, or death of a partner frequently trigger financial instability warranting time order consideration. Courts acknowledge that relationship breakdown often involves legal costs, property division, and establishment of separate households, all placing strain on previously manageable budgets.
Single parents may receive particular consideration, especially where childcare responsibilities limit employment opportunities or require expensive care arrangements. However, courts expect realistic assessment of long-term financial capacity rather than temporary arrangements pending family court proceedings.
Strategic Preparation and Documentation Best Practices
Successful time order applications require meticulous preparation extending well beyond completing Form N440. Courts appreciate thorough documentation demonstrating genuine attempts to resolve payment difficulties before seeking judicial intervention.
Financial Evidence Requirements
Compile comprehensive financial records covering at least the preceding six months, including bank statements, payslips, benefit award letters, and details of all regular commitments. Courts examine spending patterns to identify whether financial difficulties stem from unavoidable circumstances or lifestyle choices incompatible with reduced income.
Priority debt obligations receive particular attention. Demonstrate how proposed payment arrangements address mortgage or rent arrears, council tax liabilities, and utility bills before considering unsecured creditor payments. Courts rarely approve time orders where essential living costs remain unaddressed while seeking to restructure commercial debt.
Prepare detailed monthly budget calculations showing realistic income and expenditure projections. Include seasonal variations, annual expenses like insurance premiums or MOT costs, and reasonable allowances for emergency repairs or replacement of essential items. Overly optimistic budgets lacking contingency planning often result in application refusal.
Creditor Communication Documentation
Maintain detailed records of all creditor communications, including dates of contact, names of representatives spoken to, and outcomes of discussions. Courts expect evidence of genuine attempts to negotiate alternative payment arrangements before resorting to formal legal proceedings.
Where creditors have refused reasonable offers or insisted on unrealistic payment schedules, document these interactions thoroughly. Letters rejecting affordable payment proposals or threatening immediate enforcement action strengthen your position that judicial intervention represents the only viable solution.
Professional Advice and Support Evidence
Obtaining advice from recognised debt counselling services demonstrates responsible approach to financial difficulties. Citizens Advice, StepChange, or local authority debt advice services can provide written summaries of your situation and recommended courses of action that courts often find persuasive.
Where professional advisers have attempted creditor negotiations on your behalf, include copies of correspondence and summaries of outcomes. This evidence shows systematic attempts to resolve matters without court intervention while highlighting creditor intransigence where applicable.
Post-Application Procedures and Ongoing Compliance Obligations
Successfully obtaining a time order through Form N440 creates ongoing legal obligations requiring careful management to avoid subsequent enforcement action or order variation applications from creditors.
Payment Schedule Adherence and Monitoring
Time orders establish legally binding payment schedules that must be maintained without default. Even minor variations or delayed payments can prompt creditor applications for order discharge or enforcement proceedings resumption. Establish robust payment systems ensuring consistent compliance with court-imposed terms.
Direct debit arrangements often provide the most reliable payment method, removing risk of forgotten payments or timing errors. However, ensure sufficient account funds exist before each collection date, as returned payments may constitute breach of court order regardless of ultimate payment within the same month.
Maintain detailed payment records including transaction references, dates, and amounts. Should disputes arise regarding payment compliance, comprehensive documentation proves invaluable in defending your position before the court.
Circumstantial Change Reporting Requirements
Significant improvements in financial circumstances may require voluntary disclosure to creditors or the court, particularly where payment capacity substantially exceeds the time order schedule. While courts rarely require overpayment beyond agreed terms, dramatic income increases might prompt creditor applications for order variation.
Conversely, further deterioration in financial position may necessitate additional applications for payment reduction or extended time periods. Courts generally view proactive communication more favourably than reactive responses to creditor enforcement attempts following payment defaults.
Long-term Financial Planning Considerations
Time orders provide temporary respite rather than permanent debt solutions. Use the protected period to address underlying financial management issues, whether through budgeting improvements, additional income generation, or professional debt restructuring advice.
Consider whether debt consolidation, individual voluntary arrangements, or other formal insolvency procedures might provide more comprehensive solutions than extended payment periods. While time orders offer immediate protection, they may not represent optimal long-term strategies for complex debt situations.
Regular review of payment capacity ensures time order terms remain realistic and sustainable. Circumstances changing during extended payment periods may warrant discussions with creditors regarding early settlement discounts or final payment arrangements that benefit both parties while concluding the agreement ahead of schedule.