Securing Property Rights Through Legal Charge Registration
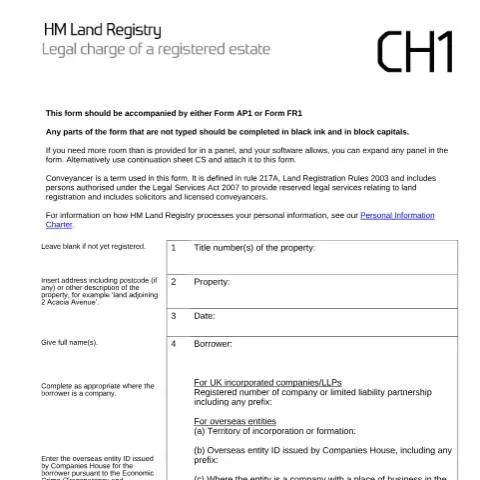
When a mortgage arrangement transforms from a mere contractual agreement into a registered legal interest, Form CH1 serves as the critical gateway. This HM Land Registry form establishes the formal registration of a legal charge, creating enforceable security rights that protect lenders whilst ensuring transparency in property ownership records. Unlike simple loan documentation, a registered legal charge provides statutory protection and priority over subsequent interests, making CH1 completion a pivotal moment in property finance.
The form operates within England and Wales' registered land system, where legal interests must be formally recorded to achieve full protection. For borrowers, this represents the moment their property becomes legally encumbered. For lenders, registration transforms a personal right into a proprietary interest, significantly strengthening their position should default occur.
Understanding When CH1 Registration Becomes Necessary
Legal charge registration through CH1 becomes mandatory when creating a mortgage over registered land, but the timing and circumstances vary considerably. New mortgages require immediate registration following completion, typically within the priority period established by the initial application. However, the form also accommodates several distinct scenarios that borrowers and lenders frequently encounter.
Transfer of existing charges presents a common situation where CH1 proves essential. When lenders assign mortgages to other institutions, the new lender must register their interest using CH1 to maintain priority and enforceability. This differs markedly from simple notification procedures used in unregistered land systems.
Corporate restructuring often triggers CH1 requirements, particularly when companies merge or undergo substantial reorganisation. The form accommodates complex ownership structures, including overseas entities subject to the Economic Crime (Transparency and Enforcement) Act 2022. These entities must provide their Companies House overseas entity ID, reflecting enhanced transparency requirements introduced to combat financial crime.
Further advance obligations represent another crucial application area. Panel 8 specifically addresses situations where lenders commit to providing additional funding secured against the same property. This might include revolving credit facilities, construction loans with staged drawdowns, or equity release arrangements with flexible withdrawal options.
Navigating the Accompanying Forms Requirement
CH1 never operates in isolation – it must accompany either Form AP1 or Form FR1, creating an integrated application package. This pairing reflects the dual nature of mortgage registration, which simultaneously affects both the property title and the charges register.
| Accompanying Form | Primary Purpose | When Required |
|---|---|---|
| AP1 | Transfer of registered estate | Property changing hands with new mortgage |
| FR1 | First registration application | Previously unregistered land entering the system |
The AP1 combination typically occurs during property purchases where buyers simultaneously register their ownership and create mortgage security. Conversely, FR1 partnerships emerge when unregistered properties enter the system for the first time, often triggered by sales, long leases, or certain mortgage arrangements on previously unregistered land.
This requirement prevents fragmented applications and ensures HM Land Registry processes related changes holistically. Attempting to submit CH1 independently would result in rejection, emphasising the interconnected nature of land registration procedures.
Completing Critical Identification and Property Details
Panels 1 and 2 establish the foundational identification framework, requiring precision that reflects the form's legal significance. Title numbers in panel 1 should remain blank for unregistered properties but must be completed accurately for registered land. Multiple title numbers may apply where charges affect several properties simultaneously, common in commercial lending or portfolio mortgages.
Property descriptions in panel 2 demand careful attention to established conventions. For registered land, the description should mirror the register entry exactly, including any specific identifiers or limitations. Unregistered properties require sufficient detail to enable precise identification, often necessitating reference to adjoining properties or distinctive features.
Postcode inclusion, whilst seemingly administrative, carries legal significance. HM Land Registry increasingly relies on postal addressing for property identification, and omitting postcodes can delay processing or create ambiguity in densely developed areas where similar property descriptions might apply to multiple locations.
Date Precision and Legal Consequences
Panel 3's date entry appears straightforward but carries substantial legal implications. This date typically represents the charge creation date, establishing priority against other interests and determining when the security becomes effective. For mortgage arrangements, this usually aligns with completion dates, but refinancing or corporate transactions may require different dating approaches.
Backdating remains permissible in specific circumstances, particularly where applications fall within priority periods established by earlier searches or applications. However, incorrect dating can affect priority disputes and create complications if intervening interests have arisen.
Managing Complex Borrower and Lender Classifications
Panels 4 and 5 accommodate increasingly sophisticated lending arrangements, reflecting modern property finance complexity. Individual borrowers require straightforward name completion, but corporate structures demand careful navigation of registration requirements and identification protocols.
UK incorporated companies must provide their Companies House registration numbers, including appropriate prefixes that identify company types. Limited liability partnerships follow similar protocols but use distinct numbering systems that reflect their hybrid legal status.
Overseas entities face enhanced requirements following recent legislative changes. The Economic Crime (Transparency and Enforcement) Act 2022 mandates overseas entity IDs for certain foreign companies acquiring UK property interests. Panel 4 specifically accommodates these requirements, distinguishing between entities requiring registration and those exempt under current thresholds.
Territory of Incorporation Considerations
For overseas companies, territory identification extends beyond simple country naming. Some jurisdictions maintain multiple corporate registration systems, and HM Land Registry requires sufficient detail to enable verification through appropriate channels. Crown Dependencies and British Overseas Territories receive specific treatment reflecting their unique constitutional positions.
Companies with UK business presences face dual reporting requirements, providing both home jurisdiction details and UK registration numbers where applicable. This reflects anti-money laundering requirements and enables cross-referencing between different regulatory databases.
Structuring Service Addresses and Communication Protocols
Panel 6 establishes crucial communication frameworks that extend far beyond simple correspondence arrangements. Lenders may designate up to three service addresses, creating flexibility whilst maintaining legal certainty about where formal notices should be directed.
The requirement for at least one postal address, whether UK-based or international, reflects legal service requirements that remain anchored in physical delivery systems. However, the inclusion of DX box numbers and email addresses acknowledges modern communication preferences whilst maintaining audit trails essential for legal proceedings.
Strategic address selection often reflects operational considerations. Large lenders frequently designate specialist departments for different notice types, using varied addresses to ensure appropriate internal routing. Professional service companies may provide registered office addresses whilst maintaining operational addresses for day-to-day correspondence.
International Service Considerations
Overseas lenders face particular challenges in service address designation. Whilst international postal addresses remain acceptable, practical enforcement considerations often favour UK-based service addresses. Many foreign lenders establish UK representative offices or engage professional agents specifically to provide domestic service addresses that facilitate efficient legal proceedings if required.
Crafting Mortgage Terms and Additional Provisions
Panel 7 presents the mortgage's fundamental structure, requiring careful selection between full and limited title guarantee options. Full title guarantee provides comprehensive protection, with borrowers warranting their complete ownership rights and freedom to create the charge. Limited title guarantee offers more restricted protection, typically used where borrowers cannot provide complete ownership warranties.
This distinction carries significant implications for lender protection and potential remedies. Full title guarantee enables lenders to pursue broader claims if title defects emerge, whilst limited guarantee restricts recovery to specifically warranted matters.
Panel 9's additional provisions accommodate the mortgage's specific terms, including repayment schedules, interest calculations, and default provisions. This section often references separate mortgage deeds or facility agreements, creating integrated documentation packages that address both registration requirements and detailed commercial terms.
Further Advances and Restriction Applications
Panel 8 addresses two sophisticated concepts that significantly impact the charge's scope and operation. Further advance obligations enable lenders to register commitments for additional lending secured against the same property. This proves particularly valuable for construction finance, equity release products, or revolving credit facilities where future advances require automatic security.
Restriction applications through panel 8 provide additional protection mechanisms, typically preventing unauthorised disposals or requiring specific consents before property transactions proceed. Standard restriction forms, detailed in Schedule 4 to the Land Registration Rules 2003, address common protection scenarios, though bespoke restrictions may be crafted for unusual circumstances.
| Restriction Type | Protection Provided | Common Applications |
|---|---|---|
| Form A | Consent requirement | Lender approval for disposals |
| Form B | Certificate requirement | Professional confirmation of compliance |
| Form C | Court order requirement | Disputed ownership situations |
Execution Requirements and Legal Formalities
Panel 10 transforms the application from administrative paperwork into a binding legal instrument through proper deed execution. The Land Registration Rules 2003 prescribe specific execution formats that vary according to signatory types and circumstances, making careful compliance essential for registration success.
Individual borrowers must execute the charge as a deed, typically requiring signature in the presence of an independent witness who must also sign and provide their name and address. The witness cannot be the borrower's spouse, civil partner, or someone with beneficial interests in the transaction.
Corporate execution follows more complex protocols reflecting different legal personality concepts. Companies may execute through directors' signatures, common seals, or authorised signatories, depending on their constitutional documents and internal approval processes.
Multiple Party Coordination
Where multiple borrowers exist, all must execute the deed, creating coordination challenges that require careful management. Different execution dates remain acceptable provided all signatures occur before application submission, but significant timing gaps may raise questions about transaction validity or party commitment.
Lender execution becomes mandatory when further advance obligations are registered through panel 8. This dual signature requirement reflects the mutual commitment nature of such arrangements, where both parties undertake binding obligations that merit formal execution.
Processing Timelines and Registration Outcomes
Following submission, HM Land Registry processes CH1 applications through established workflows that typically complete within standard service targets, though complex cases may require extended examination periods. The integrated nature with AP1 or FR1 applications means processing times reflect the most complex element of the combined application.
Successful registration results in charge entries appearing on the charges register, creating public records that protect lender interests and inform potential purchasers or subsequent lenders. The registration provides statutory protection under the Land Registration Act 2002, significantly strengthening the lender's position compared to unregistered interests.
Priority protection extends from the application date, provided registration completes successfully. This priority period proves crucial in competitive lending markets where multiple lenders might seek security over the same property, establishing clear hierarchies that determine recovery prospects in default scenarios.
Registration also triggers various notification requirements and creates ongoing obligations for both parties. Lenders must maintain accurate service address details, whilst borrowers face restrictions on property dealings that could prejudice the charge's security value.
Enforcement and Recovery Rights for Registered Legal Charges
Registration of a legal charge under Form CH1 grants the chargeholder specific enforcement powers that become crucial when borrowers default on their obligations. Understanding these rights helps both lenders assess their security position and borrowers appreciate the consequences of non-compliance with charge terms.
The primary enforcement mechanism is the power of sale, typically activated when mortgage payments fall into arrears beyond the grace period specified in the charge document. Most commercial charges include express powers of sale, but even without explicit provision, the Law of Property Act 1925 implies certain statutory powers once specific conditions are met. These conditions generally include serving appropriate notices and allowing reasonable time for remedy.
Before exercising sale powers, chargeholders must typically serve a demand notice requiring payment of the outstanding sum within a specified period, usually not less than three months for property charges. The exact notice requirements vary depending on whether the charge covers residential or commercial property, with additional consumer protections applying to residential mortgages under the Financial Conduct Authority's regulations.
Appointment of receivers represents another significant enforcement option available to registered chargeholders. This power allows the appointment of a qualified insolvency practitioner to take control of the charged assets and apply any income generated towards discharge of the debt. Receiver appointments are particularly common in commercial property situations where rental income can service the debt while preserving the asset's value.
The enforcement process differs markedly between fixed and floating charges. Fixed charges over specific assets like land or machinery provide immediate security over identifiable property, allowing direct enforcement action against those assets. Floating charges, conversely, hover over a class of assets that may change in the ordinary course of business, only crystallising into fixed security upon default or other trigger events specified in the charge document.
Priority disputes often arise during enforcement, particularly where multiple charges exist over the same assets. The registration date on Form CH1 generally determines priority between competing charges, subject to certain exceptions for purchase money security interests or charges with express subordination agreements. Professional advisers frequently recommend conducting thorough priority searches before advancing funds under any charge arrangement.
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
Cross-default provisions in charge documents can accelerate enforcement timelines significantly. These clauses treat default under related agreements or other charges as triggering events, potentially allowing immediate enforcement even where the specific charged debt remains current. Such provisions require careful drafting to ensure enforceability while avoiding unfair contract terms challenges.
Modification, Assignment and Discharge Procedures
Registered legal charges frequently require modification during their lifetime to reflect changing business circumstances, refinancing arrangements, or variations in the underlying debt structure. The Companies House filing system accommodates these changes through specific procedures that maintain the integrity of the public record while allowing commercial flexibility.
Deed of variation represents the most common method for modifying charge terms, whether increasing the secured amount, extending the security to additional assets, or altering repayment schedules. Significant variations typically require registration of a new Form CH1 rather than simple amendment, particularly where the variation creates additional security interests or substantially increases the amount secured.
The distinction between variations requiring new registration and those constituting simple amendments can prove complex. Generally, variations that increase the amount secured beyond the original sum, extend security to previously uncharged assets, or fundamentally alter the charge's nature require fresh registration. Minor administrative changes, such as updating contact details or correcting clerical errors, may not trigger new registration requirements but should still be documented properly.
Assignment of charges occurs frequently in commercial lending, particularly where original lenders sell loan portfolios to other financial institutions or where syndicated lending arrangements involve multiple participants. The assignment process requires careful attention to both the underlying debt transfer and the security assignment, as these may involve separate legal steps and documentation.
Notice requirements for charge assignments vary depending on the charge terms and applicable law. Most charge documents specify notification procedures that must be followed to perfect the assignment against the borrower and preserve the assignee's priority position. Failure to provide proper notice can result in continued payments to the original chargeholder being treated as valid discharge of the debt.
Partial discharge procedures allow release of specific assets from the charge's scope while maintaining security over remaining charged property. This flexibility proves particularly valuable in development finance situations where individual properties or phases may be released from security as they are completed and sold, provided replacement security or debt reduction occurs according to agreed formulas.
The documentation for partial discharges must clearly identify the assets being released and confirm that the remaining security adequately covers the outstanding debt. Professional valuations often accompany partial discharge applications to demonstrate that the security margin remains acceptable to the chargeholder after the proposed release.
Full discharge occurs upon complete satisfaction of the secured obligations, requiring filing of Form MR04 with Companies House to remove the charge from the public register. The discharge process involves the chargeholder providing a statutory declaration confirming that all secured obligations have been satisfied and that they consent to the charge's cancellation.
Timing considerations for discharge filings can affect the company's credit profile and future borrowing capacity. Prompt discharge of satisfied charges demonstrates good financial management and ensures that the company's borrowing capacity is not artificially constrained by defunct security interests appearing on the public record.
Cross-Border and Complex Structure Considerations
Modern commercial arrangements frequently involve international elements that complicate legal charge registration and enforcement, requiring careful consideration of conflict of laws principles and cross-border recognition issues. The UK's approach to international charges reflects both common law traditions and practical commercial needs in an interconnected global economy.
Governing law clauses in charge documents determine which jurisdiction's laws apply to the interpretation and enforcement of the security interest, but this choice may not extend to all aspects of the charge relationship. Registration requirements, priority rules, and enforcement procedures often remain subject to the law of the jurisdiction where the charged assets are located, regardless of the governing law selection.
Assets located outside the UK may require parallel security registration in their respective jurisdictions to ensure enforceability, even where the charge document is governed by English law. This dual registration approach helps protect the chargeholder's interests but requires coordination between legal advisers in multiple jurisdictions and careful attention to timing requirements in each location.
The Brussels Recast Regulation and other international instruments provide frameworks for cross-border recognition of judgments and enforcement actions, but these mechanisms do not automatically extend to all aspects of security enforcement. Chargeholders with international assets must often pursue parallel enforcement proceedings in multiple jurisdictions, with associated costs and timing complications.
Special considerations apply to charges over intellectual property rights that may be registered or protected in multiple countries. Patent and trademark portfolios often require security registration in each jurisdiction where protection exists, as local registration systems may not recognise charges registered elsewhere. This fragmentation can create gaps in security coverage that require careful structuring to address.
Subsidiary guarantee structures frequently accompany international charges, where UK parent companies provide security for obligations of overseas subsidiaries or vice versa. These arrangements must navigate both corporate law restrictions on financial assistance and security law requirements in multiple jurisdictions, often requiring complex documentation to ensure enforceability.
The impact of exchange controls in various jurisdictions can affect both the creation and enforcement of international charges. Some countries restrict the ability of local companies to grant security to foreign lenders or limit the repatriation of enforcement proceeds, requiring careful structuring to ensure that security arrangements remain commercially viable.
Currency considerations add another layer of complexity to international charge arrangements. Charges may secure obligations denominated in different currencies, raising questions about conversion rates for enforcement purposes and the treatment of foreign exchange fluctuations in calculating security coverage ratios.
Insolvency law variations across jurisdictions can significantly impact charge enforcement in cross-border situations. What constitutes preferential treatment, the ranking of different creditor classes, and the availability of various enforcement remedies may differ substantially between countries, affecting the practical value of security interests in international structures.
Professional coordination becomes essential in complex international arrangements, with legal advisers in each relevant jurisdiction working together to ensure consistent and effective security structures. This collaboration extends beyond initial documentation to ongoing compliance monitoring and enforcement coordination when difficulties arise.