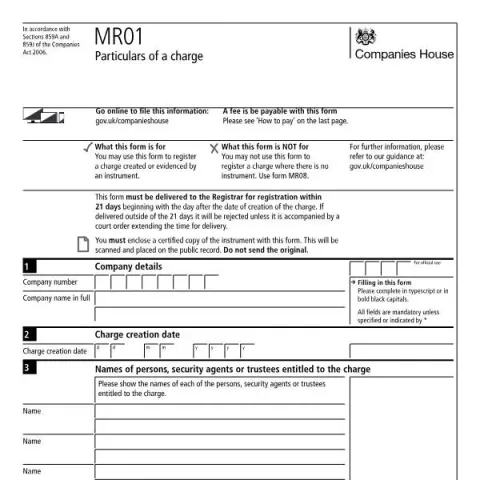
When Commercial Lending Meets Legal Certainty: Understanding the MR01 Charge Registration Process
Every business day across the UK, thousands of companies secure financing through various forms of secured lending arrangements. Whether it's a manufacturing firm mortgaging its factory premises, a logistics company using its vehicle fleet as collateral, or a technology startup granting security over its intellectual property portfolio, these transactions create what company law terms a "charge". The MR01 form represents the crucial bridge between private commercial agreements and public legal certainty, ensuring that security interests are properly recorded on the public register maintained by Companies House.
The significance of this registration process extends far beyond mere administrative compliance. When a charge remains unregistered, it becomes void against liquidators, administrators, and other creditors – potentially rendering sophisticated security arrangements worthless precisely when they're most needed. This stark legal consequence transforms the MR01 from a routine filing into a mission-critical document that can determine whether secured creditors recover their investments or join the ranks of unsecured creditors fighting over residual assets.
The Twenty-One Day Imperative and Its Commercial Reality
The Companies Act 2006 establishes an unforgiving timeline: charges must be registered within 21 days beginning with the day after creation. This seemingly straightforward requirement conceals layers of complexity that regularly trap unwary practitioners. The clock starts ticking from the charge creation date, not from when documentation is finalised, agreements are signed by all parties, or funds are advanced.
Consider a typical acquisition financing scenario where a charge is created on Monday but the broader transaction doesn't complete until the following Friday. The 21-day period begins running from Tuesday, regardless of whether the underlying commercial arrangements remain conditional. This timing pressure intensifies when dealing with complex syndicated facilities involving multiple lenders, where coordination challenges can consume precious days while the statutory deadline approaches relentlessly.
| Charge Creation Context | Registration Deadline Trigger | Common Pitfalls |
|---|---|---|
| Standard bank facility | Day after facility agreement execution | Assuming completion date controls timing |
| Debenture over multiple assets | Day after debenture creation | Delayed asset transfer completion |
| Security trustee arrangements | Day after trust deed execution | Waiting for all beneficiary confirmations |
| Cross-border transactions | Day after UK company grants security | Foreign law documentation delays |
The form explicitly warns that late filings face rejection unless accompanied by a court order extending the delivery time. Obtaining such relief requires demonstrating to the court that the failure to register within time was inadvertent and that granting an extension wouldn't prejudice existing creditors. This process involves additional legal costs, court fees, and the uncomfortable reality that relief isn't guaranteed.
Navigating the Instrument Certification Labyrinth
The MR01's requirement for a "certified copy of the instrument" represents one of the most technically demanding aspects of charge registration. Companies House requires certification that confirms the copy accurately represents the original document, but the acceptable methods of certification follow specific protocols that vary depending on who provides the certification.
Solicitors can certify copies using their professional status, typically adding a statement such as "I certify this to be a true copy of the original document" followed by their signature, printed name, and firm details. However, complications arise when dealing with complex security packages involving multiple instruments, supplemental deeds, or documents executed across different jurisdictions with varying authentication requirements.
For in-house legal teams or companies without immediate solicitor access, alternative certification routes exist. Company secretaries can provide certification, as can notaries public, though the latter option involves additional costs and potential delays. The key requirement remains ensuring that whoever certifies the copy has actually seen the original document and can attest to the accuracy of the reproduction.
International transactions present particular challenges when the underlying instrument is governed by foreign law or executed overseas. Documents may require apostille certification or consular legalisation before UK certification becomes possible, potentially consuming days or weeks of the precious 21-day window.
Decoding Floating Charges and the All-Assets Question
Section 6 of the MR01 addresses floating charges with a deceptively simple question: "Is the floating charge expressed to cover all the property and undertaking of the company?" This inquiry carries profound implications for both the charging company and its creditors, as all-assets floating charges create comprehensive security interests that can significantly impact the company's future financing flexibility.
Floating charges represent a uniquely English legal concept allowing security over a company's changing pool of assets – typically stock, debtors, and cash – while permitting the company to deal with these assets in the ordinary course of business until crystallisation occurs. When a floating charge covers "all property and undertaking", it potentially encompasses every asset the company owns or acquires, creating what practitioners term an "all monies, all assets" security interest.
The distinction matters because subsequent lenders examining the charge register need to understand the scope of existing security interests. A floating charge limited to specific asset categories leaves room for future secured lending over unencumbered assets, while an all-assets charge may require subordination agreements or complex intercreditor arrangements to accommodate additional financing.
Modern debentures often employ sophisticated drafting techniques that create multiple floating charges over different asset categories rather than a single all-encompassing charge. This approach provides greater flexibility for structuring subsequent financing arrangements while maintaining comprehensive security coverage for the original lender.
The Art of Asset Description and Intellectual Property Complexities
Section 4 requires a brief description of charged assets, with specific attention to "land, ship, aircraft or intellectual property registered or required to be registered in the UK". This requirement reflects the intersection between Companies House registration and other specialist registers maintained by different authorities.
Property descriptions must balance specificity with brevity, given the limited space available on the form. For land charges, practitioners typically provide the property address and title number, enabling searchers to cross-reference the Land Registry for detailed information. The challenge intensifies when dealing with portfolios containing numerous properties, where the form guidance suggests describing representative examples and adding "for more details please refer to the instrument".
Intellectual property presents particular complexity because UK registration requirements vary significantly between different IP categories. Registered trademarks and patents clearly fall within the scope requiring description, but unregistered rights such as copyright, design rights, or trade secrets occupy a greyer area. Domain names, increasingly valuable commercial assets, pose classification challenges as they exist within private registry systems rather than government-maintained registers.
Aircraft and ship registrations involve specialist requirements under aviation and maritime law respectively. The Civil Aviation Authority maintains the UK aircraft register, while ship registration involves either the UK Ship Register or various category-specific registers. Charges over these assets must navigate both Companies House requirements and the specialist registration obligations governing the underlying assets.
Negative Pledge Provisions and Their Strategic Implications
Section 7's inquiry about negative pledge clauses addresses one of commercial lending's most significant control mechanisms. These provisions restrict the borrower's ability to create future security interests that might rank equally with or ahead of the existing charge, providing lenders with contractual protection against dilution of their security position.
The presence of negative pledge restrictions appears on the public register, alerting potential future lenders to contractual constraints on the company's ability to grant security. This transparency serves multiple constituencies: existing lenders gain public notice of their contractual protections, while prospective lenders can identify potential impediments to new security arrangements.
Sophisticated negative pledge clauses often include carve-outs permitting specific types of future security interests. Common exceptions include purchase money security interests, refinancing arrangements up to specified amounts, or security granted to support particular business activities such as trade finance or equipment leasing. However, the MR01's binary yes/no format cannot capture these nuances, requiring searchers to examine the underlying instrument for detailed restrictions.
The strategic implications extend beyond immediate financing arrangements. Companies subject to broad negative pledge restrictions may find their ability to pursue growth opportunities constrained when potential acquisitions or expansion projects require secured financing that conflicts with existing restrictions.
Authentication Requirements and Public Record Implications
The authentication section demands careful attention because the person authenticating the form must have "an interest in the charge". This requirement excludes casual third parties while encompassing a broader range of eligible authenticators than might initially appear obvious.
Clearly eligible parties include the charge holder, borrowing company directors, and legal representatives acting for either party. However, the "interest" requirement extends to security trustees, agents appointed under syndicated facilities, and potentially other parties with recognised stakes in the security arrangement. Company secretaries typically qualify through their role in corporate administration, while external advisors must demonstrate a legitimate connection to the charge creation or registration process.
The authentication carries particular significance because the authenticator's name appears on the public register permanently. This visibility creates accountability but also means that individuals authenticating charges become associated with those transactions in public records that remain accessible indefinitely. For professional advisors, this creates a permanent professional footprint linking them to specific client transactions.
Companies House processes create additional considerations around timing and responsibility. Once submitted, corrections require separate procedures that may involve additional fees and documentation. The permanent nature of the public record means that errors in authentication or other form details cannot simply be withdrawn or amended without formal procedures.
Beyond Registration: Ongoing Obligations and Strategic Considerations
Successful MR01 registration marks the beginning rather than the end of ongoing charge administration obligations. The public register becomes a dynamic record requiring maintenance as circumstances change throughout the charge's lifecycle.
Satisfaction of charges requires separate filings when security interests are released or discharged. Companies House provides specific forms for different satisfaction scenarios, from complete discharge to partial releases affecting portions of the secured debt or charged assets. Failing to register satisfaction events leaves misleading information on the public register, potentially complicating future financing arrangements or corporate transactions.
Variations to charge terms may require additional registrations depending on their nature and scope. Increases in secured amounts, extensions of security over additional assets, or changes to fundamental charge terms can trigger fresh registration obligations. The challenge lies in distinguishing between administrative variations that require no further registration and substantive modifications that create new charge registration obligations.
Corporate restructuring events create particular complexity around existing charges. Schemes of arrangement, mergers, and corporate migrations can affect charge registration requirements in ways that require careful analysis of both the underlying commercial arrangements and applicable legal frameworks governing continuity of security interests.
The £24 paper filing fee represents only the most visible cost element in charge registration. Professional fees for legal advice, document preparation, and certification typically exceed the statutory fee significantly, while the potential consequences of registration failures can involve substantial financial exposure. This cost structure encourages careful preparation and professional involvement rather than treating charge registration as a routine administrative task.
Understanding Charge Registration Deadlines and Consequences
The timing of charge registration carries significant legal implications that many companies underestimate. The 21-day deadline from the date of creation applies strictly, with the clock starting from when the charge document is executed, not when the underlying transaction completes. This distinction proves crucial in complex commercial arrangements where documentation and funding occur on different dates.
Late registration remains possible through a court application, but this route involves substantially higher costs and uncertain outcomes. The court must be satisfied that the failure to register was inadvertent and that no creditor would be prejudiced by allowing late registration. Preparing such applications requires detailed evidence explaining the delay and demonstrating the company's good faith efforts to comply.
The consequences of non-registration extend beyond simple administrative oversight. An unregistered charge becomes void against liquidators, administrators and creditors, though it remains valid between the original parties. This creates a particularly dangerous scenario where the charge holder believes their security is protected, only to discover their vulnerability during insolvency proceedings.
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
For floating charges, the timing becomes even more critical. The charge may crystallise automatically upon certain trigger events, and if registration hasn't occurred before crystallisation, the company faces immediate practical difficulties. Banks routinely monitor charge registration status and may accelerate facilities or refuse further lending if registration requirements aren't met promptly.
Companies operating across multiple jurisdictions must coordinate registration requirements carefully. A charge over assets in Scotland requires registration with Registers of Scotland in addition to Companies House, whilst charges over assets in other jurisdictions may have entirely different registration regimes. Missing any jurisdiction's requirements can compromise the entire security structure.
Common Registration Errors and How to Avoid Them
Practical experience reveals several recurring mistakes that compromise charge registration effectiveness. Incomplete or inaccurate property descriptions represent the most frequent error, particularly with charges over multiple properties or complex asset portfolios. The particulars must identify the charged property with sufficient precision to enable third parties to understand exactly what assets are affected.
For charges over land, simply stating "the freehold property known as [address]" may prove insufficient if the company owns multiple interests at the same location. The registration should specify whether the charge covers freehold, leasehold, or both interests, and identify any excluded areas or rights. Title numbers provide the most reliable identification method, but these must be verified against current Land Registry records.
Charges over intellectual property require particularly careful description. A charge over "all trade marks" owned by the company differs significantly from a charge over "registered trade marks," and both differ from charges over specific trademark applications. Patent charges must distinguish between granted patents and pending applications, as these carry different legal characteristics and values.
Book debt charges frequently suffer from overly broad or insufficiently specific descriptions. Stating simply "all book debts and other debts due or owing to the company" may not adequately cover future debts or debts arising from specific trading relationships. More sophisticated drafting might specify "all present and future book debts, trade debts, and other debts and monetary claims due or owing to the company including but not limited to..." followed by specific categories relevant to the company's business.
Currency denomination errors create unnecessary complications, particularly for international transactions. The amount secured should be stated in the currency of the underlying obligation, with sterling equivalents calculated at current exchange rates where helpful. However, avoid stating fixed sterling equivalents for foreign currency obligations, as these become misleading as exchange rates fluctuate.
Timing coordination between legal completion and registration filing requires careful project management. The charge document must be executed before registration can occur, but the registration must be filed within the 21-day deadline. This creates particular challenges for transactions completing on Fridays or before bank holidays, where the registration window may be compressed by non-working days.
Special Considerations for Different Types of Security
Different categories of security instruments present unique registration challenges that require specialised knowledge. Debentures often combine multiple types of security within a single document, potentially covering fixed charges over specific assets alongside floating charges over general undertakings. The MR01 form must capture all these elements accurately, which may require multiple entries or supplementary documentation.
All-assets debentures present particular complexity because they typically include both present and future assets. The registration must adequately describe the scope without creating uncertainty about what assets are actually covered. Standard form debentures from major law firms usually contain tried-and-tested language, but bespoke security documents require more careful analysis to ensure the registration accurately reflects the security granted.
Retention of title arrangements occupy a grey area in registration requirements. Simple retention of title clauses in supply contracts typically don't require registration as charges, but more sophisticated arrangements that grant security over processed goods or impose obligations to hold proceeds on trust may cross the threshold into registrable territory. The distinction often depends on the specific wording and the commercial substance of the arrangement.
Charges over shares in subsidiary companies require careful attention to the mechanics of share transfers and voting rights. The registration should specify whether the charge covers just the shares themselves or extends to dividends and other distributions. For shares in foreign subsidiaries, additional perfection steps may be required under the law of the company's incorporation jurisdiction.
Hire purchase and conditional sale agreements where the company is the buyer may require registration if they create charges over the financed assets. However, the registration requirements depend on the specific terms and whether the company obtains sufficient rights in the assets to grant security over them. This analysis requires careful legal review of the financing documentation.
Pension scheme charges present unique challenges because of the regulatory overlay from the Pensions Regulator and trustees' fiduciary duties. While such charges are registrable at Companies House like any other security, the practical implications of enforcement may be constrained by pensions legislation and trustee obligations. Companies should ensure their registration accurately reflects these limitations.
Green finance instruments, including sustainability-linked loans and green bonds, may include environmental performance covenants that affect the security structure. While these don't typically change the core registration requirements, they may influence how the charge is described and what additional documentation should be filed to provide complete disclosure to potential creditors and investors.