When Changes Strike Your Limited Partnership: The Critical LP6 Filing Window
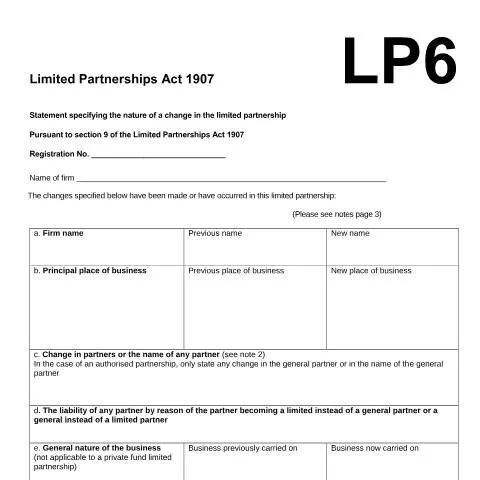
The moment a limited partnership undergoes any structural change—whether it's a partner departure, a shift in business focus, or a change of registered address—the clock begins ticking. Under the Limited Partnerships Act 1907, you have precisely seven days to notify Companies House via form LP6, officially titled "Statement specifying the nature of a change in the limited partnership".
This statutory requirement isn't merely bureaucratic housekeeping. It maintains the integrity of the public register, protects creditor interests, and ensures your partnership remains compliant with UK law. The LP6 form serves as the official conduit for reporting everything from partner additions and capital contributions to fundamental business transformations that could affect third parties dealing with your partnership.
The form's scope extends beyond traditional limited partnerships to encompass authorised partnerships under the Financial Services and Markets Act 2000 and those governed by European Long-term Investment Funds regulations. Each category carries distinct notification requirements that can trap the unwary.
Decoding the Seven Categories of Reportable Changes
Form LP6 segments partnership changes into seven distinct categories, each with specific disclosure requirements and potential pitfalls. Understanding these sections prevents costly oversights and ensures comprehensive compliance.
Section A: Firm Name Alterations
Name changes appear straightforward but require careful attention to effective dates. The form demands both the previous name and new name, with the change taking legal effect only upon Companies House registration. Trading under a new name before registration can create liability issues, particularly in contractual relationships where counterparties rely on the registered name.
Section B: Principal Place of Business Relocations
Address changes encompass more than simple office moves. The "principal place of business" represents where the partnership conducts its primary operations, not merely where mail is received. For partnerships with multiple locations, determining which qualifies as "principal" requires examining factors like:
- Volume of business transactions conducted
- Location of key decision-making activities
- Where partnership books and records are maintained
- Geographic centre of operational activities
Section C: Partner Changes and Identity Modifications
This section captures the partnership's most dynamic element—its membership. Changes include partner additions, departures, and name changes of existing partners. For authorised partnerships, however, the scope narrows significantly: only changes affecting the general partner require notification, while limited partner modifications remain unreported.
Death of a partner triggers mandatory notification, regardless of whether the deceased's interest transfers automatically under the partnership agreement. Similarly, transfers of partnership interests—even between existing partners—constitute reportable changes if they alter the partnership's registered structure.
Section D: Partner Status Transitions
The conversion between limited and general partner status fundamentally alters liability exposure and operational rights. A limited partner accepting general partner responsibilities assumes unlimited liability for partnership debts, while a general partner reducing to limited status gains liability protection but loses management authority.
These transitions often occur during succession planning or when external investors seek greater control. The form requires detailed explanation of the status change and its effective date, as liability implications begin immediately upon the change occurring, not upon Companies House registration.
Section E: Business Nature Evolution
Changes in business activities can trigger regulatory consequences beyond Companies House filing. The form requires description of both previous and current business activities, with sufficient detail to enable third parties to understand the partnership's commercial focus.
Note that private fund limited partnerships are exempt from this section, reflecting their specialised regulatory framework under alternative investment fund legislation.
Section F: Partnership Term and Character Modifications
This section addresses fundamental structural changes, including:
- Extension or reduction of partnership duration
- Conversion to or from fixed-term arrangements
- Authorisation as a regulated partnership scheme
- Revocation of regulatory authorisation
For partnerships without definite terms, the form requires explanation of constitutional conditions both before and after the change. Authorised partnerships must include authorisation order details, including Financial Conduct Authority reference numbers and effective dates.
Section G: Capital Contribution Variations
Capital changes represent the most complex reporting category, with different rules applying based on partnership type. Standard limited partnerships must report all contribution increases, whether from existing partners or new members. The form distinguishes between cash and non-cash contributions, requiring detailed particulars for the latter.
Authorised partnerships and most private fund limited partnerships enjoy exemption from capital reporting requirements. However, private fund limited partnerships registered before 6 April 2017 must report limited partner withdrawals that reduce contributions below the designation date level.
Navigating Special Partnership Categories
The LP6 form accommodates three distinct partnership types, each with tailored reporting requirements that reflect their regulatory environments.
Authorised Partnerships Under Financial Services Regulation
Partnerships authorised as collective investment schemes under the Financial Services and Markets Act 2000 operate under modified notification requirements. The Collective Investment in Transferable Securities (Contractual Scheme) Regulations 2013 limit reporting obligations to general partner changes only.
This streamlined approach recognises that limited partners in authorised schemes are essentially investors rather than active participants. Their identity changes don't affect the partnership's operational capacity or regulatory standing, unlike general partner modifications that could impact fund management capabilities.
European Long-term Investment Funds
Partnerships authorised under Regulation (EU) No 2015/760 follow similar restricted reporting patterns. Despite Brexit, existing ELTIF authorisations remain valid under transitional arrangements, though new applications now follow UK-specific procedures.
These partnerships must report authorisation order changes, including Financial Conduct Authority decisions affecting their regulated status. The form requires inclusion of the actual authorisation documentation, not merely reference numbers.
Private Fund Limited Partnerships
Private fund limited partnerships benefit from the most extensive reporting exemptions, reflecting their sophisticated investor base and alternative regulatory oversight. Sections E and F become inapplicable, while Section G applies only in specific withdrawal scenarios for pre-2017 registrations.
This differential treatment acknowledges that private fund limited partnerships operate under separate regulatory frameworks that provide appropriate investor protections without requiring detailed Companies House disclosure.
Critical Filing Mechanics and Timing Requirements
The seven-day filing window begins when changes "take place," not when they're formally documented or agreed. This timing can create practical challenges, particularly for complex transactions involving multiple simultaneous changes.
| Change Type | Trigger Date | Common Timing Issues |
|---|---|---|
| Partner admission | Execution of partnership agreement amendment | Conditional admissions pending regulatory approval |
| Address change | Actual relocation of business operations | Phased moves over multiple locations |
| Capital contributions | Receipt of funds or assets | Staged payments over extended periods |
| Name changes | Partnership resolution adoption | Coordination with trademark registrations |
The form requires signature "by the firm," which typically means any general partner or authorised signatory. For partnerships with multiple general partners, any one can sign, but internal governance arrangements may require broader consultation before filing.
Preparing Supporting Documentation and Evidence
While the LP6 form itself is relatively concise, proper completion often requires substantial supporting documentation to ensure accuracy and compliance.
Partnership Agreement Amendments
Most reportable changes stem from partnership agreement modifications. Maintaining current, executed versions of all amendments provides the factual foundation for LP6 completion and demonstrates proper internal authorisation for reported changes.
Capital Contribution Records
Section G requires precise figures for contribution increases and total amounts. Bank statements, asset transfer documents, and valuation reports for non-cash contributions provide essential verification. For partnerships accepting property or intellectual property contributions, professional valuations may be necessary to determine reportable amounts.
Regulatory Documentation
Authorised partnerships must include copies of Financial Conduct Authority orders when reporting authorisation changes. These documents provide official confirmation of regulatory status modifications and their effective dates.
Corporate Partner Information
When corporate entities serve as partners, their own structural changes may trigger LP6 reporting requirements. Name changes, mergers, or reorganisations affecting corporate partners constitute partnership changes requiring notification.
Public Record Implications and Strategic Considerations
The LP6 form concludes with a stark reminder: "all information on this form will be available on the public record." This transparency serves important public policy objectives but requires careful consideration of commercial sensitivities.
Capital contribution details become publicly accessible, potentially revealing partnership financial strength or investor commitment levels to competitors and creditors. Business nature descriptions provide insight into strategic direction and operational focus that may have competitive implications.
Partner identity disclosures can affect privacy expectations, particularly for high-profile individuals or entities seeking to maintain investment anonymity. While limited partnerships offer some privacy protection compared to companies, LP6 filings create permanent public records of structural changes.
Timing Strategic Announcements
The seven-day filing requirement can conflict with commercial announcement timing. Public companies may prefer coordinating LP6 filings with broader market communications to ensure consistent messaging about partnership developments.
Similarly, partnerships undergoing complex transactions may benefit from consolidating multiple changes into single LP6 filings where timing permits, reducing administrative burden and providing clearer public record documentation.
Compliance Failures and Remedial Actions
Missing the seven-day deadline doesn't invalidate the underlying partnership changes, but it creates regulatory non-compliance that may have consequences beyond Companies House penalties.
Late filings remain acceptable and necessary—Companies House doesn't reject LP6 forms based solely on timing. However, the delay may affect third-party reliance on public records and could complicate future transactions requiring clean compliance histories.
Discovering Historical Omissions
Partnerships reviewing their compliance status may discover unreported changes from previous years. While historical LP6 filings can remedy these omissions, they create permanent public records of non-compliance timing that may require explanation in future due diligence processes.
The appropriate response involves filing LP6 forms for all unreported changes, regardless of their age. Include clear effective dates for each change to establish the factual timeline, even when filing occurs significantly later.
Correcting Filing Errors
Errors in submitted LP6 forms require correction through new filings rather than amendments. The new filing should clearly identify the correction nature and reference the original submission being superseded.
Common errors include incorrect partner names, inaccurate addresses, or miscalculated contribution amounts. Each requires careful verification before submission to avoid compounding public record confusion.
For partnerships maintaining active business relationships, prompt error correction protects commercial credibility and ensures counterparties have access to accurate partnership information for their own compliance and risk management purposes.
Understanding Different Types of Partnership Changes and Their LP6 Requirements
The LP6 form accommodates various categories of changes, each requiring specific documentation and adherence to particular statutory timelines. Understanding which type of change you're reporting helps ensure accurate completion and compliance with Companies House requirements.
Changes to Partner Details and Status
When existing partners undergo changes in their personal or business circumstances, these modifications must be reflected in the partnership records. For individual partners, this includes changes to residential addresses, which must be reported within 14 days of the change occurring. However, if the partner has provided a service address that differs from their residential address, only changes to the service address require immediate notification unless specifically requested by Companies House.
Corporate partners present additional complexity when reporting changes. If a corporate partner changes its registered office, company name, or undergoes restructuring such as a merger or acquisition, these changes must be documented through the LP6 process. The partnership must provide evidence of the corporate partner's new status, typically in the form of updated incorporation documents or certificates of name change issued by the relevant registrar.
Nationality changes for individual partners, whilst less common, also require notification. This might occur when a partner obtains British citizenship or changes their nationality through naturalisation in another country. Such changes can have implications for the partnership's tax status and regulatory obligations, particularly if the partnership operates in sectors with foreign ownership restrictions.
Modifications to Partnership Structure and Governance
Structural changes represent some of the most significant modifications requiring LP6 notification. These encompass alterations to the fundamental nature of how the partnership operates, including changes to profit-sharing arrangements, voting rights, or management structures that may not necessarily involve partner additions or removals.
When a partnership decides to alter its profit and loss sharing ratios among existing partners, this constitutes a material change requiring formal notification. Such modifications often arise from changes in partners' contributions, responsibilities, or the partnership's strategic direction. The LP6 form must specify the new arrangements clearly, including effective dates and any transitional provisions.
Decision-making authority changes also fall under this category. If the partnership agreement is amended to alter which partners have authority to bind the partnership in specific types of transactions, or if management responsibilities are redistributed among partners, these changes must be documented. This is particularly relevant for partnerships where certain partners may have been granted enhanced decision-making powers or where previously equal partners are moving to a tiered management structure.
Geographic expansion or contraction of the partnership's operations may trigger LP6 requirements if they involve changes to the partnership's registered particulars or if they affect the partnership's legal status in different jurisdictions. For instance, if a partnership previously operating solely in England decides to establish operations in Scotland, this may require notification of changes to business addresses or operational scope.
Capital and Financial Structure Modifications
Changes to the partnership's capital structure often necessitate LP6 filings, particularly when they affect the legal relationships between partners or alter the fundamental financial architecture of the business. These modifications extend beyond simple capital contributions to encompass more complex financial arrangements.
When partners agree to modify their capital contribution requirements, whether increasing or decreasing individual commitments, this typically requires formal notification. Such changes might arise from business expansion needs, where additional capital is required from existing partners, or from business contraction, where capital may be returned to partners. The LP6 form must detail the nature of these changes, including any altered payment schedules or contribution methods.
Introduction of new classes of partnership interests represents another category requiring careful documentation. Some partnerships may decide to create different categories of partnership stakes, each with distinct rights, obligations, or profit-sharing arrangements. This sophisticated structuring requires detailed explanation in the LP6 submission, including clear descriptions of each class's characteristics and the allocation among partners.
Guarantee modifications also fall under this category. If the partnership agreement is amended to alter personal guarantees provided by partners for partnership debts, or if new guarantee arrangements are introduced, these must be reported. This is particularly significant for limited partnerships where the distinction between limited and general partner liability is fundamental to the partnership's legal structure.
Security arrangements changes, such as modifications to how partners' interests may be used as collateral or alterations to existing charge arrangements over partnership assets, require notification. These changes can significantly impact both the partnership's financial flexibility and individual partners' risk exposure.
Administrative Procedures and Documentation Requirements
Successful LP6 submission requires meticulous attention to supporting documentation and adherence to specific administrative procedures established by Companies House. Understanding these requirements prevents delays and ensures compliance with statutory obligations.
Supporting Evidence and Documentation Standards
Each type of change reported through LP6 requires specific supporting documentation to validate the modification. Companies House maintains strict standards for acceptable evidence, and failure to provide appropriate documentation typically results in rejection of the filing or requests for additional information.
For partner address changes, acceptable evidence includes recent utility bills, council tax statements, or bank statements dated within the preceding three months. However, if the partner is using a service address that differs from their residential address, the documentation requirements may vary. Service addresses require evidence of the service provider's legitimacy, such as professional registration details for solicitors or accountants providing the service.
Corporate partner changes demand more extensive documentation. If a corporate partner has changed its name, a certified copy of the certificate of incorporation showing the name change must accompany the LP6 form. For changes in corporate structure, such as mergers or acquisitions, the partnership must provide evidence of the new corporate entity's legal status and confirmation that it has assumed the previous entity's partnership obligations.
Partnership agreement amendments require careful documentation to demonstrate that proper procedures were followed. This typically includes minutes of partnership meetings showing the decision-making process, evidence of partner consultation where required by the existing agreement, and copies of the amended agreement sections. If the partnership agreement requires specific voting thresholds or procedures for amendments, evidence of compliance with these requirements must be provided.
Financial changes, such as capital contribution modifications, may require additional evidence depending on their nature. If changes involve significant sums or alter the fundamental financial structure of the partnership, Companies House may request evidence of the partners' financial capacity to meet new obligations or documentation showing how existing obligations are being modified.
Timing Requirements and Statutory Deadlines
The LP6 filing process operates under strict statutory deadlines that vary depending on the nature of the change being reported. Understanding these timelines is crucial for maintaining compliance and avoiding potential penalties or complications with the partnership's legal status.
Most partner-related changes must be notified within 14 days of their occurrence. This includes changes to partner addresses, appointment of new partners, and cessation of existing partners. However, the calculation of this 14-day period can be complex, particularly when changes occur on weekends or during periods when Companies House is closed. The deadline is calculated using working days, excluding weekends and public holidays, but partners should not assume automatic extensions for these periods.
Structural changes to the partnership may have different timing requirements depending on their nature. Changes that affect the partnership's fundamental legal structure typically require notification within 14 days, whilst administrative changes may have more flexible deadlines. However, distinguishing between these categories can be challenging, and partnerships should err on the side of caution by treating all significant changes as subject to the 14-day requirement.
International considerations add complexity to timing requirements. If changes involve partners located outside the United Kingdom, additional time may be required to obtain necessary documentation or translations. However, this does not automatically extend the statutory deadline, and partnerships must plan accordingly to ensure timely submission.
Retrospective filings, whilst sometimes unavoidable, require special attention. If a partnership discovers that changes have occurred but were not reported within the statutory deadline, the LP6 form must clearly explain the circumstances and reasons for the delay. Companies House has discretion in how it handles late filings, and providing clear, honest explanations improves the likelihood of acceptance without additional complications.
Consequences and Compliance Implications
Understanding the broader implications of LP6 filings extends beyond mere administrative compliance to encompass significant legal, financial, and operational consequences for the partnership and its stakeholders.
Legal and Regulatory Ramifications
Failure to properly notify changes through the LP6 process can result in serious legal consequences that extend far beyond simple administrative penalties. The partnership's legal status may be compromised, affecting its ability to operate effectively and potentially exposing partners to unexpected liabilities.
When partnerships fail to notify partner changes promptly, questions may arise about the authority of individuals to act on behalf of the partnership. Third parties dealing with the partnership rely on publicly available information at Companies House to determine who has authority to bind the partnership in contractual arrangements. If this information is outdated due to non-compliance with LP6 requirements, the partnership may face disputes about contract validity or find itself bound by agreements entered into by individuals who no longer have authority to act on its behalf.
Tax implications represent another critical area of concern. HM Revenue and Customs relies on partnership information filed with Companies House for various tax administration purposes. If LP6 filings are incomplete or inaccurate, this can lead to complications with partnership tax returns, self-assessment obligations for individual partners, and potential disputes about tax liability allocation among partners.
Regulatory compliance in specific sectors may also be affected by LP6 filing accuracy. Partnerships operating in regulated industries such as financial services, legal services, or healthcare may find that regulatory authorities rely on Companies House information for licensing and compliance monitoring purposes. Inaccurate or outdated information can trigger regulatory investigations or compromise the partnership's ability to maintain necessary licenses or authorisations.
Insurance implications should not be overlooked. Many professional indemnity and commercial insurance policies require partnerships to maintain accurate public records and notify insurers of material changes. Failure to properly document changes through LP6 filings may compromise insurance coverage or provide insurers with grounds to deny claims.
Operational and Commercial Impacts
Beyond legal consequences, LP6 compliance affects the partnership's day-to-day operations and commercial relationships in ways that may not be immediately apparent but can have significant long-term implications.
Banking relationships often depend on accurate partnership information for account management, credit decisions, and regulatory compliance. Banks regularly review Companies House records for their business customers, and discrepancies between filed information and actual partnership arrangements can trigger account reviews, credit restrictions, or requirements for additional documentation. This is particularly relevant for partnerships seeking new credit facilities or attempting to modify existing banking arrangements.
Commercial counterparties increasingly conduct due diligence on business partners using publicly available information. Potential clients, suppliers, or joint venture partners may review Companies House records as part of their assessment process. Inaccurate or outdated LP6 information can create unnecessary complications in commercial negotiations or raise questions about the partnership's attention to regulatory compliance.
Property transactions present another area where LP6 compliance becomes practically significant. When partnerships buy, sell, or lease commercial property, solicitors and other professionals involved in the transaction typically conduct searches of Companies House records to verify the partnership's status and the authority of individuals acting on its behalf. Discrepancies can delay transactions or require additional legal work to resolve.
Dispute resolution processes may also be affected by LP6 compliance. If partnerships become involved in commercial disputes or litigation, accurate Companies House records become important evidence about the partnership's structure, partner authority, and operational arrangements. Inaccurate filings can complicate legal proceedings and potentially weaken the partnership's position in disputes.
International business relationships add another layer of complexity. Foreign counterparties often rely heavily on official government records when assessing UK business partners, and Companies House information serves as a primary source of verification. Maintaining accurate LP6 filings becomes particularly important for partnerships engaged in international trade, seeking foreign investment, or establishing overseas operations.