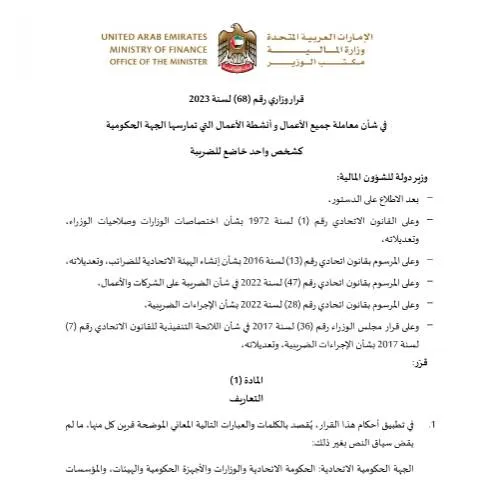
Understanding the Role of the Ministerial Resolution No. 68 of 2023
The recent Ministerial Resolution No. 68 of 2023, issued by the التشريعات الضريبية (Tax Authority), has transformed the way governmental entities in the UAE are treated for tax purposes. This resolution outlines the requirements for treating governmental activities as a single taxable entity, a significant change aimed at improving the efficiency of tax compliance among federal and local government bodies.
The Context of the Ministerial Resolution
The UAE's tax landscape has seen significant evolution since the introduction of corporate tax laws. Ministerial Resolution No. 68 of 2023 aligns with the Federal Law No. 47 of 2022 regarding Corporate Tax, providing clarity on how businesses operated by government entities are to be treated. Understanding this document is essential for compliance and efficient tax management.
Key Features of the Resolution
This resolution provides a framework under which government entities can opt to be treated as a single taxable entity. Here’s what you need to know:
- Unified Tax Treatment: Government entities can request to be assessed as a single taxable entity, simplifying the tax process.
- Eligibility Criteria: A set of conditions must be met to qualify for this treatment, including licensing and compliance with corporate tax laws.
- Designated Representation: Each entity must appoint a representative responsible for ensuring compliance with tax obligations.
Eligibility Criteria for Tax Treatment
To qualify for treatment as a single taxable entity, federal and local government entities must meet certain requirements:
- All business activities must be included in the request for treatment.
- Activities must be conducted under a valid license issued by the appropriate licensing authority.
- The application must be submitted by the designated representative of the governmental entity.
The Process: Submission and Compliance
Submitting an application under this resolution requires careful navigation of the bureaucratic processes involved. Here’s a step-by-step guide:
- Preparation: Gather all necessary documentation, including licenses and operational details of the governmental activities.
- Application Submission: Submit the request to التشريعات الضريبية through their designated platform, ensuring that all information is complete and accurate.
- Await Approval: The Tax Authority will review the application and may request additional information before granting approval.
Timelines for Application
| Stage | Duration |
|---|---|
| Preparation of Documentation | Variable (depends on the entity) |
| Review by Tax Authority | Up to 30 days |
| Notification of Approval | Immediate upon decision |
Implications of the Resolution for Government Entities
Understanding the implications of this resolution is crucial for government entities. Here’s a closer look at what this means in practice:
- Streamlined Tax Compliance: By treating multiple entities as one, the government reduces the complexity of compliance.
- Tax Obligations: Entities are now required to maintain accurate records and adhere to tax reporting schedules accurately.
- Consequences of Non-Compliance: Failure to adhere to the resolution could result in penalties or the termination of the single taxable entity status.
Responsibilities of the Designated Representative
The designated representative plays a crucial role in ensuring compliance with the resolution. This individual is responsible for:
- Submitting all necessary documentation to the Tax Authority.
- Communicating with the government entities involved to ensure all activities are covered under the tax treatment.
- Maintaining records and providing updates to the Tax Authority as required.
Scenarios: When Special Considerations Apply
While many entities will follow the standard guidelines outlined in the resolution, certain scenarios may require additional attention:
- Foreign Involvement: If a governmental entity engages in activities involving foreign entities, additional tax implications may need to be considered.
- Changes in Activities: Should a government entity cease an activity or change its scope, it must notify the tax authority within 20 business days.
- Emergency Situations: Structures should be in place for rapid compliance in times of emergency that may alter normal operational capacities.
Termination of Single Taxable Entity Status
There are circumstances under which the treatment as a single taxable entity can be terminated:
- Upon approval of a request to cease this treatment by the Tax Authority.
- Failure to meet the conditions specified in the resolution.
Conclusion: Navigating the New Tax Landscape
Ministerial Resolution No. 68 of 2023 represents a significant shift in the tax framework for government entities in the UAE. By providing clear guidelines for tax treatment as a single entity, it promotes efficiency and compliance within governmental operations. Entities must take the necessary steps to understand their obligations under this resolution to avoid penalties and ensure smooth operations.
Understanding Ministerial Decision No. (68) of 2023: Implications for Public Entities in the UAE
The Ministerial Decision No. (68) of 2023 marks a significant shift in the compliance and operational framework for government entities in the UAE. This decision aims to treat all business activities conducted by a governmental body as a single taxable entity, reflecting a more streamlined approach to taxation and accountability. The underlying objective is to enhance transparency in fiscal operations and ensure equitable tax contributions across the board.
Under this decision, entities must closely evaluate their existing operations to determine how their various activities may be aggregated for tax purposes. This means that any revenue generated by different segments of a government entity will be considered collectively, rather than in isolation. The implications of this are multifaceted; not only does it necessitate a thorough understanding of the tax implications but also a reevaluation of the internal processes and reporting structures within these entities.
One critical aspect to consider is the classification of activities. Government entities often engage in a diverse range of services, from core administrative functions to commercial activities. This decision requires entities to categorize their activities accurately and maintain meticulous records to substantiate their tax filings. Failure to comply can lead to financial penalties and reputational risks.
Furthermore, the decision compels government entities to engage more proactively with the Federal Tax Authority (FTA) to ensure compliance. Regular consultations with tax experts and thorough audits of financial practices will be paramount in adapting to this new regulatory landscape.
Operational Changes Enforced by the Ministerial Decision
As the UAE continues to evolve its taxation landscape, the operational changes mandated by Ministerial Decision No. (68) of 2023 signal a critical reorientation for government entities. The decision requires these bodies to establish comprehensive tax compliance frameworks that reflect the new singular approach to taxation.
One of the primary operational changes involves the integration of digital tax reporting systems. Government entities will need to leverage the Emirates ID system and the UAE Pass for digital identity management to ensure seamless tax reporting and compliance. This digital integration not only streamlines the process but also enhances accountability by allowing for real-time monitoring of tax obligations.
Moreover, internal training programs focusing on tax compliance will be essential. Staff within government entities must be equipped with the knowledge and skills to navigate the complexities introduced by this decision. This may include workshops led by the FTA or partnerships with specialized tax consultancies to keep abreast of evolving regulations and best practices. Emphasizing continuous learning will be crucial to fostering a culture of compliance and awareness within these organizations.
Additionally, entities must also establish clear communication channels for addressing inquiries and issues related to tax compliance. This includes designating a tax compliance officer or team responsible for liaising with the FTA, managing audits, and ensuring that all operational activities adhere to the new regulations.
Case Studies: Impact of Ministerial Decision No. (68) on Specific Government Sectors
To comprehend the full impact of Ministerial Decision No. (68) of 2023, it is essential to examine its implications across various government sectors. Different sectors may experience unique challenges and opportunities stemming from this new tax treatment of activities.
For instance, in the education sector, institutions operated by the government often generate revenues through tuition fees, grants, and various service charges. Under the new decision, these revenues will need to be aggregated and reported as part of a singular taxable unit. Educational institutions must develop strategies to align their pricing structures with tax obligations, potentially affecting how they set tuition rates and manage scholarships.
Similarly, in the healthcare sector, government-run hospitals and clinics provide a mix of free and billable services. The aggregation approach will necessitate a thorough review of how these services are classified and billed. Healthcare entities will need to engage with stakeholders to ensure that the new tax framework does not inadvertently discourage the provision of certain services or lead to increased costs for the public.
Furthermore, entities within the tourism sector, such as government-run attractions and visitor services, will need to develop comprehensive tax compliance strategies to account for their diverse revenue streams. This could involve revisiting marketing strategies to ensure that pricing reflects the tax responsibilities associated with the aggregated income from these services.
In each case, the need for sector-specific adaptations is clear. Government entities must be prepared to navigate the complexities introduced by the decision while maintaining their overarching missions to serve the public efficiently.