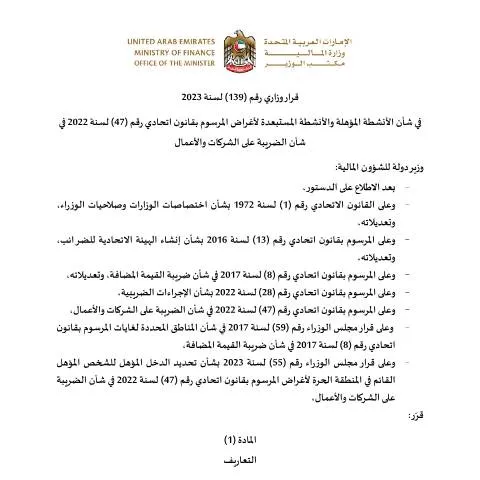
Overview of Ministerial Resolution No. 139 of 2023 on Eligible and Excluded Activities for Corporate Taxation in the UAE
The United Arab Emirates (UAE) continues to refine its corporate tax framework through the issuance of Ministerial Resolution No. 139 of 2023. This regulation provides detailed clarification on which activities are classified as eligible or excluded for the purposes of the Federal Decree-Law No. 47 of 2022 concerning corporate and business taxation. It aims to enhance transparency, compliance, and administrative efficiency within the UAE’s evolving tax landscape.
Scope and Legal Context
This resolution is issued by the Ministry of Finance (MOF) and serves as a supplementary guideline to the federal corporate tax law. It delineates specific activities that are either considered eligible for tax purposes or are explicitly excluded from the tax regime. The document is part of the UAE’s broader strategy to develop a robust and clear tax system aligned with international standards and the UAE’s legal framework established under the UAE Constitution.
Key Objectives of the Resolution
- Clarify the classification of activities: To specify which commercial, industrial, or service activities qualify for certain tax treatments under the federal law.
- Define excluded activities: To identify activities that are exempt from certain tax obligations, either due to their nature or strategic importance.
- Support compliance and enforcement: To facilitate accurate reporting and reduce ambiguities for taxpayers and tax authorities alike.
Who Is Affected by the Resolution?
The resolution primarily impacts companies and individuals engaged in various economic activities within the UAE. It is essential for taxpayers to understand whether their activities fall within the scope of eligible or excluded categories to ensure proper tax reporting and compliance. Additionally, tax consultants, legal advisors, and government agencies involved in tax administration should refer to this document for consistent interpretation and enforcement.
Core Provisions and Classifications
Eligible Activities
Activities deemed eligible typically include those aligned with the UAE’s strategic economic sectors, such as manufacturing, technology, renewable energy, and certain service industries. These activities are recognized as contributing positively to the national economy and are therefore granted specific tax treatments or incentives.
Excluded Activities
Conversely, the resolution lists activities that are excluded from the favorable tax regime. These may encompass certain financial services, real estate transactions, or other sectors deemed to require different tax considerations or subject to specific restrictions. The exclusions aim to prevent potential tax base erosion and ensure compliance with international standards.
Implementation and Compliance
Taxpayers are advised to carefully review the classifications outlined in this resolution to determine the applicable treatment for their activities. It is recommended to consult with qualified tax professionals or legal advisors to interpret the classifications accurately and ensure adherence to the relevant provisions. The UAE’s digital tax administration platforms and the Ministry of Finance’s official channels provide ongoing updates and guidance to facilitate compliance.
References and Further Guidance
This resolution complements other regulatory frameworks issued by the UAE authorities, including the Federal Tax Authority (FTA) guidelines and related ministerial decisions. For comprehensive understanding and updates, taxpayers should regularly consult the official publications from the Ministry of Finance and the FTA’s official portal.
Conclusion
Ministerial Resolution No. 139 of 2023 represents a significant step towards clarifying the scope of activities subject to corporate taxation in the UAE. By defining eligible and excluded activities, the UAE aims to foster a transparent, fair, and compliant tax environment conducive to sustainable economic growth. Businesses operating within the UAE should stay informed about these classifications to ensure proper tax planning and adherence to the legal requirements set forth by the authorities.