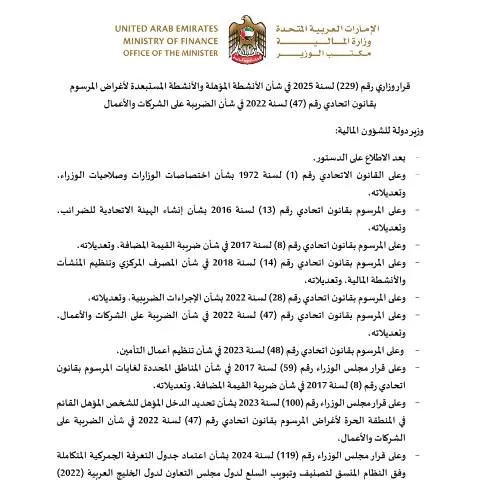
Understanding the Ministerial Decision No. 229 of 2025 on Qualified and Excluded Activities for Corporate Taxation in the UAE
The United Arab Emirates continues to refine its fiscal policy framework to promote economic growth and ensure compliance with its legal standards. A key development in this context is the issuance of Ministerial Decision No. 229 of 2025, which delineates the scope of activities considered qualifying and excluded under the federal corporate tax law. This guide aims to clarify the purpose, scope, and implications of this decision for businesses operating within the UAE.
Context and Purpose of the Ministerial Decision
The decision is issued pursuant to Federal Decree-Law No. 47 of 2022 on Corporate Tax, which introduced a comprehensive tax regime applicable to a broad spectrum of commercial activities across the federation. Recognizing the importance of clear categorization, the Ministry of Finance (MOF) has adopted this ministerial decision to specify which activities are deemed eligible for certain tax incentives or exemptions, and which are excluded due to their nature or potential for abuse.
This classification aims to foster transparency, facilitate compliance, and support strategic planning for both local and international entities. It aligns with the UAE's broader objectives of maintaining a competitive yet compliant business environment, reinforced by the digitalization of regulatory processes and the integration of federal and emirate-level authorities.
Scope and Applicability
The decision applies to all businesses subject to the UAE corporate tax regime, regardless of their jurisdiction within the federation. It provides a detailed list of activities that are considered qualifying, meaning they may benefit from specific tax treatments or incentives, and those that are excluded, which are considered incompatible with the objectives of the tax law or pose risks of tax avoidance.
Importantly, the classification impacts entities across various sectors, including manufacturing, finance, technology, and services. Companies must review their activities in light of this decision to determine their eligibility for incentives or their obligation to adhere to specific compliance requirements.
Key Elements of the Decision
Qualifying Activities
- Activities that contribute directly to the UAE's economic diversification and sustainable development.
- Innovative sectors such as technology development, renewable energy, and advanced manufacturing.
- Services that support the core economic sectors, including logistics, financial services, and professional consulting.
Excluded Activities
- Activities deemed to be primarily passive or speculative, such as certain financial trading operations.
- Activities that involve illicit, unethical, or socially harmful practices, in line with national laws and regulations.
- Any activity explicitly listed as excluded within the detailed annexes of the decision, which are subject to periodic updates by the Ministry of Finance.
Implications for Businesses and Compliance
Businesses should conduct a thorough review of their operational activities to determine their classification under this decision. The process involves cross-referencing their activity descriptions with the official list provided by the Ministry of Finance. This review is essential for ensuring compliance with the federal corporate tax regulations and for optimizing their tax position within the legal framework.
Furthermore, entities engaged in activities classified as excluded may need to adjust their operations or seek specific approvals to avoid penalties or non-compliance issues. The decision underscores the importance of maintaining accurate and detailed records of activities, which can be verified during tax audits or compliance checks conducted by the Federal Tax Authority (FTA).
References and Regulatory Framework
The Ministerial Decision No. 229 of 2025 is part of the broader legal and regulatory ecosystem governing corporate taxation in the UAE. It complements the provisions of Federal Decree-Law No. 47 of 2022 and aligns with the strategic objectives of the UAE's tax policies.
For comprehensive guidance, businesses and stakeholders are encouraged to consult official publications from the Ministry of Finance (MOF), the Federal Tax Authority (FTA), and other relevant authorities. These bodies provide detailed annexes, updates, and procedural instructions to facilitate compliance and optimal tax planning.
In summary, Ministerial Decision No. 229 of 2025 plays a crucial role in clarifying the scope of taxable activities, supporting compliance, and fostering a transparent business environment in the UAE. Companies are advised to stay informed of any updates or amendments to this decision to ensure ongoing adherence to the legal framework governing corporate taxation in the federation.