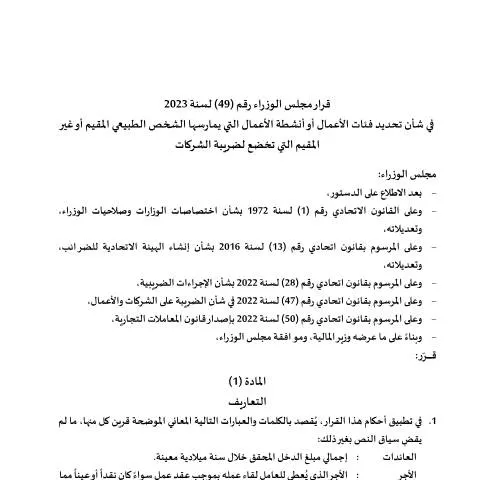
Understanding the Importance of Cabinet Decision No. 49 of 2023
The Cabinet Decision No. 49 of 2023, titled قرار مجلس الوزراء رقم (49) لسنة 2023 في شأن تحديد فئات الأعمال أو أنشطة الأعمال التي يمارسها الشخص الطبيعي المقيم أو غير المقيم التي تخضع لضريبة الشركات, plays a pivotal role in the regulatory landscape of the United Arab Emirates (UAE). Enacted on May 8, 2023, this resolution outlines specific categories of businesses and activities subject to corporate taxation within the UAE. This decision is crucial for both residents and non-residents, as it delineates tax obligations based on business activity classifications, ensuring compliance with local tax law.
Who is Required to Comply with This Decision?
Compliance with Cabinet Decision No. 49 affects a diverse range of individuals and entities operating in the UAE. Understanding the specific profiles of these stakeholders is essential for compliance. Below, we break down the relevant categories:
- Residents: Individuals who are legal residents of the UAE and engage in business activities.
- Non-residents: Foreign investors or companies conducting business within the UAE, who may not have a physical presence but still generate taxable income.
Further distinctions can be made based on the type of business activities being carried out:
Categories of Affected Business Activities
- Investment Income: Earnings from investments in local equities, bonds, and other financial instruments.
- Rental Income: Revenue from leasing properties, whether residential or commercial.
- Service Provision: Businesses providing services, including consultancy, logistics, and technology.
- Trading Activities: Engaging in the sale of goods, domestically or internationally.
The Role of Cabinet Decision No. 49 in Corporate Taxation
This decision serves as a foundational element in the UAE’s evolving tax framework. It establishes the parameters within which individuals and businesses will be subject to the newly implemented corporate tax, which is part of the UAE's broader strategy to enhance fiscal sustainability and diversify its economy.
More specifically, the Cabinet Decision provides clarity on:
- What types of businesses are subject to the corporate tax.
- The threshold of revenue that triggers tax liability.
- Exempt categories that are not subject to corporate taxation.
By clearly defining these elements, the resolution promotes transparency and compliance, which are essential for the efficient functioning of the tax system.
Step-by-Step Process for Filing and Compliance
For individuals and companies engaged in activities covered by Cabinet Decision No. 49, understanding the procedural framework for compliance is paramount. Here’s a detailed chronological guide:
Step 1: Identify Your Business Activities
The first step is to conduct a thorough assessment of your business operations to determine whether they fall under the categories specified in the decision. Consider engaging professional advice if you're uncertain.
Step 2: Gather Required Documentation
Prepare the necessary documents, which may include:
- Business licenses and permits.
- Financial statements from previous fiscal years.
- Contracts and agreements pertaining to your business activities.
Step 3: Complete the Official Form
After confirming your business activities and gathering documents, complete the official form relating to corporate tax obligations. Utilize the Emirates ID or reference number provided during registration for ease of processing.
Step 4: Submit the Completed Form
Submit your completed form through the appropriate channels as designated by the Federal Tax Authority (FTA). Ensure that you do this within any stipulated deadlines to avoid penalties.
Step 5: Await Confirmation and Further Instructions
Upon submission, the FTA will review your application. Be prepared to receive further instructions or requests for additional information if necessary. Prompt response to any inquiries will facilitate a smoother compliance process.
Supporting Documentation for Different Business Situations
Depending on the nature of your business, you may be required to provide additional documentation beyond basic forms. Below is a categorized breakdown:
| Business Type | Required Documentation |
|---|---|
| Investment Activities | Proof of investment transactions, portfolios, and income statements. |
| Property Rentals | Lease agreements, property ownership documents, and past rental income statements. |
| Service Providers | Client contracts, service agreements, and proof of service delivery. |
| Trading | Import/export documentation, sales invoices, and inventory records. |
Navigation Through Broader Regulatory Frameworks
Cabinet Decision No. 49 does not exist in isolation; it is part of a broader legal context that encompasses various regulations governing business operations in the UAE, particularly related to taxation.
- Federal Tax Authority (FTA): The principal body overseeing tax compliance and enforcement.
- Ministry of Finance (MoF): Responsible for the overall fiscal policy and implementation of tax laws.
- Local Government Regulations: Each emirate may have specific laws complementing federal legislation.
Understanding this ecosystem allows businesses to align their operations effectively while complying with all relevant laws.
The Impact of Non-Compliance and Best Practices for Adherence
Non-compliance with Cabinet Decision No. 49 can result in significant repercussions, including financial penalties, legal action, and reputational damage. To mitigate these risks, businesses are encouraged to adopt best practices:
- Regular Training: Stay informed about changes in tax regulations and requirements, ensuring all employees involved in legal compliance are adequately trained.
- Engage Legal Advisors: Consider consulting with tax professionals and legal experts familiar with UAE tax law to navigate compliance intricacies.
- Maintain Proper Records: Ensure that all business transactions are documented meticulously to facilitate easy reporting and compliance.
Proactive compliance not only safeguards against penalties but also contributes to a more sustainable business model in the rapidly evolving landscape of the UAE economy.
Conclusion: Embracing Change in Corporate Taxation
As the UAE continues to enhance its regulatory framework, understanding and adhering to decisions like Cabinet Decision No. 49 of 2023 is crucial for businesses seeking to operate successfully within this dynamic environment. By being informed and prepared, stakeholders can not only fulfill their obligations but also capitalize on opportunities in the growing Emirati market.
Understanding the Implications of Cabinet Resolution No. (49) of 2023 on Business Taxation
Cabinet Resolution No. (49) of 2023 marks a significant shift in the landscape of corporate taxation in the UAE. This resolution specifies the categories of businesses and activities that are subject to corporate tax for both resident and non-resident individuals. One of the most crucial aspects of this resolution is its alignment with international best practices, reflecting the UAE's commitment to enhancing its economic framework while ensuring compliance with global standards.
The resolution categorizes business activities under three main classifications: exempt activities, taxable activities, and activities subject to special tax treatment. This classification aims to provide clarity for business owners and investors on their tax obligations, thereby fostering a transparent business environment. For example, sectors such as oil and gas production and foreign banks have distinct treatment under the corporate tax regime, which is vital for stakeholders to understand to navigate the tax landscape effectively.
Moreover, the resolution stipulates specific compliance obligations for both businesses and individuals. These include maintaining proper records, timely filing of tax returns, and adherence to VAT guidelines outlined by the Federal Tax Authority (FTA). Non-compliance may lead to substantial penalties, hence the importance of understanding these nuances cannot be overstated. To enhance compliance, businesses are encouraged to leverage digital platforms provided by the FTA and other governmental bodies, ensuring that they stay informed and compliant with the evolving tax landscape.
Corporate Tax Registration Process for Residents and Non-Residents
The implementation of corporate tax also necessitates an efficient registration process for individuals and entities engaging in taxable activities. For both resident and non-resident individuals, the UAE provides a streamlined digital registration process through the FTA's online portal. The registration process begins with obtaining an Emirates ID, which serves as a digital identification for all administrative transactions.
Once an Emirates ID is secured, applicants must fill out a corporate tax registration form available on the FTA's portal. This form requires detailed information about the nature of the business activities, annual turnover, and any previous tax compliance history. Registration must be completed before conducting any taxable activities to avoid penalties.
Non-resident individuals engaging in business within the UAE should also be aware of the implications of establishing a tax presence. They may need to obtain a Tax Registration Number (TRN) and understand their obligations regarding withholding tax on income generated in the UAE. Moreover, engaging with local legal or tax advisory firms can be invaluable for non-residents unfamiliar with UAE regulations and the corporate tax framework.
Assessment and Enforcement Measures Post-Implementation
Following the enactment of Cabinet Resolution No. (49) of 2023, it is paramount to understand the assessment and enforcement measures that will be executed by the Federal Tax Authority (FTA). The FTA plays a crucial role in ensuring compliance with tax regulations and has been equipped with robust mechanisms to monitor business activities and evaluate tax obligations effectively.
One of the key measures includes the establishment of audit processes to assess the accuracy of tax filings. Businesses may be subjected to random or targeted audits based on various risk factors such as turnover, industry type, and compliance history. During these audits, businesses are required to present detailed records, including financial statements, invoices, and contracts, to substantiate their tax claims.
Furthermore, the FTA has the authority to impose penalties for non-compliance, which can range from fines to more severe consequences for repeated violations. To mitigate risks, businesses are encouraged to conduct internal audits to ensure compliance before official audits take place, thereby fostering a culture of transparency and accountability within the organization.
Additionally, the FTA will likely enhance its enforcement capabilities through digital tools, enabling real-time tracking and data analysis of business transactions. This digital approach aligns with the UAE's vision of embracing technology in governance and taxation, ensuring a more efficient tax system.
Ultimately, understanding these assessment and enforcement measures is critical for businesses to maintain compliance and avoid potential pitfalls in the newly established corporate tax environment.