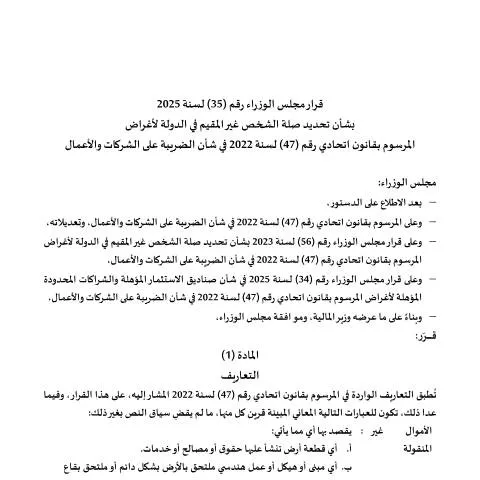
Overview of the Cabinet Decision No. (35) of 2025 on the Definition of Non-Resident Connection to the UAE for Corporate Tax Purposes
The recent issuance of Cabinet Decision No. (35) of 2025 by the United Arab Emirates (UAE) Government marks a significant step in clarifying the criteria used to determine whether a person is considered a non-resident for tax purposes under Federal Law No. (47) of 2022 concerning Corporate Tax. This decision aims to establish clear guidelines for identifying the connection of non-resident individuals and entities to the UAE, ensuring consistent application of tax regulations across all relevant jurisdictions within the country.
Context and Purpose of the Decision
In line with the UAE’s strategic move towards a comprehensive and transparent tax system, this decision complements existing legal frameworks by providing specific criteria to assess the residency status of non-resident persons. The primary goal is to define the parameters that establish a sufficient connection to the UAE, which influences the application of corporate tax obligations. This clarification is particularly pertinent given the increasing number of foreign businesses and individuals operating within the UAE’s dynamic economic environment.
Scope and Applicability
This decision applies to all non-resident persons—both individuals and legal entities—who engage in economic activities or possess certain ties within the UAE. It is especially relevant for entities that are not ordinarily resident but have operations, assets, or other significant connections in the country. The decision provides the basis for tax authorities to evaluate and verify the residency status of such persons, thereby ensuring compliance with the provisions of the federal corporate tax law.
Key Criteria for Determining Non-Resident Connection
1. Physical Presence and Duration
The decision emphasizes the importance of the duration and nature of physical presence within the UAE. A person’s presence exceeding a specified period—determined by the relevant authorities—may establish a sufficient connection, subject to additional factors.
2. Economic and Business Activities
Engagement in substantive economic activities within the UAE, such as operating a business, holding assets, or having income-generating operations, constitutes a significant connection. The decision details the circumstances under which such activities influence residency status.
3. Ownership and Control
Ownership of property, shares, or other assets in the UAE, as well as control over business entities operating within the country, are recognized as indicators of a connection to the UAE.
4. Family and Personal Ties
Personal relationships, such as family residency or long-term residence, may also be considered when assessing the connection of a non-resident to the UAE.
Implications for Tax Compliance and Reporting
Taxpayers and their advisors should carefully evaluate their connections to the UAE in light of this decision. Establishing whether a person is a non-resident or resident has direct implications on the scope of tax obligations, filing requirements, and potential tax liabilities. The decision aims to facilitate consistent and fair application of corporate tax rules, reducing ambiguities and disputes.
References and Regulatory Framework
This decision is issued by the Council of Ministers and aligns with the overarching legal framework set forth by the Federal Tax Authority (FTA) and other relevant authorities. It is part of the UAE’s ongoing efforts to enhance transparency, compliance, and international cooperation in tax matters.
Conclusion
Cabinet Decision No. (35) of 2025 provides vital guidance for understanding the criteria that determine the connection of non-resident persons to the UAE for corporate tax purposes. Entities and individuals operating within the country should review these provisions carefully to ensure compliance and optimize their tax planning strategies. For further details and official interpretations, stakeholders are advised to consult the relevant authorities, notably the Federal Tax Authority (FTA) and the Ministry of Finance (MOF).