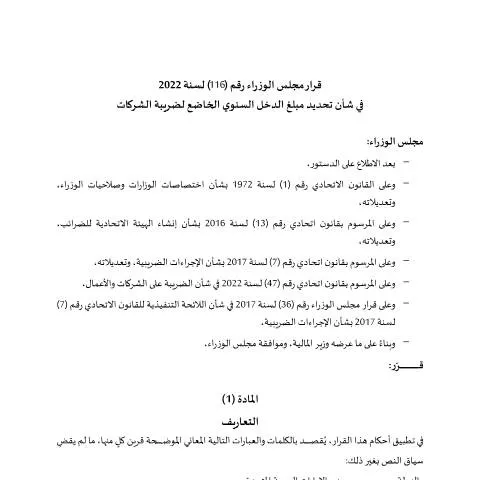
Navigating the Corporate Tax Income Threshold: Understanding the Ministerial Decision No. 116 of 2022
The introduction of the corporate tax in the UAE marks a pivotal shift in the economic landscape of the nation. The Ministerial Decision No. 116 of 2022, as part of the broader framework stipulated by the Federal Tax Authority (FTA), sets forth the annual income thresholds subject to corporate tax. This regulation is of utmost significance for businesses, as it dictates the financial obligations that companies must adhere to. Understanding this document is essential for compliance and strategic financial planning.
Who is Obligated to Submit This Form?
Not every entity is mandated to comply with the requirements outlined in the Ministerial Decision. This section elaborates on the profiles of businesses that must pay close attention to this regulation:
- Corporate Entities: All companies with a taxable income exceeding AED 375,000 are required to adhere to the corporate tax regulations.
- Free Zone Companies: Entities operating within designated free zones might have specific conditions based on their operational nature and income structure.
- Foreign Companies: Non-resident entities conducting business within the UAE must also assess their income against the established threshold.
It’s important to note certain exemptions. For instance, businesses whose taxable income does not exceed the specified threshold are not required to file.
A Deep Dive into the Regulatory Framework
The backdrop of Ministerial Decision No. 116 of 2022 is rooted in the UAE Constitution and its federal taxation laws. The foundation for corporate taxation was laid by the Federal Law No. 47 of 2022 on taxation of corporate income. The following table summarizes the key legislative components leading to the implementation of the corporate tax:
| Year | Legislation | Description |
|---|---|---|
| 2016 | Federal Law No. 13 | Initial framework for taxation laws in the UAE |
| 2017 | Federal Law No. 7 | Introduction of Value Added Tax (VAT) |
| 2022 | Federal Law No. 47 | Implementation of corporate tax regulations |
| 2022 | Ministerial Decision No. 116 | Specification of the income threshold for corporate tax |
As a result of these regulations, businesses must maintain accurate records of their income to ensure compliance with the new tax obligations.
Steps to Complete and Submit the Form
Filing for corporate tax under the provisions of Ministerial Decision No. 116 involves several meticulous steps. Familiarity with the submission process is crucial to avoid potential penalties:
- Gather Relevant Documentation: Ensure you have all necessary financial statements, tax identification numbers, and supporting documents that outline your income and expenses.
- Access the Online Portal: Navigate to the Federal Tax Authority's official website, where the e-filing system is in place for streamlined submissions.
- Complete the Form: Fill out the tax form accurately, paying special attention to the income declaration section. Any inaccuracies could lead to delayed processing or rejections.
- Review and Submit: After completing the form, conduct a thorough review of all entries before final submission.
- Receive Confirmation: Upon successful submission, ensure you receive an acknowledgment receipt, which serves as proof of your submission.
In case of online submission issues, businesses can opt for assistance through local tax offices or authorized personnel, ensuring they do not miss critical deadlines.
Common Pitfalls to Avoid When Filling the Form
The intricacies of the corporate tax submission can pose challenges. Here are essential tips to avoid common mistakes:
- Misunderstanding Income Categories: Ensure a clear understanding of what constitutes taxable income under the corporate tax framework.
- Neglecting Documentation: Failing to provide adequate financial records can result in complications during the assessment phase.
- Incorrect Calculations: Double-check all numerical entries to avoid discrepancies that could trigger audits.
- Ignoring Deadlines: Awareness of the submission timeline is critical. Late submissions may incur penalties as regulated by the FTA.
What If You Encounter Issues? Addressing Rejections and Missing Documents
In the event of a rejection or if there are missing documents, knowing the recourse available is crucial:
- Review the Rejection Notice: Carefully examine the reasons provided for the rejection or request for additional documentation.
- Rectify Errors: Make the necessary corrections or compile the required documents as specified in the notice.
- Resubmit Promptly: Submit the revised application or missing documents as soon as possible to avoid further complications.
- Consult with Professionals: If in doubt, seeking guidance from tax professionals can help clarify complex issues and ensure compliance.
Maintaining proactive communication with the FTA can also facilitate smoother resolutions to issues encountered during the filing process.
The Role of Technology in Streamlining the Submission Process
The UAE's commitment to digital efficiency is reflected in the electronic tax filing system employed by the Federal Tax Authority. This system not only enhances accessibility but also simplifies the submission process for businesses:
- Accessibility: The online platform allows for submissions from anywhere, reducing the need for physical visits to tax offices.
- Real-Time Updates: Businesses can track their submission status in real-time, ensuring they are informed of any processing updates.
- Record Management: Digital records are easier to manage, ensuring that all necessary documentation is readily available for future reference.
Understanding how to effectively utilize these technologies can greatly enhance compliance efforts and contribute to overall efficiency in tax reporting.
Conclusion: Planning for the Future under Corporate Tax Regulations
As businesses adapt to the corporate tax landscape in the UAE, the successful navigation of regulations such as the Ministerial Decision No. 116 of 2022 is paramount. By complying with these requirements and maintaining accurate records, businesses can not only fulfill their tax obligations but also position themselves strategically for growth in an evolving economic environment. Awareness and proactive management of tax responsibilities will undoubtedly be critical factors in the sustainability of business operations in the UAE.
Understanding the Corporate Tax Framework in the UAE
The introduction of corporate tax in the UAE through Cabinet Resolution No. (116) of 2022 marks a significant shift in the country's tax landscape, aligning it with global best practices. This resolution establishes a corporate tax rate of 9% on taxable income exceeding AED 375,000, with the intention of diversifying the economy away from oil dependency while ensuring compliance with international tax standards. This measure is designed to promote fairness in the tax system and encourage sustainable economic growth.
Under this framework, corporate entities are required to assess their taxable income accurately, as the determination of tax liability depends on the correct calculation of income subject to the corporate tax. Furthermore, maintaining meticulous financial records is essential not only for tax compliance but also for ensuring that businesses can leverage available deductions and exemptions.
Entities operating within the UAE must familiarize themselves with the tax laws, particularly the implications of the corporate tax, to ensure they remain compliant. The Federal Tax Authority (FTA) provides comprehensive guidelines and resources to assist businesses in understanding their obligations under this new tax regime, which are outlined further in the directive issued by the Cabinet and subsequently detailed in local emirate-based tax regulations.
Exemptions and Special Cases Under the Corporate Tax Regulation
One of the crucial aspects of Cabinet Resolution No. (116) of 2022 is the provision for specific exemptions and special cases that cater to various sectors and business types. Notably, certain business activities may be exempt from corporate tax, including those operating in free zones, provided they adhere to specific regulatory conditions. For instance, a business must engage exclusively in permitted activities defined by the respective free zone authorities to retain its tax exemption status.
Moreover, entities that operate under a qualifying investment regime or those engaged in specific sectors, such as education or healthcare, may also benefit from reduced rates or exemption from corporate tax. This nuanced approach allows the UAE to foster a business-friendly environment while still adhering to international commitments on tax transparency and fairness.
It is also vital for businesses to stay updated on any changes in the regulations that may affect their tax status. The FTA periodically reviews and updates its guidelines, providing clarity on which entities qualify for exemptions and under what circumstances. Engaging with a local tax consultant or legal advisor familiar with the UAE's corporate tax landscape can be invaluable for businesses seeking to navigate these complexities.
The Role of Digitalization in Corporate Tax Compliance
In line with the UAE's ambition to enhance digital transformation across all sectors, the corporate tax compliance process is heavily reliant on digital systems and platforms. The Federal Tax Authority has implemented an online portal that allows businesses to register for corporate tax, file tax returns, and make payments electronically. This streamlined approach not only enhances efficiency but also significantly reduces the administrative burden on businesses.
Through platforms such as u.ae and the respective emirate portals, businesses can access their tax information, submit necessary documents, and receive timely updates on their tax status. The integration of digital services facilitates real-time tracking and monitoring, enabling businesses to manage their tax obligations proactively.
Moreover, the UAE Pass, a unified digital identity, plays a pivotal role in ensuring secure and seamless access to government services, including tax-related services. By leveraging digital tools, businesses can ensure compliance with tax regulations while enhancing their overall operational efficiency. This digital-first approach exemplifies the UAE's commitment to fostering a conducive business environment and driving economic growth through innovation.