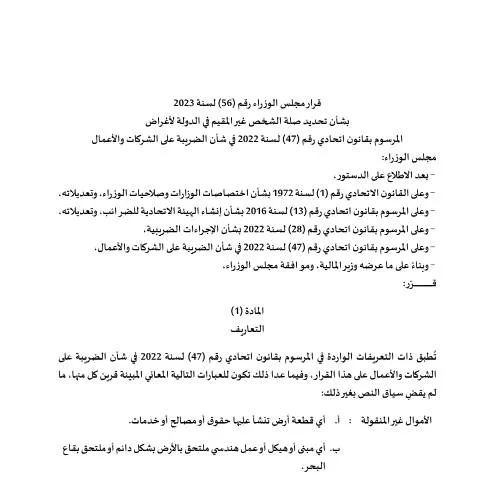
Overview of the Ministerial Decision No. (56) of 2023 on the Definition of the Connection of Non-Resident Persons for Corporate Tax Purposes in the UAE
The United Arab Emirates has issued a significant legislative update through Ministerial Decision No. (56) of 2023, which pertains to the criteria used to determine the connection of non-resident persons within the UAE for the purposes of federal corporate tax law. This decision aims to clarify the scope of tax obligations for entities and individuals who are not ordinarily resident in the country but may have taxable activities or income derived from the UAE.
Objective and Scope of the Decision
This decision is part of the UAE's broader efforts to enhance tax transparency and compliance, aligning with international standards and the country's commitment to implementing a robust federal corporate tax regime. It specifically addresses the criteria for establishing a taxable connection of non-resident persons, which is essential for determining tax liability under Federal Decree-Law No. (47) of 2022 concerning corporate taxation.
The scope of this decision covers various categories of non-resident persons, including foreign companies, partnerships, and individual entrepreneurs, who conduct economic activities or generate income within the UAE. It provides a framework for tax authorities to assess whether such persons have a sufficient connection to the UAE to be subject to corporate tax obligations.
Main Provisions and Criteria for Connection
The decision delineates specific factors that establish a connection between non-resident persons and the UAE. These include, but are not limited to:
- Presence of a Permanent Establishment: The existence of a fixed place of business through which the non-resident conducts its activities in the UAE.
- Income-Generating Activities: Engaging in activities that produce income within the UAE, such as sales, services, or other commercial operations.
- Ownership or Control of Assets: Holding assets, property, or rights within the country that are used for business purposes.
- Significant Economic Interactions: Regular transactions or contractual relationships with UAE-based entities or individuals.
The decision emphasizes that the determination of connection will be based on a comprehensive assessment of these factors, considering the specific circumstances of each case.
Implications for Non-Resident Taxpayers
Non-resident persons who are deemed to have a connection under this decision will be subject to UAE corporate tax on their income derived from activities within the country. This includes income from sales, services, or other commercial engagements that meet the connection criteria.
It is crucial for non-resident entities and individuals to review their operational structures and transactional activities to assess whether they establish a taxable connection under the new provisions. Proper documentation and compliance measures are essential to demonstrate the nature and extent of their activities in the UAE.
Compliance and Next Steps
Taxpayers and their advisors should stay informed about the detailed criteria outlined in the decision and ensure their activities are aligned with UAE tax laws. The Federal Tax Authority (FTA) provides guidance and support for entities seeking to understand their obligations under the new framework.
It is advisable for non-resident persons conducting business in the UAE to consult with tax professionals and review their operational arrangements to determine their potential tax liabilities. Maintaining accurate records of activities, contracts, and assets will facilitate compliance and support any future tax assessments.
Conclusion
The issuance of Ministerial Decision No. (56) of 2023 marks a significant step in refining the UAE's corporate tax landscape, especially concerning non-resident persons. By clearly defining the connection criteria, the decision aims to foster transparency, fair taxation, and compliance within the country's evolving fiscal framework. Non-resident taxpayers should proactively evaluate their operations in light of these new provisions to ensure adherence to UAE tax regulations and avoid potential penalties.