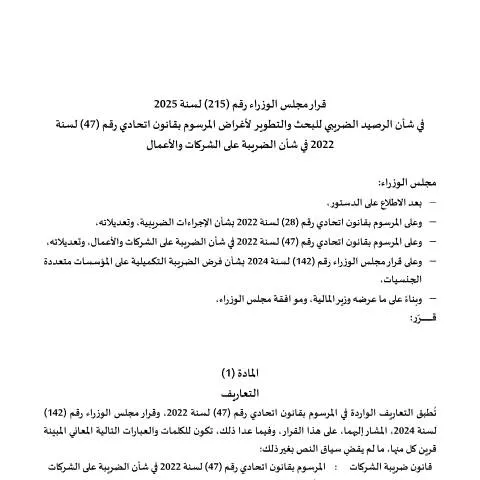
Understanding the Research and Development Tax Credit: Implications of Cabinet Decision No. 215 of 2025
The Cabinet Decision No. 215 of 2025 marks a crucial step in fostering innovation within the United Arab Emirates (UAE) by providing a structured framework for claiming tax credits related to research and development (R&D) activities. This decision is aligned with the Federal Decree-Law No. 47 of 2022 on Corporate Tax, setting out the essential definitions and stipulations necessary for eligible entities to benefit from these credits.
The Regulatory Background and Context
To appreciate the significance of Cabinet Decision No. 215 of 2025, it is essential to understand it within the broader legislative framework established by the UAE government. The decision builds on previous laws, including:
- Federal Decree-Law No. 28 of 2022 concerning tax procedures.
- Federal Decree-Law No. 47 of 2022 regarding corporate tax.
- Cabinet Decision No. 142 of 2024 on supplementary taxes applicable to multinational entities.
These laws collectively create a robust tax infrastructure aimed at enhancing economic diversification and encouraging private sector innovation. By facilitating R&D tax credits, the UAE government aims to position the nation as a leader in technological advancement.
Key Definitions and Concepts
Understanding the terminology used in Cabinet Decision No. 215 is vital for entities seeking to navigate the application process. Below is a summary of essential terms:
| Term | Definition |
|---|---|
| Qualified Entity (الكيان المؤهل) | Any legal person established and recognized under UAE laws that engages in eligible R&D activities. |
| Eligible R&D Expenses (نفقات البحث والتطوير المؤهلة) | Expenses that meet the criteria set forth in this decision for qualifying research activities. |
| R&D Tax Credit (الرصيد الضريبي للبحث والتطوير) | The tax credit a qualified entity can claim based on eligible R&D expenses. |
Application Timeline and Key Dates
Entities should be cognizant of the specific timelines associated with filing for R&D tax credits:
- Eligibility Assessment: Entities must assess their activities to ensure they meet the qualifications stipulated by the decision.
- Documentation Preparation: Prepare all necessary documentation, including proof of eligible expenses and project descriptions.
- Submission Period: The application for the tax credit must be submitted within the timeframe set by the UAE Federal Tax Authority (FTA).
- Review Process: The FTA will review submissions, typically within a specified period, to ensure compliance with the regulations.
Understanding these timelines is essential for successful application and compliance.
Navigating the Application Process
Filing for the R&D tax credit under Cabinet Decision No. 215 requires a methodical approach. Here’s a step-by-step guide:
- Determine Eligibility: Ensure the entity meets the necessary criteria, including having a minimum number of employees engaged in R&D activities.
- Collect Required Documentation: Documentation may include project outlines, expense reports, and evidence of compliance with pre-approval requirements.
- Submit Application: Utilize the designated online portals provided by the FTA. Ensure that the application includes correct reference numbers and is complete to avoid delays.
- Await Response: After submission, anticipate feedback from the FTA. If additional information is needed, be prepared to respond quickly.
Addressing Potential Challenges: Refusals and Errors
In the event of a refusal or a perceived error in processing your application, it is crucial to recognize the steps available:
- Review the Feedback: Carefully analyze the reasons for the refusal provided by the FTA. This will help identify any corrective action required.
- Seek Clarification: Directly contact the FTA for clarification if necessary.
- Resubmit Corrected Applications: If errors were identified in the initial submission, promptly prepare a corrected application and resubmit it within the designated timeframe.
Moreover, entities should maintain detailed records of all communications and submissions to support their case should disputes arise.
The Significance of Compliance and Ongoing Obligations
Once the credit has been granted, it is vital for entities to understand their ongoing compliance obligations. These include:
- Maintaining accurate and comprehensive records of all R&D activities and associated expenses.
- Ensuring that all future R&D projects comply with criteria set out in the Cabinet Decision and any subsequent amendments.
- Engaging with the UAE’s regulatory bodies to stay informed about any changes to tax regulations that may affect eligibility.
Failure to comply with these requirements can lead to penalties or revocation of credits, emphasizing the importance of vigilance and due diligence.
Real-World Implications and Benefits of the R&D Tax Credit
Claiming the R&D tax credit can significantly impact an organization’s financial health by reducing tax liabilities. Companies that successfully navigate the application process can:
- Free up capital for further innovation and development.
- Enhance their competitive edge in the market through increased investment in R&D.
- Align with the UAE government's vision for economic diversification and technological advancement.
Ultimately, the strategic utilization of these credits can facilitate not only financial benefits for individual organizations but also contribute to the broader economic landscape of the UAE.
The Broader Chain of Procedures: Interrelation with Other Tax Measures
The R&D tax credit does not exist in isolation; it is part of a comprehensive tax framework within the UAE. Understanding how this credit interacts with other tax measures is crucial:
- Corporate Tax Regulations: The R&D tax credit is inherently linked to the broader corporate tax obligations set forth in Federal Decree-Law No. 47. Entities must ensure that their claims align with their overall tax strategy.
- Supplementary Taxes: Multinational entities must account for any supplementary taxes that may apply, as outlined in Cabinet Decision No. 142.
- Ongoing Consultations: Regular consultation with tax advisors familiar with UAE tax laws can provide entities with insight into optimizing their tax positions.
Final Considerations: Maximizing the Benefits of the R&D Tax Credit
To maximize the potential benefits of the R&D tax credit, entities should:
- Engage in proactive tax planning to align R&D activities with tax credit opportunities.
- Invest in training for staff involved in R&D project management to ensure compliance and effective documentation.
- Stay informed about the latest developments in tax legislation to adapt strategies as needed.
Through careful navigation of the tax landscape and strategic planning, entities can leverage the R&D tax credit as a tool for sustainable growth and innovation.
Understanding the Implications of Cabinet Decision No. (215) of 2025 on Tax Credits for Research and Development
The Cabinet Decision No. (215) of 2025, issued by the UAE government, emphasizes the crucial role of innovation and development in fostering a competitive economy. This legislation provides a framework for tax credits aimed at stimulating research and development (R&D) within various sectors. Understanding the implications of this decision is essential for both public entities and private sector organizations engaged in R&D activities.
One of the primary objectives of this decision is to encourage more investment in innovation by providing financial relief through tax credits. Companies that engage in eligible R&D projects can benefit from a significant reduction in taxable income, effectively lowering their overall tax burden. This initiative aligns with the UAE's long-term vision of becoming a global leader in innovation, as outlined in the national agenda.
Companies must familiarize themselves with the eligibility criteria for projects that can benefit from these tax credits. The types of research deemed eligible include, but are not limited to, technological advancements, product and process innovation, and any systematic investigation that aims to improve existing systems or create new functionalities. Applicants must also ensure that their projects meet the stipulated guidelines set forth by the Federal Tax Authority (FTA) to qualify for the credit.
Application Process for Tax Credits under Cabinet Decision No. (215)
Applying for the tax credits established by Cabinet Decision No. (215) involves a structured process that necessitates thorough documentation and adherence to specific guidelines. Organizations seeking to take advantage of these benefits must initially register with the Federal Tax Authority using their Emirates ID or UAE Pass. The application process can be initiated through the FTA's official website, which provides detailed instructions and access to required forms.
Once registered, applicants must compile comprehensive documentation to demonstrate their R&D activities. This includes project proposals, detailed budgets, timelines, and evidence of expenditures directly associated with the research activities. Additionally, companies must include any relevant technical reports or publications that showcase the outcomes of their R&D efforts.
It is essential to submit applications within the specified timeframe to ensure consideration for the tax credits. Furthermore, organizations should be prepared for potential audits from the FTA, as they may seek to verify the authenticity of the R&D claims made by applicants. Organizations are encouraged to maintain meticulous records throughout the research process to facilitate this verification.
Potential Challenges and Best Practices for Claiming R&D Tax Credits
While the Cabinet Decision No. (215) provides a valuable opportunity for companies involved in R&D, various challenges may arise during the application process. One common issue is the difficulty in adequately tracking and documenting R&D expenditures. Organizations often struggle to differentiate between eligible and non-eligible costs, leading to potential complications when filing for tax credits.
To mitigate these challenges, companies should establish a robust internal framework for monitoring R&D activities and expenditures. Implementing a dedicated project management system can help categorize expenses accurately and ensure compliance with FTA guidelines. Regular training sessions for staff involved in R&D processes can also enhance awareness of eligibility criteria and documentation requirements.
Moreover, engaging with tax consultants who specialize in R&D tax credits can provide valuable insights and support throughout the application process. These professionals can assist companies in preparing documentation, ensuring compliance, and maximizing their potential benefits under the Cabinet Decision No. (215).
Ultimately, by being proactive and organized, companies can navigate the complexities of claiming R&D tax credits more effectively, positioning themselves to take full advantage of the incentives offered by the UAE government.