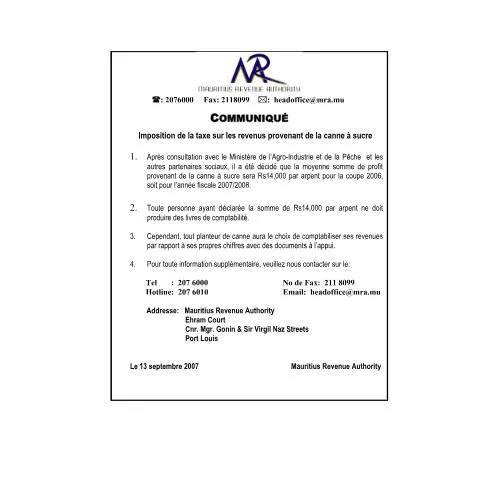
Official Notice: Imposition of Tax on Income from Sugar Cane in Mauritius
On September 13, 2007, the Mauritius Revenue Authority (MRA) issued a formal circular regarding the taxation of income derived from sugar cane cultivation for the fiscal year 2007/2008. This notice provides essential guidance for sugar cane growers and other stakeholders involved in the industry, outlining the applicable profit thresholds, reporting obligations, and options available for declaring income. It is crucial for all relevant parties to understand the provisions laid out in this communication to ensure compliance with the tax regulations applicable to their activities.
Context and Scope of the Notice
The circular was issued following consultations with the Ministry of Agro-Industry and Fisheries, as well as other social partners involved in the sugar industry. The primary objective is to establish a clear framework for the taxation of profits from sugar cane cultivation, specifically targeting the income generated during the 2006 harvest, which corresponds to the fiscal year 2007/2008. The notice aims to streamline tax reporting procedures, provide clarity on profit estimation, and facilitate compliance among sugar cane growers in Mauritius.
Who Is Affected by This Circular?
This notice directly concerns all sugar cane growers operating within Mauritius who earn income from their cultivation activities during the specified period. It applies to both small-scale farmers and larger plantation owners, provided their income from sugar cane exceeds the threshold set by the authorities. Additionally, entities involved in the processing and sale of sugar cane are indirectly impacted, especially if they engage in income declaration related to cane cultivation.
Key Provisions and Requirements
Profit Estimation and Declaration
The circular establishes that the average profit per arpent (a traditional land measurement unit used in Mauritius) from sugar cane for the 2006 harvest will be Rs14,000. This figure is applicable for the assessment of income during the fiscal year 2007/2008. Growers who declare this amount as their profit are not required to maintain detailed accounting books, simplifying their compliance obligations.
Options for Record-Keeping and Income Verification
- Growers who prefer to keep detailed records may do so by documenting their actual revenues and supporting them with relevant documents. This approach allows for a more precise declaration of income, based on their own figures.
- Alternatively, growers can opt to declare a standardized profit estimate of Rs14,000 per arpent without maintaining extensive books, provided they meet the conditions set forth by the tax authorities.
Additional Information and Assistance
For further guidance or clarification regarding the tax obligations related to sugar cane income, stakeholders are encouraged to contact the Mauritius Revenue Authority through the following channels:
- Telephone: 207 6000
- Fax: 211 8099
- Email: [email protected]
- Hotline: 207 6010
The MRA's office is located at Ehram Court, at the corner of Mgr. Gonin and Sir Virgil Naz Streets in Port Louis. Citizens are advised to seek assistance proactively to ensure full compliance with the applicable tax regulations and to clarify any uncertainties regarding their specific circumstances.
Legal and Administrative References
This circular is issued in accordance with the legal framework governing tax administration in Mauritius, notably under the authority of the Mauritius Revenue Authority Act and related fiscal laws. It reflects the government’s ongoing efforts to promote transparency, ease of compliance, and effective tax collection within the agricultural sector, especially in industries with traditional significance such as sugar cane cultivation.
Conclusion
In summary, the Mauritius Revenue Authority’s notice on the taxation of income from sugar cane provides a clear, simplified pathway for growers to declare their profits for the 2006 harvest period. Whether opting for a standard estimate or detailed record-keeping, it is vital for all affected parties to adhere to the outlined procedures to ensure compliance and avoid potential penalties. The MRA remains committed to supporting taxpayers through accessible communication channels and promoting the orderly collection of revenue essential for national development.