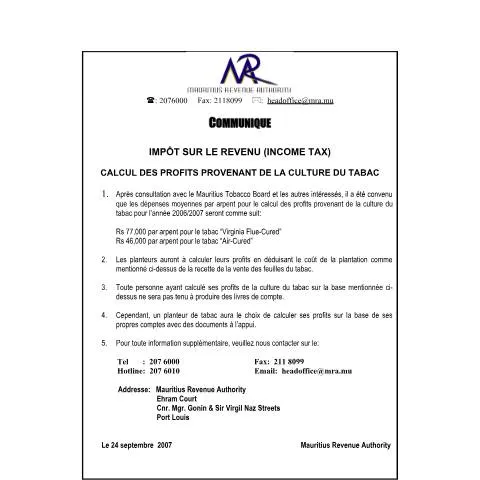
Official Notice on Calculating Profits from Tobacco Cultivation in Mauritius
This official communication from the Mauritius Revenue Authority (MRA), dated 24 September 2007, provides essential guidance for tobacco growers regarding the calculation of taxable profits derived from tobacco cultivation for the fiscal year 2006/2007. It aims to clarify the methods permitted under the current legal framework and to ensure compliance with income tax regulations related to agricultural income.
Scope and Purpose of the Notice
The primary objective of this notice is to inform tobacco planters about the accepted methods for calculating their profits for income tax purposes. It delineates the standardized expense deductions based on the type of tobacco cultivated and offers flexibility for growers to use their own accounting records if they prefer. This measure simplifies the tax reporting process for small-scale farmers and promotes transparency in the agricultural sector.
Applicable Tobacco Varieties and Expense Deductions
Following consultations with the Mauritius Tobacco Board and other stakeholders, the MRA has established average expense allowances per arpent (a traditional land measurement unit used in Mauritius) for the 2006/2007 period:
- Rs 77,000 per arpent for Virginia Flue-Cured tobacco
- Rs 46,000 per arpent for Air-Cured tobacco
These figures are intended to serve as standard deductions representing the average costs incurred in planting, maintaining, and harvesting the respective tobacco varieties. The expense allowances are designed to streamline the calculation process and reduce administrative burdens for farmers.
Calculation of Profits and Tax Obligations
According to the notice, tobacco growers should determine their profits by subtracting the prescribed expenses from the total revenue obtained from selling tobacco leaves. Specifically:
- Calculate the gross income from tobacco sales.
- Deduct the standard expense amount per arpent based on the variety cultivated.
- The resulting figure represents the taxable profit for income tax purposes.
Importantly, the notice indicates that farmers who adopt this standardized method are not required to maintain detailed accounting books, simplifying compliance for small-scale or informal growers.
Option for Self-Prepared Accounts
While the standard expense deductions are encouraged, the notice grants flexibility to tobacco planters. Farmers may choose to calculate their profits based on their own detailed accounts, provided they can substantiate their figures with appropriate documentation. This option allows for more precise profit calculation, particularly for larger or more organized growers who maintain comprehensive financial records.
Implications for Tobacco Growers and Tax Compliance
This guidance aims to facilitate compliance with income tax obligations by providing clear, standardized procedures for profit calculation. It reduces the administrative burden on small farmers while allowing larger producers to opt for detailed accounting if desired. Ultimately, the measure promotes transparency and fairness in the taxation of agricultural income related to tobacco cultivation.
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
Contact and Further Information
For additional guidance or questions concerning the calculation of profits from tobacco cultivation, tobacco growers are encouraged to contact the Mauritius Revenue Authority through the following channels:
- Telephone: 207 6000
- Fax: 211 8099
- Hotline: 207 6010
- Email: [email protected]
The MRA’s office is located at Ehram Court, at the corner of Mgr. Gonin and Sir Virgil Naz Streets, Port Louis. This communication underscores the authority’s commitment to supporting agricultural taxpayers through clear, accessible procedures aligned with legal requirements.