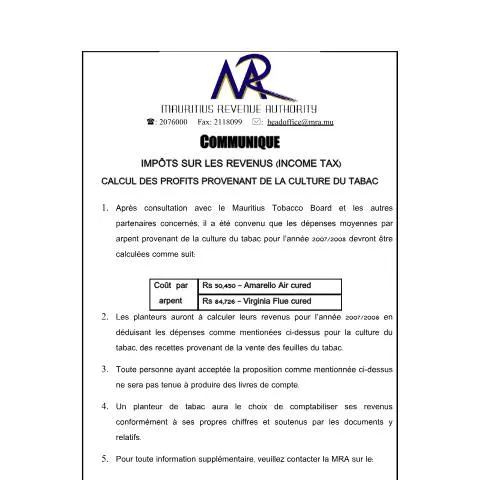
Official Notice on Calculating Profits from Tobacco Cultivation in Mauritius
Introduction and Context
This official communication issued by the Mauritius Revenue Authority (MRA) on September 17, 2008, provides guidance to tobacco growers regarding the calculation of taxable profits derived from tobacco cultivation for the fiscal year 2007/2008. The notice aims to clarify the procedures, accepted expense deductions, and the implications for tax reporting, following consultations with relevant stakeholders including the Mauritius Tobacco Board and other involved partners.
Scope and Purpose
The primary objective of this notice is to standardize the method for tobacco growers to calculate their net income from tobacco sales for the specified year. By establishing a clear framework, the MRA seeks to facilitate compliance, streamline tax processes, and ensure equitable taxation based on actual cultivation costs. This guidance is applicable to all registered tobacco cultivators who intend to declare their income for tax purposes during the 2007/2008 fiscal year.
Calculation of Expenses and Revenue
According to the notice, the calculation involves deducting specific, predefined cultivation expenses from gross income obtained through the sale of tobacco leaves. The expenses are determined based on the type of tobacco cultivated and are expressed per arpent, a traditional Mauritian land measurement unit.
- Amarello Air Cured Tobacco: Rs 50,450 per arpent
- Virginia Flue Cured Tobacco: Rs 84,726 per arpent
Growers are advised to compute their gross revenue from the sale of tobacco leaves and then subtract these standardized expenses to arrive at their taxable profit.
Tax Filing and Record-Keeping
One significant aspect of this guidance is the flexibility granted to tobacco cultivators regarding record-keeping. Growers who accept the prescribed expense calculations as outlined above are not required to produce detailed accounting books during tax assessments, simplifying their compliance process. However, those who prefer to use their own figures must support their calculations with relevant documentation, including receipts, invoices, and other supporting evidence.
This approach allows farmers to choose the method most suitable to their record-keeping capacities and ensures transparency and accuracy in reporting.
Implications for Tobacco Growers
All registered tobacco farmers are encouraged to adhere to this calculation method for the 2007/2008 fiscal year. The decision to accept the prescribed expenses means that they will not be obliged to submit detailed books of account, easing administrative burdens. Conversely, those opting for self-calculated figures must ensure proper documentation to substantiate their reported income and expenses.
This guidance aims to promote a fair and consistent approach to taxation while accommodating different levels of record-keeping sophistication among growers.
Contact and Further Information
For additional guidance or clarification regarding the calculation procedures or related tax obligations, tobacco growers and interested parties are advised to contact the Mauritius Revenue Authority. The contact details are as follows:
- Telephone: 207 6000
- Fax: 211 8099
- Email: [email protected]
The MRA office is located at Ehram Court, Corner Mgr Gonin Sir Virgil Naz Streets, Port Louis. Citizens are encouraged to utilize the agency’s digital services and online portals for efficient communication and submission of relevant information.
Legal and Administrative References
This notice is issued under the authority of the Mauritius Revenue Authority in accordance with applicable tax laws and regulations. It reflects the collaborative effort between the MRA, the Mauritius Tobacco Board, and other stakeholders to ensure a clear and practical approach to taxation of tobacco cultivation income for the specified year.
Conclusion
By providing a standardized method for calculating profits from tobacco cultivation, the Mauritius Revenue Authority aims to streamline tax compliance and promote transparency among tobacco growers. The guidance emphasizes the importance of accurate reporting, whether through accepted standardized expenses or supported self-calculations, to uphold the integrity of the tax system and support sustainable agricultural practices in Mauritius.