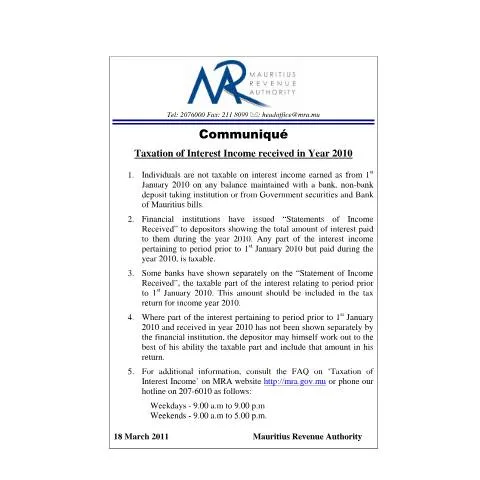
Overview of the Taxation of Interest Income for the Year 2010 in Mauritius
On 18 March 2011, the Mauritius Revenue Authority (MRA) issued an official notice detailing the tax treatment of interest income received during the fiscal year 2010. This communication aims to clarify the applicable rules, the responsibilities of depositors and financial institutions, and the procedures for reporting interest income in accordance with Mauritian tax law.
Context and Scope of the Notice
The notice primarily addresses the changes introduced in the taxation of interest income starting from 1 January 2010. It marks a significant shift in the tax policy, whereby individuals are no longer taxed on interest earned from bank deposits, non-bank deposit-taking institutions, government securities, and Bank of Mauritius bills from that date onward. This policy change aims to encourage savings and investment by reducing the tax burden on interest income for individual depositors.
However, the notice emphasizes that interest accrued prior to 1 January 2010 remains taxable, and the relevant income received during the year 2010 must be correctly reported. The communication also highlights the responsibilities of financial institutions in providing detailed statements to depositors, which are essential for accurate tax reporting and compliance.
Who Is Affected by These Changes?
This notice is relevant primarily to individual depositors who received interest income during the year 2010, as well as to the financial institutions that issued statements of income received. It is essential for depositors to review their statements carefully to determine the taxable portion of their interest income, especially when interest pertains to periods before 1 January 2010.
Furthermore, financial institutions are required to issue detailed statements that distinguish between interest accrued before and after the start of the new tax regime. These documents serve as vital references for depositors when preparing their tax returns.
Key Points for Taxpayers and Financial Institutions
- Interest earned from 1 January 2010 onwards is not subject to tax, regardless of the amount or the type of deposit or security.
- Interest paid during 2010 that relates to periods prior to 1 January 2010 remains taxable and must be declared.
- Statements of Income Received issued by banks and financial institutions should specify the taxable portion of interest, especially when interest for periods before 2010 is involved.
- If the statement does not clearly separate the taxable interest, depositors are advised to estimate the taxable amount to the best of their ability and include it in their tax return.
Procedures for Reporting Interest Income
Depositors must include the taxable interest amount in their annual income tax return for the year 2010. The Mauritius Revenue Authority recommends reviewing the Statement of Income Received issued by the financial institution to identify the relevant figures.
In cases where the statement does not explicitly distinguish the taxable interest, taxpayers are encouraged to perform a reasonable calculation based on available information. This ensures compliance and avoids potential penalties for underreporting.
Additional Resources and Support
For further guidance, depositors and financial institutions can consult the FAQ section on the Mauritius Revenue Authority’s official website at http://mra.gov.mu. The FAQ provides detailed explanations on the taxation of interest income and related procedures.
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
Additionally, the MRA hotline is available for inquiries and assistance, operating on weekdays from 9:00 a.m. to 9:00 p.m., and on weekends from 9:00 a.m. to 5:00 p.m. The contact number is 207-6010.
Conclusion
This official notice from the Mauritius Revenue Authority clarifies the tax treatment of interest income received during the fiscal year 2010, emphasizing the importance of accurate reporting and compliance. While interest earned from 1 January 2010 is exempt from tax, depositors must remain vigilant in identifying and declaring the taxable interest related to periods prior to this date, as reflected in their financial statements. By adhering to these guidelines, taxpayers can ensure proper compliance with Mauritian tax law and avoid potential penalties.