Navigating the Transfer Pricing Disclosure Form: A Comprehensive Guide
In the intricate landscape of corporate governance and taxation in Sri Lanka, the Transfer Pricing Disclosure Form (Asmt_TPDF_01_E) emerges as a crucial document for both resident and non-resident entities engaged in cross-border transactions. As stipulated by the Inland Revenue Act No. 24 of 2017, this form must be filled out meticulously to ensure compliance with local tax regulations. Its importance cannot be understated, as it plays a significant role in maintaining transparency and integrity in pricing mechanisms among associated enterprises.
The Context of Transfer Pricing in Sri Lanka
Transfer pricing refers to the pricing of transactions between related entities, particularly when goods, services, or intangible assets are exchanged. In a globalized economy, where companies frequently engage in international trade, Sri Lanka has implemented stringent regulations to prevent tax avoidance through manipulative pricing practices.
The introduction of the Transfer Pricing Disclosure Form serves not only as a tool for revenue authorities to assess compliance but also as a means for businesses to document their adherence to the arm's length principle. This principle dictates that the pricing for transactions between related parties should mirror that of transactions between unrelated entities. By filling out this form, companies provide the tax authorities with essential information that facilitates accurate tax assessments.
Timeline for Submission and Official Notification
Understanding the timeline associated with the Transfer Pricing Disclosure Form is vital for compliance. The year of assessment for which this form is applicable is 2021/2022, following regulations outlined in Extraordinary Gazette Notification No. 2217/7 dated March 2, 2021. The form must be submitted by a specified deadline, typically aligned with the broader tax filing schedule established by the Department of Inland Revenue (DIR).
Entities should note that failure to submit this form on time may result in penalties or increased scrutiny from tax authorities. The consequences of late submission can range from financial penalties to potential audits, which can be both resource-intensive and time-consuming.
Understanding the Structure of the Transfer Pricing Disclosure Form
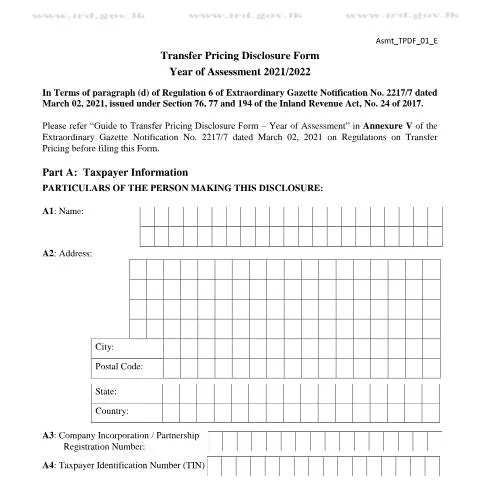
The Transfer Pricing Disclosure Form is structured into various sections, each designed to capture specific data regarding the taxpayer and their international transactions. Below, we provide a detailed overview of the form's components:
Part A: Taxpayer Information
- Name: The full legal name of the taxpayer or entity making the disclosure.
- Address: The registered address of the taxpayer, including city, postal code, and country.
- Company Incorporation/Partnership Registration Number: This unique identifier is crucial for establishing the legal status of the entity.
- Taxpayer Identification Number (TIN): This identifier is issued by the Department of Inland Revenue and is essential for all tax-related documentation.
- Contact Information: Including telephone number, email address, and web address, to facilitate communication with tax authorities.
Part B: Transactions with Associated Enterprises
This section focuses on the specifics of the transactions conducted with associated enterprises, requiring detailed disclosures that include:
- Transaction Item: Description of the transaction conducted.
- Associated Enterprise (AE) Details: Identification of the other party involved in the transaction, along with their TIN.
- Transfer Pricing Methodology: The approach used for determining the arm's length price.
- Amount of Transaction (in LKR): Accurately reporting the monetary value of transactions in Sri Lankan Rupees.
- Profit Level Indicator: Identification of indicators used to measure profitability in relation to the transaction.
Practical Considerations for Accurate Submission
Completing the Transfer Pricing Disclosure Form demands careful consideration of several factors:
Documentation and Evidence
To support the disclosures made in the form, businesses must retain thorough documentation that justifies their pricing strategies. This includes:
- Contracts and agreements pertaining to the transactions.
- Financial statements for the entities involved.
- Market analysis reports that provide context for pricing decisions.
- Comparability analyses demonstrating adherence to the arm's length principle.
Filing Process and Where to Submit
Once completed, the Transfer Pricing Disclosure Form must be submitted to the relevant tax authority in Sri Lanka, typically through the online portal managed by the Inland Revenue Department or via physical submission if required. It's essential for entities to retain a copy of the submitted form along with any acknowledgment received from the authorities as proof of compliance.
Consequences of Inaccuracies and Non-Compliance
Accuracy in the Transfer Pricing Disclosure Form is paramount. Inaccuracies or omissions can lead to severe ramifications, including:
- Financial Penalties: Fines may be imposed for incorrect disclosures or delays in submission.
- Increased Audit Risk: Non-compliance may trigger audits, leading to further examination of the taxpayer's financial activities.
- Legal Consequences: Persistent non-compliance could lead to legal action under the Inland Revenue Act.
Special Circumstances: Non-Resident Entities and Complex Situations
For non-resident companies or entities that have more intricate operational structures, the Transfer Pricing Disclosure Form holds additional considerations. Non-residents must be more vigilant in their disclosures, ensuring that they provide accurate information regarding:
- Cross-border transactions that might be subject to different jurisdictions' tax laws.
- The nature of associated enterprises, particularly if they are based in jurisdictions with differing tax obligations.
Moreover, companies should prepare for potential inquiries from the Inland Revenue Department regarding their pricing practices and must be ready to present comprehensive documentation to substantiate their claims.
The Role of Professional Advisors
Given the complexities of transfer pricing regulations, many companies opt to engage professional advisors or legal counsel specializing in tax law. These experts can assist in a variety of ways:
- Providing guidance on compliance requirements and best practices.
- Assisting in the preparation of documentation and analyses.
- Representing clients during audits or inquiries from tax authorities.
Working closely with advisors ensures not only compliance but also aids in developing robust strategies to mitigate tax risks associated with transfer pricing.
Final Thoughts on the Transfer Pricing Disclosure Form
The Transfer Pricing Disclosure Form (Asmt_TPDF_01_E) is more than just a bureaucratic requirement; it is a critical instrument for ensuring fairness in the taxation of multinational enterprises operating within Sri Lanka. By grasping the nuances of this form, businesses can navigate the complexities of compliance, thereby shielding themselves from potential penalties and fostering a transparent relationship with tax authorities.
As industries evolve and global trade continues to expand, staying abreast of regulatory changes related to transfer pricing will be essential. Engaging with the nuances of forms like Asmt_TPDF_01_E not only enhances compliance but also supports sustainable business operations in an ever-changing economic environment.
Understanding Transfer Pricing Regulations in Sri Lanka
Transfer pricing in Sri Lanka is governed by both local tax legislation and international standards outlined by the Organisation for Economic Co-operation and Development (OECD). The primary aim is to ensure that transactions between related parties are conducted at arm's length, thereby reflecting fair market conditions. The Inland Revenue Department (IRD) mandates that companies adhere to these regulations to maintain fairness in taxation and to prevent tax avoidance through profit shifting. Comprehensive documentation is essential not only for regulatory compliance but also for facilitating efficient audits and mitigating disputes with tax authorities.
The IRD has issued guidelines that detail the required documentation standards to substantiate the arm's length nature of intercompany transactions. These include financial analysis, economic studies, and pricing methodologies. Firms must evaluate their transfer pricing strategies based on the nature of their operations and the sectors they belong to, thereby ensuring they comply with both local laws and international best practices.
Key Aspects of the Transfer Pricing Disclosure Form - [Asmt_TPDF_01_E]
The Transfer Pricing Disclosure Form - [Asmt_TPDF_01_E] is a critical document for businesses engaged in related-party transactions. This form must be meticulously filled out to provide a comprehensive overview of the entity's transfer pricing practices and its compliance with the prevailing regulations. It serves as an essential tool for the IRD to assess the consistency of reported profits and the rationale behind pricing decisions. Failure to submit this form or inaccuracies within it can lead to significant penalties, including financial audits and adjustments to taxable income.
This form typically requires detailed information, such as:
- Entity Information: Basic information about the company, including its National Identity Card (NIC) number if applicable, registration number, and contact details.
- Financial Data: A comprehensive financial summary, including revenue from intercompany transactions, cost allocations, and profit margins, which must align with the reported financial statements.
- Analytical Information: A detailed analysis of the transfer pricing method employed, whether it is the Comparable Uncontrolled Price Method, Resale Price Method, Cost Plus Method, or other acceptable methods as defined by the IRD.
- List of Related Parties: Identification of all entities involved in related party transactions, including their respective jurisdictions and the nature of the relationships.
Additionally, the form requires a narrative explaining the rationale behind the pricing strategy used, which should directly correlate with the business model and operational structure of the entity. The IRD recommends that companies maintain robust transfer pricing documentation that can support their disclosures, thereby minimizing the risk of disputes and facilitating streamlined compliance processes.
Best Practices for Completing the Transfer Pricing Disclosure Form
Completing the Transfer Pricing Disclosure Form - [Asmt_TPDF_01_E] necessitates careful planning and execution. Here are some best practices to ensure accurate and compliant submissions:
- Early Preparation: Start the preparation process early in the fiscal year. This approach allows sufficient time to gather necessary data, conduct a thorough review, and amend any discrepancies before submission.
- Collaboration Across Departments: Engage finance, legal, and operational departments in the process. A collaborative approach ensures that all relevant information is captured accurately and that the different perspectives within the organization are reflected in the disclosure.
- Consult with Experts: It may be beneficial to consult with tax advisors or legal experts familiar with Sri Lankan transfer pricing regulations. Their expertise can provide valuable insights and help identify any potential pitfalls in the documentation process.
- Consistency with Financial Statements: Ensure that the data provided in the disclosure form is consistent with the company's financial statements. Any discrepancies could trigger scrutiny from tax authorities and lead to complications during audits.
- Regular Review and Updates: Transfer pricing policies should be reviewed regularly to adapt to changes in business operations, market conditions, or updates in legislation. Keeping documentation current demonstrates a proactive approach to compliance.
Ultimately, accurate and thorough completion of the Transfer Pricing Disclosure Form is essential for maintaining compliance with the IRD, protecting a company’s interests, and fostering sustainable business practices in Sri Lanka.