The Significance of the Tourist VAT Refund Scheme in Sri Lanka
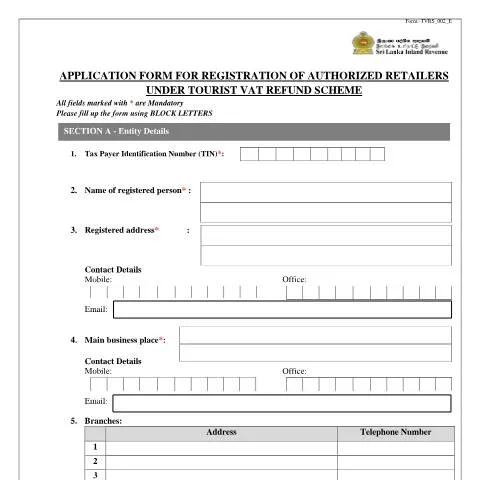
The Tourist VAT Refund Scheme (TVRS) plays a pivotal role in enhancing Sri Lanka's tourism landscape. Established under the guidance of the Department of Inland Revenue, this scheme aims to stimulate consumer spending among tourists and thereby amplify the local economy. The cornerstone of this initiative is the Application Form for Registration of Authorized Retailers under Tourist VAT Refund Scheme (TVRS_002), which serves as a gateway for businesses wishing to participate in the scheme.
A Deep Dive into the Application Process: From Preparation to Submission
The journey of registering as an authorized retailer begins with thorough preparation. Understanding the nuances of the TVRS_002 form is essential for both new and existing businesses. Here’s a detailed step-by-step outline:
- Gather Necessary Documentation: Ensure you have your Taxpayer Identification Number (TIN) and all relevant business documents ready.
- Fill Out the Form: Use block letters to clearly provide the required information, including business name, registered address, and contact details.
- Specify Main Business Place: It’s crucial to identify the primary location of your business operations.
- List Branches: If applicable, include details of any branches along with their contact numbers.
- Signature Requirement: The form must be signed by an authorized representative of the company, such as a Managing Director or Partner.
- Submit the Form: Choose your submission method—online via e-services or physically at designated offices.
Understanding the Form: Essential Sections and Requirements
Each section of the TVRS_002 form is designed to capture critical information about the applying retailer. Below is an overview of the form's key sections:
| Field | Description | Mandatory |
|---|---|---|
| Tax Payer Identification Number (TIN) | Your unique tax identification number. | Yes |
| Name of Registered Person | The official name of your business entity. | Yes |
| Registered Address | The physical address where your business is registered. | Yes |
| Main Business Place | Your primary business location. | Yes |
| Branches | Details of any other operating locations. | No (if applicable) |
| Contact Information | Mobile and office numbers, along with email addresses. | Yes |
Submission Channels: Navigating Your Options
Deciding on how to submit the TVRS_002 form is crucial. Businesses can choose either traditional paper submissions or digital avenues. Here’s a breakdown:
- Online Submission: Utilizing the ICTA's digital services through forms.gov.lk allows for quicker processing. However, internet access and familiarity with the system are prerequisites.
- Paper Submission: Businesses opting for this method should ensure all documents are accurately filled out and signed. Submission can typically be made at the local Department of Inland Revenue office.
What Happens After Submission? Tracking Your Application
Once the TVRS_002 form is submitted, businesses can expect certain actions from the Department of Inland Revenue:
- Processing Time: The average processing time for applications can vary, but it is recommended to follow up within two weeks if no communication is received.
- Verification: The department will review submitted information for accuracy and completeness. Any discrepancies may lead to delays.
- Approval Notification: Upon successful registration, businesses will receive an official notification, completing their enrollment in the TVRS.
Addressing Challenges: What If Your Application Is Rejected?
Despite careful preparation, there may be instances when an application is rejected. Understanding how to navigate this situation can save time and resources:
- Common Reasons for Rejection: Incomplete forms, incorrect details, and failure to meet eligibility criteria are frequent issues.
- Action Steps: If your application is rejected, promptly review the provided feedback. Rectify any mistakes or omissions, and reapply within the stipulated timeframe.
- Contacting Authorities: For clarification or assistance, reaching out to the Department of Inland Revenue directly is advisable.
Legal Framework: The Backbone of the Tourist VAT Refund Scheme
The legal basis for the Tourist VAT Refund Scheme is derived from English common law principles, which are integral to Sri Lankan law. This framework ensures that the scheme operates within a structured and legally sound environment:
- Interpretation Ordinance: This provides the guidelines for interpreting laws and regulations surrounding the scheme.
- Electronic Transaction Act: This law facilitates the use of digital forms and online submissions, enhancing accessibility for retail businesses.
Your Responsibilities as an Authorized Retailer
Once registered under the TVRS, retailers must adhere to specific obligations to maintain their status:
- Compliance with Regulations: Retailers are obligated to follow all legal requirements as outlined by the Department of Inland Revenue.
- Training Staff: Ensure that your staff is well-informed about VAT refund procedures to assist tourists effectively.
- Maintaining Records: Accurate record-keeping of all transactions is essential for audits and inspections.
Conclusion: The Path Forward for Authorized Retailers
Engaging in the Tourist VAT Refund Scheme through the TVRS_002 form presents significant opportunities for businesses in Sri Lanka. By following the outlined procedures and maintaining compliance, retailers can enhance their visibility and appeal to international visitors. This proactive approach not only contributes to the individual business’s growth but also to the broader economic vitality of Sri Lanka’s tourism sector.
Eligibility Criteria for Authorized Retailers
Becoming an authorized retailer under the Tourist VAT Refund Scheme (TVRS) in Sri Lanka entails meeting specific eligibility criteria set forth by the Department of Inland Revenue (DIR). The following conditions must be satisfied:
- The retailer must have a valid business registration and be registered for VAT in Sri Lanka.
- The retail establishment should prominently display a physical presence and should be located in areas frequented by tourists.
- The retailer must comply with all tax obligations, including timely submissions of VAT returns and payment of taxes.
- The business must be able to provide a range of goods that are eligible for VAT refunds, ensuring compliance with the list of qualifying products as detailed by DIR.
Additionally, the retailer must demonstrate an understanding of the VAT refund process and the associated responsibilities. This includes providing staff training on how to assist tourists in claiming their VAT refunds efficiently. Retailers should also maintain adequate inventory records to ensure transparency and accountability during VAT refund transactions.
Key Steps in the Application Process
The application process for becoming an authorized retailer under the TVRS involves several key steps, each requiring adherence to specific guidelines. Here's a breakdown:
- Gather Necessary Documentation: Collect all required documents, including your business registration certificate, VAT registration, and proof of location.
- Complete the Application Form: Fill out the Application Form for Registration of Authorized Retailers meticulously. Ensure all information is accurate, as discrepancies can lead to delays.
- Submit the Application: Submit your completed application along with supporting documents to the nearest office of the Department of Inland Revenue. Be sure to keep copies for your records.
- Await Approval: The DIR will review your application, which may take several weeks. During this period, they may conduct an inspection of your business premises to ensure compliance with the regulations of the TVRS.
- Receive Authorization: If approved, you will receive official notification of your status as an authorized retailer and will be issued a unique identification number for the scheme.
It's important to remain proactive during this process. Regularly follow up with the DIR if you have not received a response within the expected timeframe. Maintaining communication can help expedite your application.
Understanding Compliance and Monitoring Requirements
After obtaining authorization under the Tourist VAT Refund Scheme, retailers must adhere to a set of compliance and monitoring requirements to maintain their status. This includes:
- Regular Training for Staff: Conduct ongoing training sessions for employees to ensure they are well-versed in the VAT refund process, including how to handle the necessary documentation and assist customers efficiently.
- Maintain Accurate Records: Maintain comprehensive records of all VAT refund transactions, including receipts issued to tourists. This documentation is crucial for both customer service and tax audits.
- Annual Renewal of Authorization: The authorization to operate under the TVRS is not indefinite. Retailers must undergo a renewal process annually, which may require submitting updated documentation and proof of compliance with VAT regulations.
Moreover, the DIR conducts periodic audits of authorized retailers to ensure ongoing compliance. Retailers should be prepared to demonstrate adherence to all regulations and best practices, including maintaining a conducive environment for tourists and accurate handling of VAT refunds.
Failure to comply with the established guidelines may result in penalties, including the revocation of authorized retailer status. Therefore, it is essential to prioritise compliance and actively participate in any audits or inspections initiated by the Department of Inland Revenue.