Understanding the Solid Fuel Declaration Form for Electricity Generation in Ireland
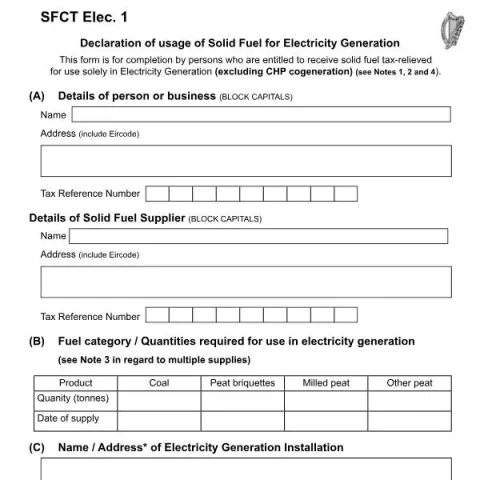
The Declaration of usage of Solid Fuel for Electricity Generation (Form SFCT Elec. 1) is an official document issued by the Revenue Commissioners, designed for operators of electricity generation installations who wish to claim tax relief on solid fuel used exclusively for generating electricity. This form is crucial for ensuring compliance with Irish tax regulations concerning the Solid Fuel Carbon Tax, particularly under Section 82(1)(a) of the Finance Act 2010.
Who Needs to Fill Out This Form?
This declaration must be completed by individuals or businesses that receive solid fuel tax-relieved for use solely in electricity generation, excluding combined heat and power (CHP) cogeneration. The form is intended for operators who purchase solid fuel—such as coal, peat briquettes, milled peat, or other peat products—for their electricity generation installations and want to benefit from the associated tax relief.
It is essential that the operator is authorized to declare that the fuel is used exclusively for electricity production. The form must be submitted to the solid fuel supplier before any tax-relieved supply occurs, ensuring the supplier can apply the relief at the point of sale.
How to Complete the Form
Part A: Operator and Supplier Details
Begin by providing the full name and address (including Eircode) of the person or business claiming the relief, along with their Tax Reference Number. Next, include the details of the solid fuel supplier—name, address, and tax reference number. Accurate information here is vital for proper processing and compliance.
Part B: Fuel Quantities and Supply Details
Specify the type and quantity of solid fuel supplied for electricity generation, including:
- Product category (e.g., coal, peat briquettes)
- Quantity in tonnes
- Date of supply
If multiple supplies are made within a calendar month, a single composite declaration may be used, provided supporting records are maintained to reconcile the supplies with the declaration.
Part C: Installation Details
Insert the name and address of the electricity generation installation. If multiple premises are involved, attach a separate list of addresses and note "list attached" opposite the "Premises Address" field.
Declaration and Signature
The operator must declare that the quantities of solid fuel specified are used solely for electricity generation at the specified installation. By signing, the operator confirms compliance with the relevant legal provisions and agrees to pay the full Solid Fuel Carbon Tax if the fuel is diverted for other uses.
The declaration must be signed by an authorized person within the business, with their name, designation, and date clearly indicated.
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
Important Submission and Record-Keeping Guidelines
The original completed form should be sent directly to the solid fuel supplier before any tax-relieved supply occurs. The operator must retain a copy for their records and be prepared to produce it during inspections by the Revenue Commissioners.
Operators are also advised to keep detailed records of all receipts and uses of solid fuel supplied tax-relieved, including copies of declarations, to demonstrate compliance and facilitate any future audits.
Additional Notes and Common Errors
- Timeliness: Ensure the form is submitted before the first tax-relieved supply; late submissions may result in the application of full tax at the point of sale.
- Completeness: All sections must be filled out accurately; incomplete forms can delay processing or lead to disqualification from relief.
- Multiple Supplies: For multiple supplies within a month, a single declaration can be used if records are maintained, but each supply must be clearly documented.
- Use in CHP Plants: This form does not apply to fuel used in CHP plants, which are subject to separate relief schemes.
Conclusion
The SFCT Elec. 1 declaration form is a key document for operators seeking to benefit from the Irish Solid Fuel Carbon Tax relief for electricity generation. Proper completion, timely submission, and diligent record-keeping are essential to ensure compliance with Irish tax law and to avoid penalties or disqualification from relief benefits.