Understanding the Solid Fuel Carbon Tax (SFCT) Return & Declaration (Form SFCT1) in Ireland
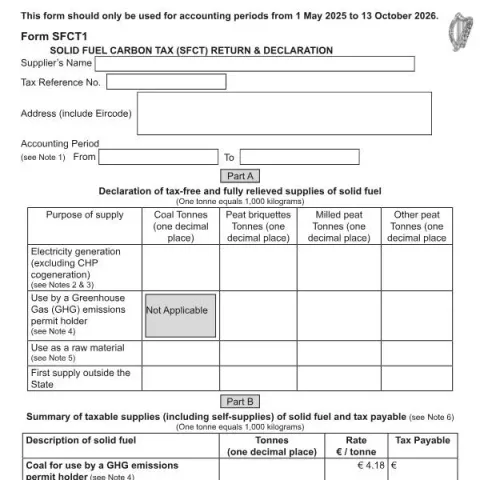
The Solid Fuel Carbon Tax (SFCT) Return & Declaration, known officially as Form SFCT1, is a mandatory tax compliance document issued by the Office of the Revenue Commissioners. It applies to suppliers involved in the sale or supply of solid fuels within Ireland, covering specific accounting periods from 1 May 2025 to 13 October 2026. This form is essential for reporting the quantities of solid fuels supplied, determining tax liabilities, and declaring tax-free or tax-relieved supplies.
Purpose and Scope of Form SFCT1
The primary purpose of Form SFCT1 is to ensure accurate reporting of solid fuel supplies, including taxable and exempt supplies, for the relevant accounting periods. It allows suppliers to declare quantities supplied, specify the nature of each supply, and calculate the corresponding tax payable or reliefs applicable under Irish law. The form caters to various types of solid fuels, such as coal, peat briquettes, milled peat, and other peat products, with specific considerations for biomass content and usage purposes.
When and How to Use the Form
The SFCT1 must be completed and submitted within one month of the end of each two-month accounting period. Suppliers, whether registered for the Revenue Online Service (ROS) or not, are required to file their returns and make payments accordingly. The form can be submitted online via ROS for registered users or through myAccount for non-ROS users, who may also opt to send a scanned copy by email or post.
Key Sections of the SFCT1 Form
Part A: Declaration of Tax-Free and Fully Relieved Supplies
This section requires suppliers to declare the quantities of solid fuels supplied at zero or reduced rates, such as supplies used for electricity generation, by GHG emissions permit holders, or as raw materials. Quantities are entered in tonnes, with one decimal place, for categories including coal, peat briquettes, milled peat, and other peat products.
Part B: Summary of Taxable Supplies and Tax Liability
Here, suppliers detail the total quantities of each solid fuel type supplied, including those subject to standard or reduced rates of tax based on biomass content. The form specifies different rates depending on the biomass percentage, ranging from €4.18 per tonne for certain coal uses to €167.24 per tonne for specific biomass-rich peat briquettes. The total tax payable is calculated based on these entries.
Declaration and Certification
In Part C, the supplier's authorized signatory must declare that all information provided is accurate and complete, affirming compliance with relevant legal provisions, including the Finance Act 2010 and the SFCT Regulations 2013. The declaration confirms that the quantities, tax reliefs, and certificates of biomass content are correct and available for inspection if required by Revenue.
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
Points of Attention and Practical Tips
- Accurate Record-Keeping: Suppliers must retain certificates of biomass content for all biomass products declared at relief rates, as Revenue may request verification during audits.
- Timely Filing and Payment: Returns must be filed within one month of the end of each accounting period to avoid interest charges or enforcement actions. Payments should be made promptly via ROS or myAccount.
- Understanding Usage Categories: Proper classification of supplies—whether for electricity generation, raw materials, or other purposes—is crucial for correct declaration and tax treatment.
- Compliance with Legal Requirements: The declaration must be signed by an authorized person, and all legal obligations under Irish law must be observed, including obtaining necessary certificates and declarations from relevant parties.
Conclusion
The SFCT1 form is a vital administrative requirement for suppliers of solid fuels in Ireland, ensuring transparency and compliance with the country's carbon tax regulations. Proper completion, timely submission, and adherence to legal obligations help avoid penalties and facilitate smooth tax management processes. Suppliers should familiarize themselves with the form's sections, keep comprehensive records, and seek guidance from Revenue resources if needed to ensure full compliance.