Understanding the Natural Gas Carbon Tax (NGCT) Return and Declaration (Form NGCT1) in Ireland
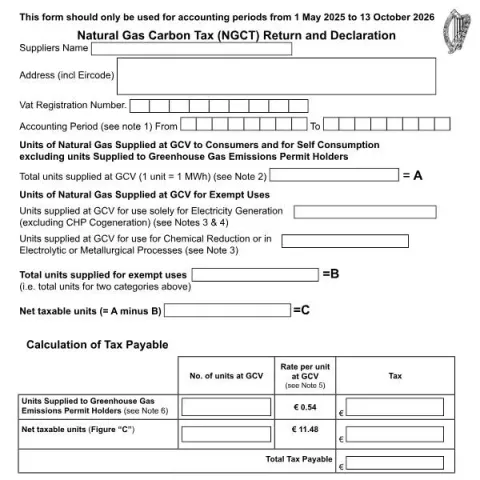
The Natural Gas Carbon Tax (NGCT) Return and Declaration is a mandatory compliance requirement for suppliers of natural gas operating within Ireland. Managed by the Office of the Revenue Commissioners, this form ensures that suppliers declare their natural gas supplies and calculate their corresponding tax liabilities for a specific accounting period. This article provides a comprehensive overview of when and how to complete this form, the key information required, and the procedures for submitting it correctly.
Scope and Timing of the NGCT1 Form
The NGCT1 form should only be used for accounting periods from 1 May 2025 to 13 October 2026. An accounting period is defined as a two-month interval, with the first period starting in January/February of each year. Suppliers are required to submit their return and declaration within one month after the end of each accounting period. This schedule allows the Revenue to monitor and collect the appropriate carbon tax on natural gas supplied within the specified timeframe.
Key Information Required for the Return
The form collects detailed data on the natural gas supplied at Gross Calorific Value (GCV), measured in units per megawatt hour (MWh). The main sections include:
- Supplier’s Details: Name, address (including Eircode), and VAT registration number.
- Accounting Period: Start and end dates of the period being reported.
- Units of Natural Gas Supplied: Total units supplied, broken down into categories such as exempt uses, electricity generation, and chemical or metallurgical processes.
- Tax Calculation: Application of the relevant rate (€0.54 per unit for greenhouse gas permit holders, as specified) to the net taxable units (total supplied minus exempt uses).
It is crucial to accurately record the units supplied and to distinguish between taxable and exempt quantities. Suppliers must also declare units supplied to Greenhouse Gas Emissions Permit Holders, as these are subject to specific rates and exemptions.
How to Complete and Submit the Form
Online Submission for ROS Registered Suppliers
Suppliers registered for the Revenue Online Service (ROS) can submit their NGCT1 return directly via their ROS account. The process involves selecting the appropriate tax declaration type and following the guided steps to upload the completed form and make the payment. Detailed instructions are available on the Revenue website under the Payment Services Guides.
For Non-ROS Registered Suppliers
Suppliers not registered with ROS have two options:
- Submit a scanned copy of the completed and signed Form NGCT1 via MyEnquiries through their myaccount portal.
- Send the completed form by post to the following address:
| Office of the Revenue Commissioners | Collector-General’s Division |
|---|---|
| Sarsfield House | Francis Street |
| Limerick | V94 R972 |
Payments for non-ROS suppliers can be made through the myaccount portal, following the instructions provided on the Revenue website under the Payments Guide.
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
Important Points and Compliance Tips
- Timely Submission: Ensure the return is filed within one month of the accounting period’s end to avoid interest charges or penalties.
- Accurate Data Entry: Verify the units supplied and exemption categories carefully, especially when dealing with exempt uses such as electricity generation or chemical processes.
- Record Keeping: Maintain copies of declarations of exempt usage and supporting documentation, as Revenue may request these during audits.
- Payment Deadlines: Allow sufficient time for payments to reach Revenue to avoid late payment interest and enforcement actions.
Legal Basis and Further Guidance
The obligation to complete and submit the NGCT1 form is grounded in Chapter 2 of Part 3 of the Finance Act 2010 and the NGCT Regulations 2010. Compliance with these legal provisions ensures proper calculation and remittance of the carbon tax, supporting Ireland’s environmental and taxation policies.
For further assistance, suppliers are encouraged to consult the official Revenue guides or contact Revenue directly through their online services. Proper adherence to these procedures not only ensures compliance but also contributes to Ireland’s efforts in managing greenhouse gas emissions effectively.