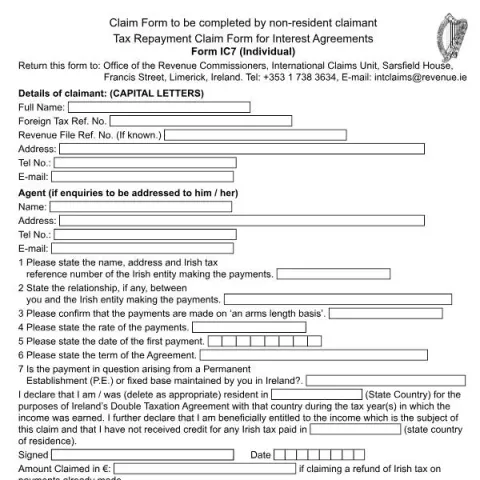
Understanding the Irish Tax Repayment Claim Form for Interest Agreements (Form IC7)
The Form IC7, officially titled Tax Repayment Claim Form for Interest Agreements, is a crucial document issued by the Office of the Revenue Commissioners in Ireland. It is specifically designed for non-resident individuals who seek to reclaim Irish withholding tax deducted on interest payments made under interest agreements involving Irish entities. This form plays a vital role in ensuring that non-residents can recover taxes paid in Ireland, especially when applicable treaties or exemptions apply.
Purpose and Scope of the Form
The primary objective of the Form IC7 is to enable non-resident claimants to request a refund of Irish tax deducted at source on interest payments. It is applicable to individuals who have earned interest income from Irish sources and believe they are eligible for a reduction or exemption under Ireland’s double taxation agreements (DTAs) or domestic legislation. The form is to be completed and submitted to the International Claims Unit of the Revenue Commissioners, located in Limerick.
Preparing Your Dossier for Submission
Gathering Essential Documentation
- A fully completed Form IC7, with all sections accurately filled out in capital letters.
- A copy of the Interest Agreement signed by both parties, which details the terms of the interest payments.
- The Form R185, if claiming a repayment of tax already deducted.
- For residents of specific countries, additional certificates such as a Form 6166 (for US residents) or a Certificate of Residence (for Spanish residents) may be required.
Completing the Form Correctly
Each section of the form must be filled with precise information, including:
- Details of the Irish entity making the payments, including name, address, and Irish tax reference number.
- The relationship between the claimant and the Irish entity.
- Confirmation that payments are made on an 'arms length basis'.
- The rate of interest paid, the date of the first payment, and the term of the agreement.
- Whether the payment arises from a Permanent Establishment or fixed base in Ireland.
- Residency declaration, confirming the claimant's residence status during the relevant tax years.
Submission Procedures and Deadlines
Claims must be submitted within four years following the end of the calendar year in which the tax was deducted, as stipulated by Section 17 of the Finance Act 2003. The completed form, along with all supporting documentation, should be sent to:
Office of the Revenue Commissioners International Claims Unit Sarsfield House, Francis Street, Limerick, Ireland Tel: +353 1 738 3634 Email: [email protected]How the Irish Revenue Handles the Claim
Once received, the Revenue Commissioners will review the claim, verify the documentation, and determine the eligibility based on applicable treaties and legislation. If approved, the refund will be processed electronically, transferred directly to the bank account details provided by the claimant. It is important to ensure that the bank details, including IBAN and BIC, are accurate to avoid delays.
Important Considerations and Additional Notes
Supporting Documentation
Alongside the completed Form IC7, the following documents are essential:
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
- A signed copy of the Interest Agreement.
- The relevant claim form (e.g., Form R185) for tax deducted.
- Certificates of residence, if applicable, especially for US or Spanish residents.
Time Limits and Exemptions
Claims must be submitted within four years after the tax deduction year. Claimants should also consider whether they qualify for exemptions from Irish withholding tax under section 246(3) of the Taxes Consolidation Act 1997. Additionally, residents of treaty countries may benefit from reduced withholding rates under Ireland’s DTAs, which can be self-certified via the provisions outlined in the Revenue’s guidance manual.
Conclusion
The Form IC7 is an essential tool for non-residents seeking to recover Irish tax withheld on interest payments. Proper preparation, timely submission, and adherence to documentation requirements are key to successfully claiming a refund. For further assistance or clarification, claimants are advised to contact the Revenue’s International Claims Unit directly or consult their official guidance resources.