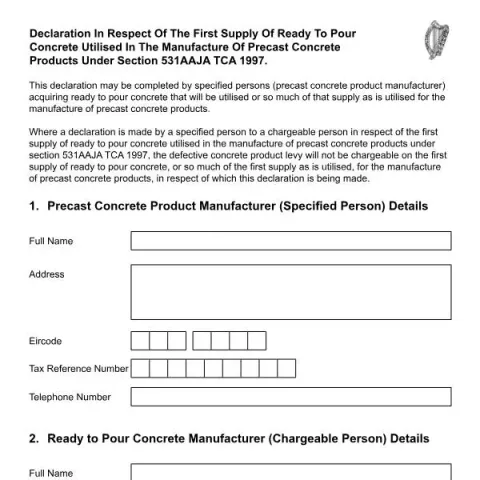
Understanding the Irish Revenue Form DCPL Declaration for Ready to Pour Concrete
The Irish Revenue Commissioners require specific documentation for manufacturers involved in the production of precast concrete products. The Form DCPL Declaration is an official document used to declare the first supply of ready to pour concrete that will be used in the manufacturing of these products. This declaration plays a crucial role in the application of the defective concrete products levy, ensuring that the correct tax treatment is applied during the initial supply process.
Purpose and When to Use the Form
This form must be completed by a precast concrete product manufacturer (referred to as the specified person) when they acquire ready to pour concrete from a supplier (the chargeable person). It is specifically used in the context of the first supply of ready to pour concrete that will be utilized in manufacturing precast concrete products. The purpose of the declaration is to confirm that the concrete will be used for manufacturing, which exempts the first supply from the defective concrete products levy.
Each supply of ready to pour concrete intended for precast manufacturing requires a separate declaration. The form ensures compliance with section 531AAJA of the Taxes Consolidation Act 1997 and helps prevent unnecessary tax charges on the initial supply.
Key Information Required on the Declaration
The form requests detailed information from both parties involved:
- Precast Concrete Product Manufacturer (Specified Person):
- Full Name
- Address and Eircode
- Tax Reference Number
- Telephone Number
- Ready to Pour Concrete Manufacturer (Chargeable Person):
- Full Name
- Address and Eircode
- Tax Reference Number
- Telephone Number
Additionally, details of the specific consignment are required, including:
- Delivery Address and Eircode
- Date of Supply
- Volume of Ready to Pour Concrete (in cubic metres)
- Open Market Value of the Supply (€)
Completing and Submitting the Declaration
The declaration must be signed and dated by the authorized representative of the precast concrete manufacturer. By signing, the declarant affirms that:
- They are a specified person under the relevant legislation.
- The first supply or part of it will be used exclusively for manufacturing precast concrete products.
- They meet the conditions set out in Part 18E of the Taxes Consolidation Act 1997.
- All information provided is accurate and complete.
The completed form should be retained by the precast concrete manufacturer, while the supplier must keep the original declaration for six years from the end of the relevant accounting period. This record-keeping is essential in case of audits or verification by Revenue.
Legal and Practical Considerations
It is important to note that the declaration applies solely to the initial supply of ready to pour concrete used in manufacturing precast products. If the concrete is used for other purposes, the levy may still apply. The form ensures transparency and compliance with Irish tax law, facilitating correct tax treatment and avoiding unnecessary levies on the first supply.
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
Manufacturers and suppliers should ensure all details are correctly filled out and retained, as the declaration is a legal document. Any inaccuracies or incomplete information could lead to penalties or tax disputes.
Conclusion
The Form DCPL Declaration is a vital administrative tool for manufacturers of precast concrete products in Ireland. It streamlines the process of claiming exemption from the defective concrete products levy on the first supply of ready to pour concrete used in manufacturing. Proper completion and retention of this document help ensure compliance with Irish tax law and facilitate smooth interactions with Revenue Commissioners.