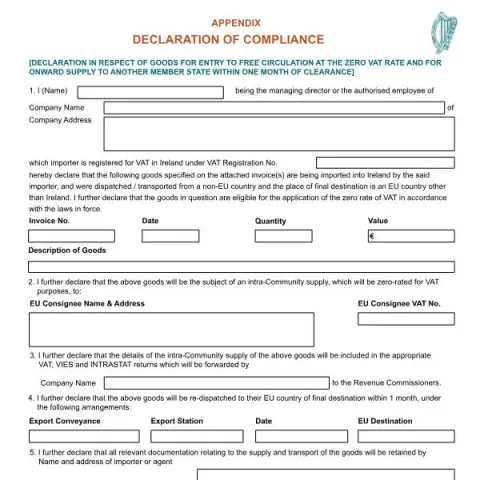
Understanding the Declaration of Compliance for Zero VAT on Goods Entering Ireland for Intra-Community Supply
The Declaration of Compliance (form code: RPC013878_EN_WB_L_1) is an official document issued by the Revenue Commissioners of Ireland. It pertains specifically to goods imported into Ireland from non-EU countries that are intended for onward intra-Community supply within the European Union (EU). This form plays a crucial role in ensuring compliance with Irish VAT laws, particularly regarding the application of the zero rate of VAT on qualifying goods.
What Is the Purpose of This Declaration?
This declaration serves multiple purposes:
- To confirm that imported goods are eligible for the zero VAT rate when they are dispatched for intra-Community supply.
- To provide the Revenue Commissioners with detailed information about the goods, their origin, and their intended destination within the EU.
- To establish a legal record that the importer intends to re-dispatch the goods to another EU member state within one month of clearance, in accordance with Irish VAT legislation.
- To facilitate the correct VAT treatment and compliance with intra-Community trade regulations.
Who Needs to Complete This Form?
The form must be completed by the managing director or an authorized employee of a VAT-registered company that imports goods into Ireland from outside the EU. The company must declare that the goods are intended for intra-Community supply, and that they will be re-dispatched within the stipulated timeframe. This process is essential for businesses engaged in cross-border trade within the EU, particularly those seeking to benefit from the zero VAT rate on qualifying goods.
How to Fill Out the Declaration of Compliance
Section 1: Import Details
Provide the full name of the person completing the form, along with the company's name, address, and VAT registration number. Specify the invoice number, date, quantity, value (in euros), and a detailed description of the goods. This section confirms the import and the eligibility of the goods for zero VAT based on Irish law.
Section 2: Intra-Community Supply Details
Declare the recipient's name and address within the EU, along with their VAT number. This confirms the intention to supply the goods to an EU customer under zero-rated intra-Community supply rules.
Section 3: VAT and VIES Returns
Indicate the name of the company responsible for including the intra-Community supply details in the relevant VAT, VIES (VAT Information Exchange System), and INTRASTAT returns. These returns are submitted to the Revenue Commissioners and are essential for compliance and record-keeping.
Section 4: Re-Dispatch Arrangements
Describe the arrangements for re-dispatching the goods to the final EU destination, including the export conveyance, export station, date of dispatch, and the EU destination country. This section confirms the planned timeline for re-export within one month.
Section 5: Documentation and Record-Keeping
State the name and address of the person or entity responsible for maintaining all relevant documentation related to the goods' transport and supply. These records must be retained for a period of three years and be available for inspection by Revenue officers if required.
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
Section 6: Undertaking and Signatures
The signatory undertakes to pay any VAT due if the conditions for zero-rating are not met. The form must be signed and dated by an authorized person, with their name and address clearly printed in block capitals.
Where and How to Submit the Form
The completed declaration should be submitted to the Revenue Commissioners, typically by post or as part of the relevant customs or VAT documentation process. It is important to retain a copy of the form and all supporting documentation for at least three years, as Revenue officers may request to inspect these records during audits or compliance checks.
Common Errors to Avoid
- Failing to declare accurate and complete details of the goods, including description, quantity, and value.
- Not specifying the correct arrangements for re-dispatch within the one-month timeframe.
- Omitting to include the intra-Community supply details in VAT, VIES, and INTRASTAT returns.
- Neglecting to retain documentation for the required three-year period.
Proper completion and submission of this declaration are essential to benefit from the zero VAT rate on goods being imported into Ireland for intra-Community supply. Businesses should ensure compliance with all legal requirements to avoid penalties or delays in their trade activities within the EU.