Understanding the Irish Non-Resident Form V2A: A Guide for Qualifying Individuals
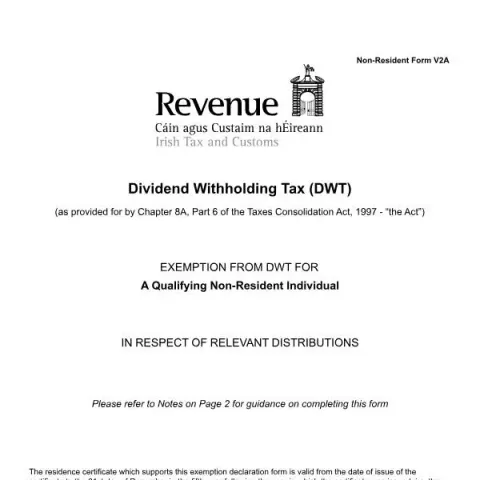
The Irish Revenue Commissioners have established the Non-Resident Form V2A as a crucial document for individuals who are non-resident in Ireland and wish to benefit from exemption from Dividend Withholding Tax (DWT). This form is designed to facilitate compliance with Ireland’s tax regulations while allowing qualifying non-residents to receive relevant distributions without the deduction of DWT. Below, we explore the purpose of this form, the process of preparing and submitting it, and key considerations for applicants.
Purpose and Scope of Form V2A
The primary objective of Form V2A is to declare that a non-resident individual qualifies for exemption from DWT on relevant distributions from Irish-resident companies. Under Chapter 8A, Part 6 of the Taxes Consolidation Act, 1997, this exemption is available to individuals who meet specific residency criteria. The form acts as a formal declaration from the individual, supported by a residence certificate issued by the tax authorities of their country of residence, confirming their status as a qualifying non-resident person.
This exemption benefits individuals who are neither resident nor ordinarily resident for Irish tax purposes but are resident in a country classified as a “relevant territory.” Such territories include EU member states, EEA countries, or states with which Ireland has a Double Taxation Agreement. The exemption applies solely to relevant distributions, which typically include dividends paid by Irish companies.
Preparing the Application: Key Steps and Documentation
To successfully apply for exemption using Form V2A, applicants should follow a structured process:
- Obtain a Residence Certificate: The applicant must secure a certificate from the tax authorities of their country of residence. This document confirms their residency status for tax purposes and must be valid from the date of issue until 31 December of the fifth year following the year of issuance.
- Complete the Form Accurately: The form requires personal details such as the shareholder's name, address, and tax reference number in their country of residence. If applicable, an Irish tax reference should also be provided.
- Declaration and Supporting Documents: The applicant must declare their beneficial entitlement to the relevant distributions and attach the residence certificate. The declaration includes an affirmation that the individual is a qualifying non-resident person.
- Sign and Date: The form must be signed in ink by the declarant or their authorized representative, with the date clearly indicated.
Once completed, the form should be forwarded to the relevant Irish paying company, qualifying intermediary, or authorized withholding agent. It is important to note that the form should not be sent directly to the DWT Unit, as it is intended to facilitate exemption at the point of payment.
Submission and Validity
The validity of the exemption declaration is tied to the residence certificate’s validity period, which extends until 31 December of the fifth year after issuance. Applicants should ensure that their certificate remains current and reapply if their residency status changes.
It is also essential to retain a copy of the completed form for personal records and potential future claims, such as refunds of DWT where applicable. The form can be photocopied for subsequent declarations, but each declaration must be signed and dated anew to confirm its authenticity.
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
Additional Considerations and Contact Points
Applicants should be aware that the process involves verifying their residency status through their tax authority and ensuring that the Irish entity or intermediary receives the declaration. For questions or assistance with completing the form, the Revenue DWT Unit can be contacted via the details provided on the official Revenue website or through their contact channels.
In summary, Form V2A plays a vital role in streamlining the process for non-residents to receive Irish distributions without unnecessary tax deductions. Proper preparation, accurate completion, and timely submission are key to ensuring compliance and enjoying the benefits of exemption from DWT.