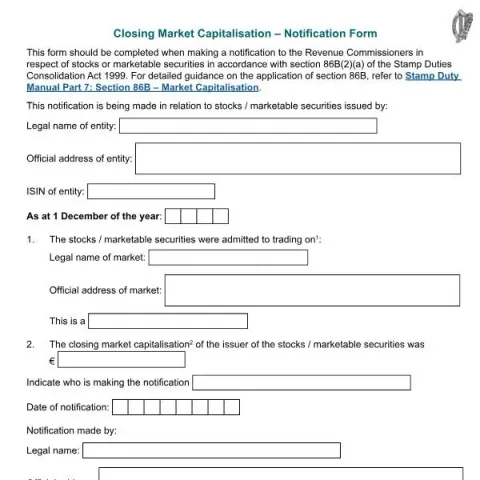
Understanding the Closing Market Capitalisation – Notification Form in Ireland
The Closing Market Capitalisation – Notification Form is an official document issued by the Revenue Commissioners of Ireland. It serves a specific purpose within the context of Irish tax law and securities regulation, particularly relating to the Stamp Duties Consolidation Act 1999. This form is essential for entities involved in the issuance or trading of stocks or marketable securities, providing a formal notification regarding their market capitalisation at a specific point in time.
Purpose of the Form
This form is primarily used to notify the Revenue Commissioners of the market capitalisation of stocks or securities issued by a particular entity, as at 1 December of the relevant year. The information supplied through this form is crucial for compliance with section 86B(2)(a) of the Stamp Duties Consolidation Act 1999. Accurate reporting ensures that the appropriate stamp duty obligations are identified and managed, and that the market value of securities is correctly reflected in tax assessments.
Who Must Complete the Form?
The form must be completed by entities involved in the issuance, trading, or holding of stocks or securities that are admitted to trading on a market. This includes:
- Issuer companies or entities,
- Market operators or exchanges, and
- Any third-party entities responsible for notification on behalf of the issuer.
If the securities are traded on multiple markets, the form should be submitted for the primary market where the securities are admitted to trading. It is important that the correct entity or market operator completes and submits the form to ensure compliance with Irish tax law.
How to Complete the Form
Section 1: Details of the Issuer
Provide the legal name of the entity issuing the securities, its official address, and the ISIN (International Securities Identification Number). Specify the date as of 1 December of the relevant year to indicate the snapshot date for the market capitalisation.
Section 2: Trading Market Information
Indicate the market where the securities are admitted to trading, including the legal name of the market, its official address, and the type of market (e.g., regulated market, multilateral trading facility). If the securities are traded on multiple markets, only one should be selected for the notification.
Section 3: Market Capitalisation
Enter the closing market capitalisation of the issuer’s securities, expressed in euros. If the market value is originally in a different currency, convert it to euros using the appropriate exchange rate as of 1 December of the relevant year.
Section 4: Notification Details
Provide details of the person or entity making the notification, including their legal name, official address, email, and phone number (including country code). The date of notification should also be specified.
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
Supporting Documents and Submission Process
Once completed, the form should be emailed to [email protected] with the subject line “Market cap exemption”. No physical submission is required, but it is advisable to keep copies of the completed form and any supporting documentation for your records.
Common Errors and Tips for Accurate Submission
- Incorrect currency conversion: Ensure the market capitalisation is converted accurately to euros as of 1 December.
- Multiple markets: Only submit the form for one market, even if securities are traded on several exchanges.
- Incomplete details: Fill out all relevant sections completely to avoid delays or rejections.
- Timely submission: Submit the form before any deadlines set by the Revenue Commissioners to ensure compliance.
Conclusion
The Closing Market Capitalisation – Notification Form is a key compliance tool for entities involved in securities trading in Ireland. Proper completion and timely submission help ensure adherence to tax obligations related to stamp duty and market valuation. For further guidance, refer to the Stamp Duty Manual Part 7: Section 86B – Market Capitalisation, and consult with a tax professional or legal advisor if necessary.