Understanding the Expected Market Capitalisation Notification Form (RPC020136_EN_WB_L_1)
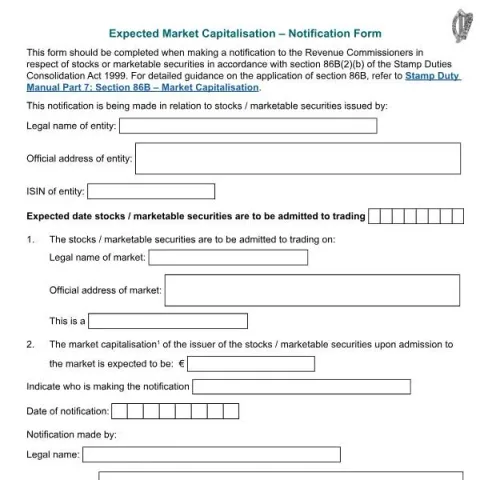
The Expected Market Capitalisation – Notification Form is an official document issued by the Revenue Commissioners of Ireland. It serves a specific purpose within the Irish tax and securities framework, primarily relating to the Stamp Duties Consolidation Act 1999. This form is essential for entities issuing stocks or marketable securities that are to be admitted to trading on a recognised market in Ireland or abroad. Proper completion and submission of this form ensure compliance with Irish tax law and facilitate the correct assessment of stamp duty obligations.
When and Why to Use the Form
This notification must be submitted whenever an entity intends to admit stocks or marketable securities to trading and expects the market capitalization at that time to reach a certain threshold. The primary legal basis for this requirement is section 86B(2)(b) of the Stamp Duties Consolidation Act 1999. The form is used to declare the anticipated market value of securities upon their admission to trading, which is crucial for determining whether stamp duty exemptions or liabilities apply.
Typically, issuers such as companies planning an initial public offering (IPO), or those listing additional securities, will need to complete this form. It ensures that the Irish Revenue authorities are informed of the expected size of the securities issue, which may impact the stamp duty treatment and compliance obligations.
Key Information Required on the Form
The form requests detailed data about both the issuer and the market where securities will be traded:
- Issuer Details: Legal name, official address, and ISIN of the securities.
- Expected Admission Date: The date when the stocks or securities are to be admitted to trading.
- Market Details: Name of the market, official address, and whether it is a regulated or third-market facility, including the country of operation.
- Expected Market Capitalisation: The anticipated value of the issuer’s securities at the time of admission, expressed in euros. If the valuation is in another currency, the appropriate exchange rate must be used.
- Notification Details: Date of notification, the legal name of the person or entity submitting the form, their official address, email, and phone number (including country code).
It is important to note that the form must be completed accurately, especially regarding the expected market capitalisation. An incorrect valuation could lead to issues with tax compliance or future audits.
How to Submit the Form
Once completed, the form should be sent electronically via email to [email protected]. The subject line of the email must include the phrase “Market cap exemption” to facilitate processing. It is advisable to retain a copy of the submission confirmation for your records.
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
Points of Attention and Practical Tips
- Accurate Valuation: Ensure the market capitalisation estimate is realistic and based on reliable data. An over- or under-estimate may affect stamp duty obligations or trigger compliance checks.
- Currency Conversion: If the valuation is in a foreign currency, use the official exchange rate applicable at the date of valuation to convert into euros.
- Timeliness: Submit the notification well in advance of the securities’ admission to trading to avoid delays or penalties.
- Data Privacy: Be aware that your personal data will be processed in accordance with Revenue’s data protection policy, which is detailed on their Privacy page.
Legal and Regulatory Context
This form is part of Ireland’s broader regulatory framework governing securities markets and taxation. The Revenue Commissioners oversee tax compliance related to securities transactions, ensuring that stamp duty obligations are correctly applied. The form also aligns with the requirements set out in the Irish Constitution and relevant sector-specific legislation.
For further guidance, entities should consult the Stamp Duty Manual Part 7: Section 86B – Market Capitalisation, or seek professional advice to ensure full compliance with Irish law when issuing securities and submitting this notification.