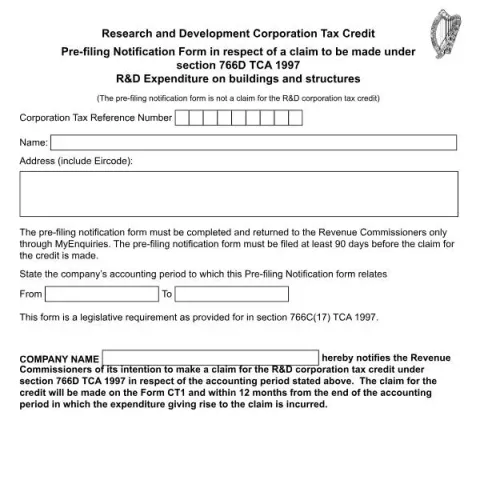
Understanding the Research and Development Corporation Tax Credit Pre-filing Notification Form (Code: 766D) in Ireland
The Irish Revenue Commissioners require companies intending to claim the Research and Development (R&D) Corporation Tax Credit under section 766D of the Taxes Consolidation Act 1997 to submit a specific pre-filing notification form, identified as Form 766D. This form is a legislative obligation designed to inform Revenue of a company's intention to make an R&D tax credit claim, and it must be completed before the actual claim is filed. This article provides a comprehensive overview of the purpose, eligibility, and procedural steps involved in submitting this pre-filing notification.
Purpose and Scope of the Pre-filing Notification
The primary purpose of the Form 766D is to notify the Revenue Commissioners of a company's intention to claim the R&D tax credit for a specific accounting period. It is important to note that this notification is not a claim itself but a prerequisite that must be fulfilled at least 90 days prior to submitting the actual claim via the Form CT1. The notification helps ensure transparency and allows Revenue to prepare for the review process.
This requirement applies to companies that are claiming the R&D tax credit under section 766D for the first time or those that have not claimed such credits in any of the previous three accounting periods. The form must be submitted through the online portal MyEnquiries, part of Revenue's digital services.
Key Conditions and Eligibility Criteria
When to Submit the Form
The pre-filing notification must be filed at least 90 days before the company intends to make the formal R&D tax credit claim. This timeline ensures that Revenue has adequate notice to process and review the company's intentions prior to the claim submission.
Who Should Complete the Form
Any company planning to claim the R&D tax credit under section 766D, especially those doing so for the first time or after a period of non-claim, must complete this form. It is also necessary for companies that have not claimed the credit in the last three accounting periods.
Criteria for R&D Activities and Buildings
- Qualifying R&D activities: Must be systematic, investigative, or experimental activities aimed at scientific or technological advancement. These activities should involve research in science or technology and seek to resolve scientific or technological uncertainties.
- Qualifying buildings or structures: A building qualifies if, over a four-year period (the relevant period), at least 35% of its use is attributable to R&D activities carried out within a relevant Member State.
- Expenditure: Any costs associated with the R&D activities that have been or will be met directly or indirectly by grants or other assistance are included. Assistance can come from public bodies, EU institutions, or other relevant bodies.
Procedure for Completing and Submitting the Form
Step-by-step Process
- Access the form: Log into MyEnquiries, Revenue's online enquiry portal, and select the category 'Corporation Tax' and subcategory 'R&D Pre-filing Notification.'
- Complete Section 1: Provide details about the company, including Corporation Tax Reference Number, company name, address (including Eircode), and the relevant accounting period (from and to dates).
- Declare R&D activities: Confirm whether the building or structure qualifies, specify the proportion used for R&D, and detail any expenditure met through grants or assistance.
- Complete Section 2: Add any additional information or comments that may support the notification or clarify the R&D activities undertaken.
- Submit the form: Once completed, submit the notification electronically via MyEnquiries. The Revenue Commissioners may request further information to verify the details provided.
Post-Submission Considerations
After submitting the pre-filing notification, companies should prepare to file their formal R&D tax credit claim using Form CT1 within 12 months of the end of the relevant accounting period. It is essential to retain documentation and records supporting the activities and expenditure declared, as Revenue may request these during audits or reviews.
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
Failure to submit the pre-filing notification at least 90 days before the claim may result in delays or disqualification of the R&D tax credit claim. Therefore, companies should plan their submissions carefully to comply with the legal requirements.
Additional Notes
It is important to remember that the pre-filing notification form is a legislative requirement introduced to enhance transparency and compliance. It is not a claim for the R&D tax credit itself. Proper completion and timely submission of this form are crucial steps in the overall process of claiming R&D tax incentives in Ireland.