Partnership Tax Returns: Navigating the SA800 Obligations and Deadlines
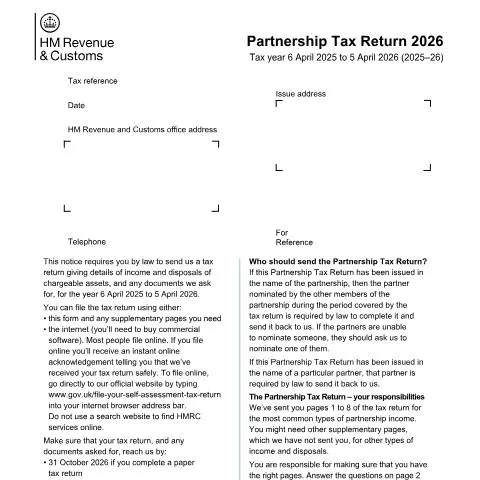
When partnerships in the UK generate income, dispose of assets, or engage in qualifying business activities during the tax year, HMRC requires detailed reporting through the Partnership Tax Return (SA800). This comprehensive document serves as the cornerstone of partnership taxation, capturing everything from trading profits to property income and capital gains. The responsibility for completing this return typically falls on a nominated partner, though the legal obligations extend to all partnership members.
The SA800 operates on a strict deadline structure that demands careful attention. For the 2025-26 tax year, partnerships must submit their returns by 31 October 2026 for paper submissions or 31 January 2027 for online filing. These dates become particularly crucial when considering that each partner faces automatic penalties if the partnership fails to meet these deadlines, regardless of whether they were directly involved in the preparation process.
The Nominated Partner System: Responsibilities and Legal Framework
The partnership tax return operates through a nominated partner system that creates specific legal responsibilities. When HMRC issues the SA800 in the partnership's name, the partners must nominate one individual to complete and submit the return. This nomination isn't merely administrative convenience—it's a legal requirement that determines who bears the primary responsibility for accuracy and timeliness.
If partners cannot agree on a nomination, HMRC will step in and designate someone themselves. Alternatively, when the return is issued directly to a specific partner's name, that individual becomes legally bound to complete the submission. This system ensures accountability while recognising the practical challenges of collective decision-making in partnership structures.
The nominated partner must ensure that all partnership members receive the information they need for their personal tax returns as quickly as possible. This requirement becomes particularly pressing for partners who prefer to submit their individual returns by the earlier 31 October deadline, rather than waiting until the following January.
Information Flow and Partner Coordination
The SA800 creates a cascade of information requirements that extend beyond the partnership itself. Individual partners rely on the partnership return data to complete their personal Self Assessment returns accurately. This interdependency means that delays or errors in the partnership return can create complications for multiple individuals' tax obligations.
Partners should establish clear communication protocols early in the tax year to ensure smooth information sharing. The nominated partner typically needs access to:
- Partnership accounting records and profit and loss statements
- Details of any property income or rental activities
- Records of capital gains and disposals during the tax year
- Information about foreign income or overseas activities
- Documentation of any business changes, including starts or cessations
Determining Required Supplementary Pages Through Strategic Questioning
The SA800 includes a sophisticated question framework designed to identify which supplementary pages each partnership requires. This system prevents unnecessary paperwork while ensuring comprehensive reporting of all relevant income streams and activities.
The core questions on page 2 of the return systematically cover different income categories and partnership characteristics. These inquiries determine whether additional forms are needed for UK property income, foreign earnings, capital gains, or specialised partnership structures involving corporate partners or non-UK residents.
| Question Category | Triggers Additional Pages | Typical Scenarios |
|---|---|---|
| UK Property Income | Property supplementary pages | Rental properties, commercial lettings |
| Foreign Income | Foreign income pages | Overseas trading, foreign property |
| Capital Disposals | Capital gains pages | Asset sales, business disposals |
| Corporate Partners | Specialised partnership pages | Limited companies as partners |
| Export Activities | Additional reporting requirements | Goods or services sold internationally |
Cash Basis vs Traditional Accounting Elections
One critical decision reflected in the SA800 involves the accounting method used to calculate partnership income and expenses. Partnerships can elect to use either the cash basis or traditional accruals accounting, with significant implications for timing of income recognition and expense deductions.
The cash basis typically suits smaller partnerships with straightforward income streams, as it recognises income when received and expenses when paid. Traditional accounting, marked by ticking box 3.9, follows accruals principles and may be mandatory for larger partnerships or those with complex transactions.
Partnership Lifecycle Events and Their SA800 Implications
The SA800 must capture significant changes in partnership structure during the tax year, including commencements, cessations, and changes in accounting periods. These events trigger specific reporting requirements and can affect the partnership's overall tax obligations.
When a partnership starts after 5 April 2025, box 3.7 requires completion with the exact start date. This information affects how income is apportioned and may influence the partnership's first accounting period. Similarly, partnerships that cease operations before the end of the tax year must report the cessation date in box 3.8, triggering final return procedures.
Accounting Period Complexities
Partnerships don't always align their accounting periods with the standard tax year running from 6 April to 5 April. The SA800 accommodates these variations through boxes 3.4 and 3.5, which capture the actual accounting period covered by the partnership's records.
When partnership accounts don't cover the expected period from the last accounting date, box 3.11 must be ticked, with explanations provided in the additional information section. This flexibility recognises that partnerships may change their accounting dates or face unusual circumstances requiring adjusted reporting periods.
Multiple Trades and Complex Partnership Structures
Partnerships conducting multiple trades face additional complexity in SA800 completion. Each separate trade requires its own set of boxes within the return, reflecting HMRC's requirement for detailed analysis of different income streams and business activities.
This separation becomes particularly important when partnerships operate diverse business activities—for example, a partnership running both a consultancy service and property development activities. Each trade's income, expenses, and profit allocation must be clearly distinguished to ensure accurate tax calculations for individual partners.
Corporate and Non-Resident Partner Considerations
Question 5 on the SA800 identifies partnerships with special characteristics that trigger additional reporting obligations. Partnerships including corporate partners, non-UK residents, or partners involved in foreign-controlled businesses face enhanced scrutiny and may require supplementary documentation.
These arrangements often involve complex tax planning considerations and may be subject to specific anti-avoidance provisions. The SA800 serves as HMRC's mechanism for identifying such structures and ensuring appropriate tax treatment across different jurisdictions and entity types.
Submission Channels and Their Strategic Implications
The choice between paper and online submission carries practical implications beyond mere convenience. Online filing through HMRC's official portal provides instant acknowledgement of receipt, eliminating uncertainty about whether the return reached HMRC within the deadline period.
However, online submission requires commercial software purchase, as HMRC doesn't provide free partnership return software equivalent to their individual Self Assessment portal. This cost consideration must be weighed against the benefits of electronic filing, including the extended deadline until 31 January rather than 31 October for paper returns.
HMRC specifically warns against using search websites to locate their online services, emphasising the importance of typing www.gov.uk/file-your-self-assessment-tax-return directly into browsers. This guidance reflects ongoing concerns about fraudulent websites that mimic official tax services.
Late Filing Consequences and Penalty Structure
The SA800's penalty structure affects all partnership members, not just the nominated partner responsible for submission. Automatic penalties apply when returns miss the filing deadline, creating shared liability across the partnership regardless of individual involvement in the preparation process.
These penalties compound with interest charges on any late-paid tax, creating escalating costs that can significantly impact partnership finances. The automatic nature of these penalties means that technical difficulties or administrative oversights carry immediate financial consequences.
Documentation Standards and Accuracy Requirements
HMRC's warning about checking all tax returns and imposing penalties for false or incomplete information underscores the importance of thorough preparation and accurate record-keeping. The SA800 requires supporting documentation that substantiates all reported figures and claims.
Partnerships should maintain comprehensive records throughout the tax year, including detailed accounting records, receipts for expenses, documentation of capital transactions, and evidence supporting any claims for reliefs or allowances. This documentation becomes crucial if HMRC selects the partnership for enquiry or compliance review.
The requirement to identify and obtain appropriate supplementary pages places responsibility on partnerships to understand their own activities fully. Missing pages or incomplete reporting can trigger penalties and additional scrutiny, making thorough preparation essential for successful SA800 completion.
Export activities, captured through Question 6.1, require partnerships to distinguish between goods and services sold internationally. This information supports HMRC's economic analysis and may influence the partnership's eligibility for various export-related reliefs or incentives available through the UK tax system.
Partnership Changes and Cessation Considerations
Partnership structures can evolve significantly throughout a tax year, and the SA800 requires careful attention to these changes. When partners join or leave during the accounting period, you must apportion profits and losses based on their actual period of membership. The return includes specific boxes for recording partner admission and cessation dates, which directly impact profit-sharing calculations.
If a partner joins mid-year, their profit share typically starts from their admission date, though partnership agreements may specify different arrangements. For departing partners, you'll need to calculate their share up to their leaving date and ensure any outstanding capital accounts are properly resolved. HMRC expects clear documentation supporting these calculations, particularly where profit-sharing ratios change during the year.
Partnership cessation presents additional complexities for the SA800. When a partnership dissolves, the final return must account for all assets distributed, any goodwill valuations, and potential balancing charges on capital allowances. Partners may face capital gains implications on asset distributions, which while not reported on the SA800 itself, must be considered for their individual returns. The partnership must also settle any outstanding liabilities and distribute remaining funds according to the partnership agreement.
Dormant partnerships require special consideration. If your partnership becomes inactive but doesn't formally dissolve, you must still submit an SA800 showing nil activity. HMRC distinguishes between temporary inactivity and permanent cessation, with different reporting requirements for each scenario. Partnerships planning extended periods of inactivity should consider formal cessation procedures to avoid ongoing compliance obligations.
Capital Allowances and Asset Management
Capital allowances represent one of the most technical aspects of partnership tax returns, requiring detailed tracking of qualifying expenditure and disposal proceeds. The SA800 includes comprehensive sections for recording plant and machinery additions, with separate treatment for different allowance categories including Annual Investment Allowance (AIA), first-year allowances, and writing-down allowances.
Partnerships can claim AIA up to the annual limit, currently substantial for qualifying expenditure. However, where accounting periods don't align with tax years, or partnerships have related companies, the available allowance may be restricted. The SA800 requires careful calculation of these limitations, particularly for partnerships with fluctuating partner numbers or corporate partners subject to associated company rules.
Special rate pools apply to certain assets including integral features of buildings, cars with higher CO2 emissions, and thermal insulation. These assets attract lower writing-down allowance rates and must be separately identified on the return. Partnerships acquiring second-hand assets may face restrictions on available allowances, depending on the seller's circumstances and any connected party relationships.
Asset disposals require careful consideration of balancing adjustments. When partnership assets are sold for more than their tax written-down value, balancing charges may arise, effectively clawing back excess allowances previously claimed. Conversely, disposal proceeds below written-down values generate balancing allowances, providing additional tax relief. The SA800 includes specific boxes for recording these adjustments, which directly impact the partnership's taxable profit.
Partnerships operating from business premises face particular complexities around fixtures and fittings. Items qualifying as plant and machinery for allowance purposes aren't always obvious, with HMRC guidance distinguishing between integral building features and qualifying equipment. Professional advice often proves valuable for maximising legitimate allowance claims while avoiding disputes over classification.
International Aspects and Cross-Border Considerations
Partnerships with international elements face significantly enhanced reporting requirements on the SA800. Non-resident partners trigger additional disclosure obligations, requiring detailed information about their tax residence status and any relevant double taxation treaty provisions. The partnership must maintain comprehensive records of each non-resident partner's profit allocation and any UK tax suffered under partnership withholding arrangements.
Foreign income received by UK partnerships requires careful classification between trading income, investment income, and capital receipts. Currency fluctuations can create additional complexities, particularly where partnership accounts are maintained in foreign currencies but the SA800 must be completed in sterling. Exchange rate movements between earning and receipt dates may generate taxable gains or allowable losses requiring separate calculation.
Partnerships with overseas operations must consider permanent establishment rules, which can significantly impact UK tax liabilities. A partnership carrying on business abroad through a fixed place of business may create permanent establishments in multiple jurisdictions, each with distinct reporting requirements. The SA800 includes sections for recording overseas permanent establishment profits, though detailed calculations often require specialist advice.
Transfer pricing rules apply to partnerships with international connected parties, requiring arm's length pricing for cross-border transactions. This particularly affects partnerships providing services to overseas group companies or licensing intellectual property internationally. Documentation requirements can be substantial, and the SA800 may need to reflect adjustments where HMRC challenges pricing arrangements.
Controlled Foreign Company (CFC) rules can impact partnerships with overseas subsidiaries, potentially creating additional UK tax charges on undistributed profits. While CFC charges don't appear directly on the SA800, they affect partner profit allocations and must be considered when preparing individual partner returns. Professional advice becomes essential for partnerships with complex international structures.