Understanding SDLT Manual 62047 Schedule: When Property Transactions Require Additional Lease Documentation
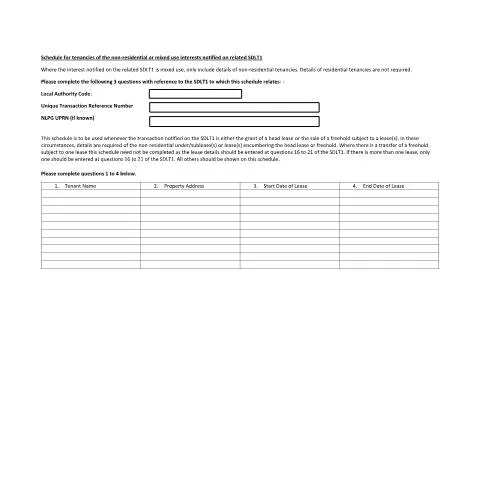
Property transactions involving non-residential or mixed-use properties with existing lease arrangements often trigger additional reporting requirements beyond the standard SDLT1 return. The SDLT Manual 62047 Schedule serves as a crucial supplementary document that captures essential details about underlying tenancies when dealing with complex property structures such as head leases or freehold sales subject to existing leases.
This schedule becomes particularly relevant in commercial property transactions where multiple lease arrangements may exist beneath the primary interest being transferred. Unlike straightforward residential purchases, these transactions require HMRC to understand the complete tenancy structure to assess stamp duty liability accurately and maintain proper records of property interests.
The Strategic Role of Schedule 62047 in Complex Property Structures
The schedule addresses a specific gap in the standard SDLT1 form, which can only accommodate details of one lease arrangement within questions 16 to 21. When property transactions involve multiple underlying leases, the primary form becomes insufficient to capture the full picture of tenancy obligations and rental income streams that may affect stamp duty calculations.
Consider a commercial office building sold as a freehold interest but subject to three separate business tenancies. The SDLT1 can record one lease directly, but the remaining two require documentation through this schedule. This ensures HMRC receives complete information about all non-residential tenancy arrangements that encumber the property interest being transferred.
Mixed-Use Properties: Selective Reporting Requirements
For mixed-use properties containing both residential and commercial elements, the schedule specifically excludes residential tenancies from reporting requirements. This selective approach recognises that residential and non-residential properties face different stamp duty treatment and regulatory oversight.
Property developers and investors dealing with mixed-use developments must therefore carefully categorise each tenancy before completing the schedule. A building containing ground-floor retail units with residential flats above would require reporting of the commercial leases only, streamlining the documentation process whilst maintaining regulatory compliance.
Mandatory Information Fields and Their Strategic Importance
The schedule demands four critical pieces of information for each non-residential tenancy: tenant name, property address, lease start date, and lease end date. These seemingly straightforward requirements serve multiple administrative and analytical purposes within HMRC's property transaction monitoring systems.
| Information Field | Primary Purpose | Secondary Applications |
|---|---|---|
| Tenant Name | Identify lease counterparties | Cross-reference with business records |
| Property Address | Specify exact location of tenancy | Validate against NLPG UPRN data |
| Start Date | Establish tenancy commencement | Calculate remaining term value |
| End Date | Determine lease expiry | Assess long-term property interests |
Tenant Identification and Due Diligence Implications
Recording tenant names serves purposes beyond simple identification. HMRC may use this information to cross-reference business activities and ensure consistency across different tax obligations. For instance, a tenant operating multiple business premises might face scrutiny if their lease arrangements appear inconsistent with their declared business activities or turnover.
Professional advisors should ensure tenant names match exactly with those used in lease documentation and business registration records. Discrepancies could trigger additional enquiries or delay transaction processing, particularly where corporate structures or trading names complicate identification.
Integration with SDLT1 Returns and Transaction References
The schedule cannot exist independently but must link directly to a specific SDLT1 return through three mandatory reference fields: Local Authority Code, Unique Transaction Reference Number, and NLPG UPRN where available. This integration ensures HMRC can associate supplementary lease information with the correct primary transaction.
The Unique Transaction Reference Number, generated during SDLT1 submission, becomes the critical linking mechanism. Without this reference, the schedule lacks context and cannot be processed effectively. This dependency means the primary SDLT1 return must typically be submitted before or simultaneously with any associated schedules.
Local Authority Codes and Geographic Precision
Local Authority Codes serve multiple administrative functions beyond simple geographic identification. These codes enable HMRC to analyse regional property market trends and ensure compliance with local planning and development regulations that might affect stamp duty liability.
Different local authorities may have varying approaches to mixed-use property classification or development incentives that could influence tax treatment. The code system allows HMRC to apply appropriate regional considerations when processing complex property transactions.
Distinguishing Head Lease Grants from Freehold Sales with Existing Leases
The schedule applies to two distinct transaction types that share similar documentation requirements but involve fundamentally different property interests. Understanding this distinction proves crucial for correct application and compliance with reporting obligations.
Head lease grants involve creating a new superior lease interest whilst potentially retaining underlying sublease arrangements. The head lessee assumes responsibility for existing subtenancies, creating a layered property structure that requires comprehensive documentation of all subordinate interests.
Conversely, freehold sales subject to existing leases transfer absolute ownership whilst preserving tenant rights under existing lease agreements. The new freehold owner inherits landlord obligations and benefits but cannot immediately alter existing tenancy terms without following proper legal procedures.
Sublease Hierarchies and Documentation Complexity
Complex property structures involving multiple sublease levels require careful consideration of which arrangements require schedule documentation. The guidance focuses on non-residential under/subleases that encumber the primary interest being transferred, but determining exactly which arrangements meet this criteria can prove challenging.
Professional advisors must trace the complete chain of property interests to identify which leases directly affect the transaction. Subleases granted by existing tenants may not require documentation if they don't materially impact the primary transfer, but this assessment requires detailed legal analysis of the specific property structure.
Practical Application Scenarios and Decision Trees
Different transaction structures trigger varying documentation requirements under the schedule system. Understanding these scenarios helps property professionals determine when schedule completion becomes mandatory and which specific information HMRC requires.
A single lease scenario requires no schedule documentation, as the SDLT1 form can accommodate all necessary lease details within its standard structure. However, multiple lease arrangements immediately trigger schedule requirements, regardless of the individual lease values or terms.
Mixed-Use Property Complications
Mixed-use properties present particular challenges in determining schedule requirements. A building containing both residential and commercial elements might have numerous tenancy arrangements, but only non-residential leases require documentation through the schedule.
Consider a property with six total tenancies: three residential flats, two ground-floor shops, and one basement storage facility used for business purposes. Only the two retail units and business storage arrangement would appear on the schedule, despite the residential tenancies potentially representing significant rental value.
Strategic Considerations for Property Professionals and Investors
The schedule requirements influence transaction planning and due diligence processes for commercial property deals. Professional advisors must factor documentation obligations into transaction timelines and ensure all necessary lease information is available before completion.
Transaction timing becomes particularly important where multiple properties or complex structures are involved. The schedule must be submitted alongside or after the primary SDLT1 return, creating dependencies that could delay completion if not properly managed.
Due Diligence and Information Gathering
Successful schedule completion requires comprehensive lease information that may not be immediately available from standard property searches or vendor disclosures. Buyers and their advisors must specifically request details of all non-residential tenancies, including exact start and end dates that might not appear in basic rent rolls.
Lease documentation quality varies significantly across different property sectors and ownership structures. Older commercial properties or those with informal tenancy arrangements may lack precise date information, requiring additional investigation or legal clarification before schedule completion becomes possible.
Regulatory Compliance and Administrative Efficiency
The schedule system reflects HMRC's broader approach to property transaction monitoring, balancing comprehensive information gathering with practical administrative efficiency. By limiting detailed reporting to transactions involving multiple lease arrangements, the system avoids unnecessary bureaucracy whilst capturing essential data about complex property structures.
This targeted approach recognises that simple property transactions rarely require extensive additional documentation, whilst complex commercial deals involving multiple tenancies justify more detailed reporting requirements. The threshold system ensures resources focus on transactions most likely to require additional scrutiny or analysis.
Professional advisors should view schedule requirements as an opportunity to demonstrate transaction transparency and reduce the likelihood of subsequent HMRC enquiries. Complete and accurate schedule submission can expedite transaction processing and establish positive relationships with tax authorities for future dealings.
The integration between SDLT1 returns and supplementary schedules represents a sophisticated approach to property transaction documentation that serves both immediate administrative needs and longer-term property market analysis. Understanding these requirements and their strategic implications enables more effective transaction planning and regulatory compliance across all levels of commercial property activity.
Computational Methodology and Rate Application Framework
The SDLT Manual 62047 schedule establishes a sophisticated computational framework that extends beyond basic rate tables to encompass complex calculation scenarios requiring specialist interpretation. The methodology distinguishes between linear progression calculations for standard residential transactions and multi-tiered assessments for mixed-use developments where both residential and commercial elements coexist within a single purchase.
For residential transactions, the schedule mandates a slice-by-slice calculation approach where each portion of the consideration falls within distinct rate bands. A property purchased for £750,000 would incur no SDLT on the first £250,000, 5% on the portion between £250,001 and £925,000 (calculated as £500,000 × 5% = £25,000), resulting in total liability of £25,000. This differs markedly from a flat rate application across the entire consideration.
Commercial property calculations under the schedule follow separate rate structures, with the 2% rate applying to consideration between £150,001 and £250,000, and 5% on amounts exceeding £250,000. Mixed-use transactions require apportionment between residential and commercial elements, with HMRC guidance under Manual 62047 requiring detailed valuations to establish fair allocation of consideration between different property types within the same transaction.
The schedule addresses computational complexities arising from linked transactions, where multiple property purchases forming part of a single arrangement or series of arrangements require aggregation for rate determination purposes. This prevents artificial fragmentation of large developments into smaller transactions to avoid higher rate bands. Professional advisers must maintain detailed records demonstrating how linked transaction rules apply, particularly where purchases occur across different tax years or involve multiple legal entities within the same corporate structure.
Timing considerations within the computational framework prove crucial for transactions spanning the schedule's effective dates. Where contracts exchange before implementation but complete afterwards, transitional provisions may apply, requiring careful analysis of which rate structure governs the final calculation. The schedule provides specific guidance on determining the relevant effective date for computational purposes, particularly where conditional contracts or options to purchase create uncertainty about completion timing.
Documentation Requirements and Compliance Verification
Manual 62047 schedule imposes comprehensive documentation requirements extending beyond the standard SDLT return submission, establishing an audit trail supporting rate calculations and exemption claims. These requirements recognise that complex transactions often involve multiple parties, sophisticated financing arrangements, and cross-border elements requiring enhanced scrutiny to prevent avoidance or ensure correct application of international provisions.
Primary documentation must include detailed completion statements showing consideration breakdown, particularly where chattels, fixtures, or services form part of the overall transaction value. The schedule requires clear identification of VAT treatment, as this affects the chargeable consideration calculation. Professional fees, stamp duty, and other transaction costs generally fall outside chargeable consideration, but the boundaries require careful documentation where advisory services relate directly to property enhancement or development potential.
For transactions involving non-UK residents, additional documentation requirements under the schedule include evidence of tax residence status, particularly where different rate structures apply. This extends to beneficial ownership disclosure where corporate vehicles or trust structures hold property interests. HMRC's enhanced compliance approach requires transparency about ultimate beneficial ownership, with the schedule providing specific guidance on acceptable evidence standards for different entity types.
Valuation documentation assumes particular importance where transactions involve part-exchanges, transfers between connected parties, or consideration including non-monetary elements. The schedule requires professional valuations meeting RICS standards where market value determinations affect SDLT calculations. This includes scenarios where agricultural land receives development potential, requiring before-and-after valuations to establish the chargeable consideration properly.
Record retention requirements under the schedule extend beyond the standard six-year period for complex transactions involving ongoing compliance obligations. Where reliefs or exemptions apply subject to future conditions—such as property development completion within specified timeframes—documentation must demonstrate continuous compliance with qualifying conditions. This creates ongoing compliance burdens for developers and investors requiring systematic record management approaches.
The schedule addresses digital submission requirements, recognising that complex transactions generate substantial supporting documentation. HMRC's digital transformation agenda requires electronic submission capabilities while maintaining document integrity and security standards. Professional advisers must establish systems ensuring compliance with both SDLT reporting deadlines and broader digital record-keeping obligations under Making Tax Digital initiatives.
International Transactions and Cross-Border Compliance
The SDLT Manual 62047 schedule provides comprehensive guidance for international transactions involving UK property, addressing the complexities arising from cross-border investment structures, foreign currency considerations, and interaction with overseas tax systems. These provisions reflect the significant international investment in UK property markets and the need for clear compliance frameworks preventing both double taxation and avoidance opportunities.
Foreign currency transactions require conversion to sterling using prescribed exchange rates, typically the spot rate prevailing on the effective date of the transaction. However, the schedule addresses complications where consideration involves foreign currency loans, deferred payment terms, or hedging arrangements affecting the ultimate sterling equivalent. Professional advisers must maintain detailed records of exchange rate calculations, particularly where fluctuations between contract and completion dates materially affect SDLT liability.
Non-UK resident purchasers face additional compliance obligations under the schedule, including enhanced rate structures for certain residential properties and specific reporting requirements for beneficial ownership disclosure. The 2% additional rate for non-UK residents purchasing residential property creates computational complexities where purchaser residence status changes between contract exchange and completion, requiring careful analysis of the relevant determining factors under the schedule's guidance.
Corporate structures involving overseas entities require detailed analysis under the schedule's provisions addressing indirect ownership and control tests. Where UK property sits within complex international holding structures, determining the correct rate application requires tracing beneficial ownership through multiple jurisdictions, each with different transparency and disclosure requirements. The schedule provides guidance on acceptable evidence standards while recognising practical limitations in obtaining comprehensive ownership information from certain overseas jurisdictions.
Treaty provisions may affect SDLT treatment where double taxation agreements contain specific property taxation clauses. The schedule addresses interaction between SDLT and overseas stamp duty or transfer tax systems, though relief typically requires specific treaty provisions rather than general double taxation relief principles. Professional advisers must analyse applicable treaties carefully, as property taxation provisions often contain specific conditions and limitations not found in income tax treaty articles.
Trust structures involving international elements create particular complexities under the schedule, especially where settlors, trustees, or beneficiaries span multiple jurisdictions with different legal concepts of property ownership. The schedule addresses situations where overseas trust law creates beneficial interests not recognised under English law, requiring careful analysis of substance over form principles to determine correct SDLT treatment. This extends to Islamic finance structures and other arrangements where religious or cultural legal principles create property interests differing from conventional English law concepts.