Understanding Scotland's Corrective Estate Process After Confirmation
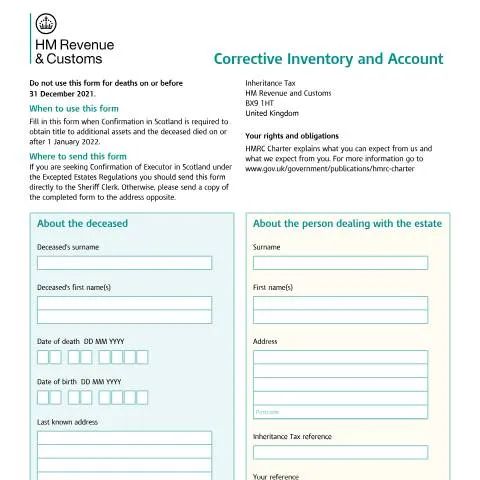
When dealing with a deceased person's estate in Scotland, the initial Confirmation process rarely tells the complete story. Assets emerge from forgotten bank accounts, property valuations shift, or debts surface that weren't apparent during the original application. The Corrective Inventory and Account for Scotland (Form C4(S)) serves as the essential mechanism for executors to formally amend their original estate declaration when new information comes to light after Confirmation has been granted.
This specialised form applies exclusively to deaths occurring on or after 1 January 2022, reflecting recent changes to Scotland's succession law framework. Unlike routine administrative corrections, this document requires careful preparation as it directly impacts both the estate's tax liability and the executor's legal standing with HM Revenue and Customs.
When Amendments Become Necessary: The Trigger Points
The need for a corrective inventory typically arises in several distinct scenarios, each requiring different approaches to documentation. Discovery of additional assets represents the most common trigger, particularly when executors uncover previously unknown bank accounts, insurance policies, or shareholdings after the original Form C1(2022) submission.
Property revaluations constitute another frequent catalyst for corrections. Market fluctuations between the date of death and the completion of estate administration can result in significant valuation discrepancies. Similarly, professional revaluations of artwork, jewellery, or business interests may reveal substantial differences from initial estimates used in the original inventory.
Debt adjustments also necessitate corrective action. Creditors may present claims after Confirmation, or conversely, disputed debts included in the original calculation may prove invalid. The form accommodates both increases and decreases in liabilities, ensuring the final estate valuation reflects all legitimate obligations.
Excepted Estate Status Complications
Executors dealing with estates initially processed under the Excepted Estates Regulations face particular complexity. If corrections push the estate value beyond excepted estate thresholds, the entire case transfers from the Sheriff Clerk's jurisdiction to HMRC's direct oversight. This transition triggers additional compliance requirements and potentially extends processing timeframes significantly.
Navigating the Dual Submission Pathways
The form's routing depends critically on whether the corrected estate maintains its excepted estate status. This determination shapes not only where to submit the documentation but also influences the level of scrutiny the corrections will receive.
| Estate Status | Submission Destination | Processing Authority | Additional Requirements |
|---|---|---|---|
| Remains Excepted Estate | Sheriff Clerk directly | Local Sheriff Court | Standard Confirmation procedures apply |
| No longer Excepted Estate | HMRC Inheritance Tax BX9 1HT | HM Revenue and Customs | Full inheritance tax assessment may be required |
Executors must carefully evaluate the cumulative effect of all corrections before determining the appropriate submission route. The excepted estate threshold for 2024 stands at £325,000 for the nil rate band, though additional allowances may apply for transfers between spouses or the residence nil rate band.
Sheriff Clerk Coordination Requirements
When submitting to the Sheriff Clerk, executors must ensure their corrections align with existing Confirmation records. The court requires specific declarations confirming that the additional inventory represents a complete account of newly discovered assets. This process involves updating the original court books entry, potentially affecting the scope of the executor's authority over estate assets.
Detailed Asset and Liability Reconciliation Process
The form's core functionality revolves around systematic reconciliation of the original estate declaration. Executors must categorise corrections into distinct sections: asset increases, asset decreases, liability increases, and liability decreases. Each category requires specific documentation approaches and impacts the final tax calculation differently.
Asset increases encompass newly discovered property, upward revaluations, or assets initially omitted from the original inventory. The form requires executors to use identical descriptions to those employed in the original Form C1(2022), maintaining consistency for administrative tracking purposes. Assets must be listed in prescribed geographical order: Scotland (heritable estate first), England and Wales, Northern Ireland, then overseas assets.
Liability adjustments demand particular attention to supporting documentation. New debts require creditor verification, while liability reductions need clear evidence of the changed circumstances. The form's calculation methodology ensures that net changes in both assets and liabilities feed directly into the revised inheritance tax assessment.
Continuation Page Management
Complex estates frequently require additional space beyond the standard form allocation. The companion Form C4(S)(C) continuation pages integrate seamlessly with the main document, though executors must ensure totals transfer accurately between pages. Each continuation page requires the same level of detail and verification as the primary form sections.
Multiple Executor Coordination and Signature Requirements
Scottish succession law frequently involves multiple executors, creating coordination challenges for corrective inventory preparation. The form accommodates up to six executor signatures, though all named executors need not sign if they've formally delegated authority to acting executors.
Each signatory assumes personal liability for the accuracy and completeness of the corrections presented. This responsibility extends beyond mere oversight to active verification of the amended information. Executors must understand that penalties for false information apply individually, regardless of collective decision-making processes.
The declaration section requires each executor to confirm their understanding of potential prosecution risks for providing false information. This represents a significant legal commitment, particularly given that corrective inventories often involve complex valuation disputes or previously contested assets.
Professional Representation Considerations
While the form permits executor self-completion, the complexity of inheritance tax calculations and the legal implications of corrections frequently warrant professional assistance. Solicitors specialising in Scottish succession law can navigate the technical requirements while ensuring compliance with both HMRC expectations and Sheriff Court procedures.
Tax Calculation Integration and Repayment Mechanisms
The corrective inventory directly interfaces with inheritance tax calculations, potentially triggering additional payments or generating refunds. The form's summary section requires executors to reference their original IHT400 submission or the most recent HMRC calculation, ensuring continuity in tax assessment processes.
When corrections result in reduced estate values, executors may qualify for inheritance tax repayments. The integrated repayment section facilitates direct bank transfers using Faster Payments, with transactions identified by the estate's inheritance tax reference number. Account details must be provided accurately to avoid processing delays or misdirected funds.
Conversely, corrections increasing estate values may generate additional tax liabilities. HMRC typically issues revised calculations within 15 working days of receiving properly completed corrective inventories, though complex cases involving multiple corrections may require extended processing periods.
Interest and Penalty Implications
Late discovery of assets doesn't automatically trigger penalties, provided executors demonstrate reasonable diligence in the original estate investigation. However, interest charges may apply to additional inheritance tax from the original due date, typically six months after the end of the month of death.
Post-Submission Tracking and Administrative Follow-Up
After submission, executors should retain comprehensive records of all corrective documentation. HMRC's processing systems generate acknowledgment correspondence, though response timeframes vary depending on submission route and estate complexity.
Sheriff Clerk submissions typically receive faster processing for straightforward corrections, particularly when estates remain within excepted estate parameters. The local court's familiarity with the original Confirmation application can expedite review processes, though executors should allow 10-15 working days for standard cases.
HMRC submissions enter the broader inheritance tax processing system, potentially involving specialist review teams for complex corrections. Executors can track progress using their inheritance tax reference number, though telephone enquiries should reference specific correction details to facilitate efficient case handling.
Amendment Rejection and Appeal Procedures
HMRC may reject corrections that appear incomplete or inconsistent with available records. Common rejection reasons include insufficient supporting documentation, mathematical errors in calculations, or attempts to amend items outside the corrective inventory's scope.
Rejected submissions require complete resubmission rather than partial corrections. Executors should address all identified deficiencies simultaneously to avoid multiple rejection cycles. The appeals process for disputed corrections follows standard inheritance tax appeal procedures, potentially involving tribunal hearings for complex valuation disputes.
Integration with Broader Scottish Succession Procedures
The corrective inventory represents one component within Scotland's comprehensive succession framework. Its completion may trigger requirements for additional legal documentation, particularly when corrections affect heritable property or business interests requiring separate legal transfers.
Executors must coordinate corrective inventory timing with ongoing estate administration activities. Property sales, debt settlements, or beneficiary distributions may be affected by pending corrections, requiring careful sequencing to avoid legal complications or unnecessary delays.
The form's integration with digital government services continues evolving, with HMRC developing enhanced online submission capabilities for Scottish estates. However, the current paper-based system remains the primary mechanism for most corrective inventories, requiring traditional postal submission and manual processing workflows.
Understanding these procedural intricacies ensures executors can navigate the corrective inventory process efficiently while maintaining compliance with both inheritance tax obligations and Scottish succession law requirements. The form's technical complexity reflects the sophisticated legal framework governing estate administration, emphasising the importance of thorough preparation and accurate documentation throughout the correction process.
Specific Scottish Legal Framework and Devolved Considerations
Whilst Inheritance Tax remains a reserved matter under the Scotland Act 1998, meaning it falls under UK-wide HMRC jurisdiction rather than Revenue Scotland, the Scottish legal system introduces distinctive elements that can significantly impact corrective inventory procedures. The fundamental difference lies in Scotland's separate legal tradition, where concepts like 'confirmation' replace 'probate', and heritable property follows different succession rules.
Under Scots law, the executor must obtain confirmation from the Sheriff Court before distributing the estate. This process runs parallel to, but separate from, the IHT account submission to HMRC. When preparing a corrective inventory, executors must ensure consistency between the confirmation inventory lodged with the Sheriff Court and the amended IHT account. Discrepancies between these documents can trigger both HMRC queries and potential Sheriff Court complications.
Scottish agricultural property presents particular complexities for corrective inventories. The Agricultural Holdings (Scotland) Act 2003 and Land Reform (Scotland) Act 2016 create specific tenancy arrangements and succession rights that may not have been fully captured in the original IHT account. For instance, secure 1991 Act tenancies carry different valuation implications compared to limited duration tenancies or modern limited partnerships. When agricultural property relief (APR) was initially claimed incorrectly due to misunderstanding these Scottish-specific tenure arrangements, the corrective inventory must provide detailed legal analysis of the actual tenancy structure.
The Scottish system of legal rights—including legitim for children and jus relictae/jus relicti for surviving spouses—can affect IHT calculations in ways that differ markedly from English law. These rights exist regardless of will provisions and may create additional liabilities or reliefs that weren't apparent in the original account. A corrective inventory might need to address situations where legal rights claims have been made after the initial IHT submission, potentially altering both the taxable estate value and available exemptions.
Scottish partnerships, particularly those involving agricultural or business assets, operate under the Partnership Act 1890 as interpreted through Scots law. The presumption that partnership assets belong to the partnership rather than individual partners can affect business property relief claims. Corrective inventories frequently need to address misclassifications between personal assets and partnership interests, especially where the deceased held both partnership shares and separate business assets.
Valuation Challenges and Expert Assessment Requirements
The requirement for accurate asset valuation in corrective inventories often necessitates engaging multiple specialist valuers, each bringing sector-specific expertise that may not have been available during the initial account preparation. HMRC's Inheritance Tax Manual provides detailed guidance on acceptable valuation methods, but practical application can be considerably more complex than the guidance suggests.
Property valuations present recurring challenges, particularly for unique or specialist properties where comparable sales data may be limited. Scottish castles, historic houses, or properties with unusual restrictions require expert valuers familiar with both the Scottish property market and heritage considerations. The corrective inventory must demonstrate why the revised valuation differs from the original assessment, providing detailed methodology and supporting evidence. This might include recent comparable sales that weren't available initially, structural surveys revealing previously unknown defects, or planning restrictions that have since come to light.
Business valuations for family companies often require retrospective analysis of trading conditions, market circumstances, and specific discount factors that may not have been properly considered initially. The corrective inventory must address whether any changes result from new information about the business's financial position or from improved understanding of appropriate valuation methodology. For instance, if the original valuation failed to apply appropriate marketability discounts for minority shareholdings in family companies, the corrective account must explain both the theoretical basis for such discounts and their specific application to the deceased's holding.
Chattels and personal possessions frequently present valuation difficulties, especially where items have cultural, historical, or collector significance beyond their apparent market value. Scottish cultural items—such as clan regalia, historical weapons, or items with specific Highland heritage—may require specialist Scottish valuers familiar with these particular markets. The corrective inventory process might reveal that items initially dismissed as having minimal value actually represent significant assets requiring detailed professional assessment.
Agricultural assets present ongoing valuation challenges, particularly where farming operations span both commercial activities and sporting rights. Scottish estates often combine traditional farming with shooting, fishing, and renewable energy enterprises, each requiring separate valuation expertise. The corrective inventory might need to address whether sporting rights were properly valued initially, whether renewable energy installations were correctly categorised as plant and machinery or land improvements, and whether diversification activities affect the availability of agricultural property relief.
Intellectual property and digital assets represent emerging areas where initial valuations may prove inadequate. This could include copyrights in literary or artistic works, trademark rights in family businesses, or digital assets including cryptocurrency holdings. The corrective inventory must address both the technical valuation challenges and any subsequent changes in market conditions that might affect these asset values. For Scottish-based creative professionals or technology entrepreneurs, this might involve complex analysis of royalty streams, licensing arrangements, or international intellectual property portfolios.
International Assets and Cross-Border Complications
Scottish estates with international dimensions present particularly complex challenges for corrective inventories, especially where the deceased maintained connections with multiple jurisdictions through residence, business interests, or family relationships. The interaction between UK Inheritance Tax and foreign tax systems can create situations where the original IHT account failed to capture the full scope of international obligations or available reliefs.
Double taxation agreements between the UK and other countries provide mechanisms for avoiding duplicate taxation, but their application requires detailed understanding of both UK rules and foreign tax systems. A corrective inventory might need to address situations where foreign tax liabilities were initially underestimated, where double taxation relief was incorrectly calculated, or where changes in foreign exchange rates significantly affect asset values. For instance, if the deceased held substantial US dollar assets and sterling depreciated significantly between death and the corrective inventory, this could materially affect both the UK tax liability and any US estate tax obligations.
Scottish connections to Commonwealth countries, particularly Canada, Australia, and New Zealand, often involve complex property holdings that may not have been fully understood initially. These might include family trusts established under foreign law, pension arrangements that don't translate easily into UK concepts, or property held through corporate structures designed for foreign tax efficiency. The corrective inventory process must unravel these arrangements to determine their proper UK tax treatment whilst ensuring compliance with foreign reporting requirements.
European Union considerations, despite Brexit, continue to affect estates with pre-Brexit EU connections or ongoing business operations across European borders. The corrective inventory might need to address how Brexit has affected asset values, whether previously available EU tax reliefs remain applicable, or how ongoing European business operations should be valued in the post-Brexit environment. For Scottish businesses with traditional European connections—particularly in sectors like whisky production, financial services, or renewable energy—these considerations can be material.
Offshore structures present recurring complications where the original IHT account may have mischaracterised the deceased's relationship with foreign companies, trusts, or foundations. The corrective inventory must address whether the deceased had sufficient control or benefit to bring these structures within the UK tax net, applying complex rules around foreign domicile, excluded property status, and beneficial ownership. This analysis often requires detailed legal advice on both UK and foreign law, particularly where structures were established many years previously under different tax regimes.
Foreign immovable property presents specific challenges where local legal requirements, valuation methods, or market conditions differ substantially from UK norms. Scottish executors dealing with foreign property must navigate local succession laws, obtain appropriate valuations using locally accepted methods, and ensure proper integration with the UK IHT account. The corrective inventory might need to address situations where local legal requirements have delayed property transfers, where local taxes affect net values, or where political or economic instability has affected property values since death.