When Property Development Meets VAT Complexity: The Certificate to Disapply
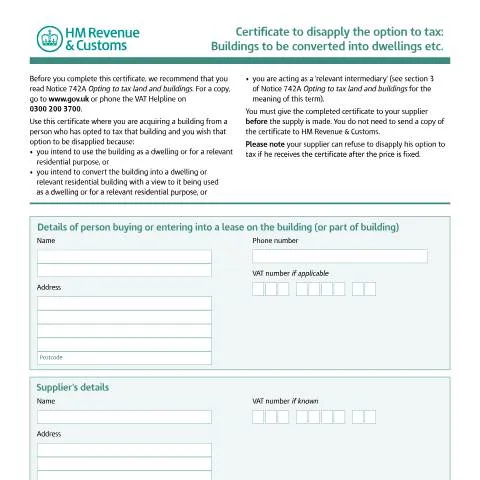
In the intricate world of VAT on property transactions, developers and purchasers regularly encounter a peculiar administrative hurdle: dealing with buildings where the seller has previously "opted to tax". This election, once made, typically transforms what would be VAT-exempt property sales into standard-rated supplies at 20%. However, when residential development enters the equation, HMRC provides a specific escape route through the Certificate to disapply the option to tax (VAT1614D), a document that can fundamentally alter the financial dynamics of property acquisitions destined for housing.
This certificate operates within the complex intersection of Schedule 10 to the VAT Act 1994 and represents more than mere paperwork—it's a statutory mechanism that can save developers substantial sums whilst ensuring compliance with residential property VAT reliefs. Understanding its proper application becomes crucial for anyone navigating property conversions, residential developments, or acting as intermediaries in such transactions.
The Statutory Framework Behind Disapplying VAT Elections
The certificate derives its authority from paragraph 6 of Schedule 10 to the VAT Act 1994, which establishes three distinct conditions under which a VAT election can be disapplied. This legislative framework recognises that applying standard VAT rates to properties ultimately destined for residential use would create unnecessary tax burdens and administrative complications.
When a property owner makes an option to tax election, they're essentially choosing to treat their property supplies as standard-rated rather than exempt. This election typically remains in force for 20 years and covers all future supplies of that property. However, the disapplication mechanism acknowledges that residential use represents a legitimate exception to this general rule.
The Three Qualifying Conditions
The certificate accommodates three specific scenarios where disapplication becomes permissible:
- Direct residential use: The purchaser intends to use the building as dwellings or for relevant residential purposes
- Conversion projects: The purchaser plans to convert the building into residential accommodation
- Relevant intermediary arrangements: The purchaser acts as an intermediary, ultimately disposing of the property to someone meeting the residential criteria
Each condition carries specific evidential requirements and legal obligations, with the certificate serving as the formal declaration of compliance with these statutory tests.
Practical Applications Across Property Development Scenarios
The certificate finds application across diverse property development contexts, each presenting unique considerations and timing requirements. Commercial-to-residential conversions represent perhaps the most common scenario, where developers acquire former office buildings, warehouses, or retail premises with elected VAT status for transformation into housing.
Office Conversion Projects
Consider a developer acquiring a 1980s office block where the previous owner elected to tax. Without the certificate, the acquisition would attract 20% VAT on the full purchase price. For a £2 million acquisition, this represents £400,000 in additional costs. The certificate enables the developer to disapply this election, provided they can demonstrate genuine conversion intentions and compliance with planning requirements.
Mixed-Use Development Challenges
Where developments involve partial residential conversion, the certificate requires precise description of the residential portion. The form specifically requests percentage calculations based on floor space, creating practical challenges for developers working with complex architectural plans. This precision requirement reflects HMRC's need to prevent abuse whilst accommodating legitimate mixed-use projects.
| Development Type | Certificate Requirements | Key Considerations |
|---|---|---|
| Full residential conversion | Complete building description | Planning permission alignment |
| Partial residential conversion | Precise floor space percentages | Clear demarcation of residential areas |
| Intermediary arrangements | Onward disposal evidence | Chain of certificates required |
Timing Imperatives and Commercial Negotiations
The certificate's effectiveness hinges entirely on timing compliance. HMRC's guidance explicitly states that suppliers can refuse disapplication if they receive the certificate after the price is fixed. This creates significant commercial pressure and requires careful coordination between purchasers, suppliers, and their respective advisers.
In practice, this timing requirement often influences heads of terms negotiations, with purchasers seeking to include certificate acceptance as a condition precedent. Sophisticated transactions may incorporate specific warranty provisions regarding the supplier's obligation to accept valid certificates presented within agreed timeframes.
Price Negotiation Dynamics
The potential for VAT disapplication frequently affects initial price negotiations. Sellers with elected properties may quote prices exclusive of VAT, anticipating certificate presentation, whilst purchasers must evaluate acquisition costs under both scenarios. This uncertainty can complicate financial modelling and requires careful legal drafting to address various outcomes.
Due Diligence Requirements and Supporting Evidence
Completing the certificate demands thorough preparation and supporting documentation, though the form itself travels only between purchaser and supplier. However, prudent practice suggests maintaining comprehensive records to support any future HMRC enquiries or disputes.
Planning Permission Alignment
Planning permission consistency represents a critical consideration. The certificate's residential use declarations must align with granted or anticipated planning consents. Discrepancies between certificate declarations and planning documentation could trigger HMRC scrutiny and potentially invalidate the disapplication.
Conversion Timeline Evidence
For conversion projects, maintaining detailed project timelines, architectural plans, and contractor agreements strengthens the certificate's supporting evidence base. The legislation specifically excludes arrangements where non-qualifying use is intended before residential conversion, making timeline documentation particularly important for phased developments.
Intermediary Arrangements and Certificate Chains
The relevant intermediary provision creates sophisticated structuring opportunities whilst imposing additional administrative burdens. Under this arrangement, an intermediary can issue a certificate based on receiving a corresponding certificate from their intended purchaser, creating a chain of residential use commitments.
This mechanism particularly benefits development finance arrangements where funders temporarily hold property interests before disposal to residential developers. However, each link in the certificate chain must satisfy the statutory conditions, and break-downs can jeopardise the entire arrangement's VAT treatment.
Documentation Requirements for Intermediaries
Intermediaries must retain evidence of their onward disposal intentions and the downstream certificate supporting their own declaration. This creates practical challenges where disposal arrangements remain subject to planning outcomes or market conditions, requiring careful legal structuring to maintain compliance throughout development timescales.
Compliance Responsibilities and Penalty Risks
The certificate carries significant personal liability implications for signatories. HMRC's warnings emphasise potential penalty exposure for false certificates, with the responsible individual bearing personal accountability regardless of corporate structure or professional advice received.
These penalties operate under HMRC's general penalty regime, potentially reaching substantial amounts where deliberate inaccuracy is established. The legislation's emphasis on intended use rather than guaranteed outcomes provides some protection for genuine commercial uncertainties, but requires careful consideration of realistic development prospects.
Record Keeping Best Practices
Maintaining comprehensive contemporaneous records becomes essential given the certificate's self-certification nature. Key documentation includes:
- Planning application materials and correspondence
- Architectural drawings and conversion specifications
- Project timelines and development appraisals
- Board minutes or partnership decisions regarding intended use
- Professional advice received regarding VAT treatment
Navigating Disputes and Challenging Supplier Refusals
Suppliers occasionally refuse certificate acceptance, either through misunderstanding the legislation or attempting to preserve their VAT election benefits. Such refusals can derail development finances and require prompt resolution through negotiation or legal intervention.
The legislation provides no explicit enforcement mechanism compelling certificate acceptance, leaving purchasers reliant on contractual remedies or dispute resolution procedures. This emphasises the importance of incorporating appropriate protection within acquisition agreements and ensuring legal documentation addresses potential certificate disputes.
Alternative Structuring Considerations
Where certificate acceptance appears problematic, alternative structuring options merit consideration. These might include conditional contracts dependent upon certificate acceptance, price adjustment mechanisms reflecting VAT uncertainty, or alternative acquisition structures avoiding opted properties entirely.
However, such alternatives often carry their own complications and costs, reinforcing the value of early engagement with suppliers regarding certificate procedures and ensuring all parties understand their respective obligations under the VAT legislation.
Common Scenarios Requiring Disapplication Certificates
Understanding when businesses typically need to disapply the option to tax helps illustrate the practical applications of this VAT provision. The certificate becomes particularly relevant in several recurring commercial situations that property owners and investors encounter.
Property development and conversion projects represent one of the most frequent scenarios. When a developer acquires an opted building with plans for residential conversion, they must secure disapplication before commencing work. This prevents the automatic VAT charge on construction services that would otherwise apply to an opted property. The timing proves critical—applications submitted after work begins face rejection, potentially leaving developers liable for VAT on substantial construction costs.
Commercial property sales between VAT-registered businesses create another common requirement. If a seller has opted a building for VAT purposes but the purchaser intends different usage—perhaps converting from commercial lettings to owner-occupation—the sale contract often includes provisions requiring the seller to obtain disapplication. This protects the buyer from inheriting an unwanted VAT election that could affect their future property dealings.
Portfolio restructuring by property investment companies frequently triggers disapplication needs. When investors reorganise their holdings or prepare properties for sale to non-VAT registered buyers, removing the option to tax election becomes essential. Investment funds particularly encounter this when disposing of assets to pension schemes or other exempt entities that cannot recover VAT.
Landlords switching from commercial to residential lettings must also consider disapplication. While residential lettings remain VAT-exempt, retaining the option to tax election on a building being converted to residential use can create complications for future transactions. The certificate provides certainty that the property's VAT status aligns with its intended use.
Corporate restructuring scenarios often necessitate disapplication certificates. During mergers, acquisitions, or business transfers, companies may need to align the VAT status of their property portfolios. The certificate ensures that transferred buildings don't carry unwanted VAT elections that could disadvantage the acquiring entity.
Inheritance situations can also require disapplication. When opted commercial properties pass to beneficiaries who lack VAT registration or intend different property uses, obtaining the certificate prevents future complications. Estate administrators should consider this aspect when managing commercial property inheritances.
Strategic Timing and Commercial Considerations
The timing of disapplication applications carries significant commercial implications that extend beyond mere administrative compliance. Property professionals must carefully coordinate certificate applications with broader transaction timelines and commercial objectives.
Pre-contract positioning often determines application timing. In property sales, purchasers typically require sellers to obtain disapplication certificates before exchange of contracts. This creates certainty about the property's VAT status and prevents completion delays. However, sellers must balance this requirement against HMRC processing times, which can extend several weeks during busy periods.
Market conditions can influence disapplication decisions. During periods of high transaction activity, HMRC processing times may extend, affecting deal timelines. Experienced property advisers often recommend initiating applications well in advance of anticipated completion dates, particularly for complex transactions involving multiple properties or unusual circumstances.
Tax year considerations add another timing dimension. Businesses planning significant property transactions around the tax year end (5 April) should factor in potential HMRC delays during this busy period. Applications submitted in March may not receive responses until after the new tax year begins, potentially affecting accounting treatments and cash flow planning.
The irrevocable nature of disapplication creates strategic implications. Once HMRC issues a certificate, the property owner cannot subsequently elect to tax the same building. This permanence requires careful consideration of future business plans and potential changes in property use or ownership structure.
Portfolio management strategies often involve phased disapplication approaches. Large property holders may stagger applications across their portfolios to maintain flexibility while achieving specific commercial objectives. This approach allows businesses to test market responses and refine their strategies before committing entire portfolios to disapplication.
Financial planning must account for the VAT implications of disapplication timing. Removing the option to tax election affects input tax recovery on future expenditure related to the property. Businesses should model these impacts when planning major refurbishment or development projects, ensuring that disapplication timing optimises overall VAT positions.
Lease renewal negotiations can also influence disapplication timing. Landlords may coordinate certificate applications with lease restructuring to achieve specific commercial outcomes, such as offering VAT-free rentals to attract exempt sector tenants while maintaining flexibility for future lettings.
Integration with Broader VAT Compliance Obligations
Disapplication certificates don't exist in isolation but form part of comprehensive VAT compliance frameworks that property businesses must navigate. Understanding these interconnections helps ensure that certificate applications align with broader tax strategies and regulatory requirements.
VAT return implications begin immediately upon certificate issue. Businesses must adjust their VAT accounting to reflect the changed status, ensuring that future property-related transactions receive appropriate VAT treatment. This includes reviewing standing data in accounting systems and updating procedures for handling property income and expenditure.
The relationship with partial exemption calculations requires particular attention. Property businesses often straddle exempt and taxable activities, making input tax recovery calculations complex. Disapplication can alter these calculations by changing the VAT status of property-related income streams. Regular partial exemption reviews should incorporate disapplication effects to ensure continued compliance.
Capital goods scheme obligations may continue despite disapplication. If a business previously claimed input tax on property acquisition or improvement under the capital goods scheme, the annual adjustments continue for the full adjustment period. Disapplication doesn't terminate these obligations, though it may affect future adjustment calculations.
Group VAT registration considerations become relevant for corporate property holders. Disapplication by one group member can affect the group's overall VAT position, particularly regarding cost sharing arrangements and intra-group supplies. Group VAT representatives should coordinate disapplication decisions across all relevant entities.
Transfer of going concern (TOGC) rules interact with disapplication in property sales. When opted properties form part of a business transfer that qualifies as a TOGC, the VAT election typically transfers with the business. However, if the seller obtains disapplication before transfer, this can affect TOGC eligibility and the transaction's VAT treatment.
International aspects may arise for businesses with cross-border property interests. While UK disapplication certificates only affect UK VAT obligations, property businesses with international operations should consider how UK disapplication decisions might interact with foreign tax obligations or double taxation treaty provisions.
Record-keeping requirements extend beyond the certificate itself. Businesses must maintain comprehensive documentation supporting their disapplication decisions, including evidence of the circumstances necessitating disapplication and records of how the changed VAT status affects ongoing compliance obligations. These records prove essential during VAT inspections or when addressing subsequent HMRC enquiries.
The interaction with Making Tax Digital obligations requires ongoing attention. Property businesses subject to MTD requirements must ensure their digital records accurately reflect disapplication effects, including appropriate coding of property transactions and maintenance of the audit trail connecting certificate applications to subsequent VAT treatments.