When UK Pension Transfers Cross International Borders
Moving pension benefits from a UK registered scheme to an overseas arrangement involves far more than simply requesting a transfer. The APSS263 form sits at the heart of this complex process, serving as a critical information bridge between pension scheme members and their administrators when transferring to a Qualifying Recognised Overseas Pension Scheme (QROPS). This document becomes essential the moment someone decides to relocate their pension pot internationally, whether they're emigrating permanently or seeking better investment opportunities abroad.
The form's existence stems from HMRC's need to maintain oversight of UK pension assets even after they leave British shores. Unlike domestic transfers that remain within familiar regulatory boundaries, international pension movements trigger specific tax implications and reporting requirements that can persist for years after the initial transfer.
The 60-Day Deadline That Shapes Everything
The most critical aspect of the APSS263 process centres on an unforgiving 60-day deadline. From the moment you submit your transfer request to your scheme administrator, this countdown begins ticking. Miss this window, and your transfer automatically becomes subject to the overseas transfer charge—a punitive tax that can significantly erode your pension value.
This deadline creates a practical urgency that distinguishes QROPS transfers from other pension arrangements. While domestic transfers typically allow for leisurely consideration, international moves demand swift action and precise information gathering. The scheme administrator cannot proceed without this completed form, creating a bottleneck that has caught many transferees off guard.
The 60-day rule reflects HMRC's recognition that overseas transfers require enhanced due diligence. During this period, administrators must verify the receiving scheme's QROPS status, confirm member details, and ensure all tax obligations are properly addressed before releasing funds.
Dissecting the Member Information Requirements
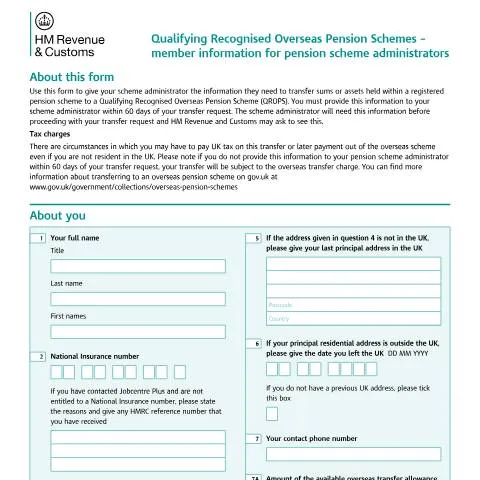
The form's structure reveals the comprehensive data trail HMRC requires for overseas pension movements. The opening section focuses intensively on personal identification, but with specific nuances that reflect international contexts.
Identity and Address Complications
Question 4 demands your principal residential address, but explicitly prohibits using the scheme manager's address or PO Box numbers unless country-specific circumstances necessitate them. This restriction addresses common attempts to obscure actual residence status, which directly impacts tax liability.
The address requirements become particularly complex for individuals who have already relocated. Questions 5 and 6 create a geographic timeline, requiring both your last UK address and the specific date you left the country. This information enables HMRC to establish residence patterns that influence tax treatment both at transfer and for future payments.
National Insurance Number Exceptions
While most UK pension holders possess National Insurance numbers, question 2 acknowledges exceptions. Individuals who have contacted Jobcentre Plus but been deemed ineligible must explain their circumstances and provide any HMRC reference numbers received. This provision typically applies to certain categories of overseas workers or individuals with complex immigration histories.
The Overseas Transfer Allowance Mystery
Question 7A introduces the concept of "available overseas transfer allowance," requiring a specific monetary amount. This allowance system operates as a lifetime limit on certain types of overseas transfers, though the form itself doesn't specify the current threshold. Members must obtain this figure from their scheme administrator or HMRC records, as incorrect amounts can invalidate the entire process.
Decoding QROPS Classifications and Their Consequences
The middle section of APSS263 navigates the complex taxonomy of overseas pension schemes, with each classification triggering different procedural paths and tax implications.
| QROPS Type | Key Identifier | Form Path | Employment Details Required |
|---|---|---|---|
| Occupational Pension Scheme | Employer-sponsored arrangement | Skip to Question 15 | Yes - Full employment history |
| Overseas Public Service Scheme | Government/public sector connection | Skip to Question 15 | Yes - Full employment history |
| International Organisation | Supranational body affiliation | Skip to Question 15 | Yes - Full employment history |
| Other QROPS | Commercial/individual arrangements | Skip to Question 21 | No employment details needed |
The Employment Details Pathway
Questions 15-20 only apply to specific QROPS categories, creating a bifurcated process that many find confusing. When transferring to occupational schemes, overseas public service arrangements, or international organisation plans, comprehensive employment details become mandatory.
The payroll tax reference number (question 20) proves particularly challenging for individuals whose employment relationships span multiple jurisdictions or involve complex corporate structures. Some employers operate through umbrella companies or overseas subsidiaries, making the specific UK tax reference difficult to identify.
Employment Context and Regulatory Definitions
The form's employment questions reflect specific regulatory definitions established in Statutory Instrument 2006/206, which governs QROPS recognition. These aren't casual inquiries but legal classifications that determine tax treatment.
Overseas public service schemes encompass arrangements established for government employees, including diplomatic services, international development agencies, and certain multinational governmental organisations. The regulation 3(1B) reference provides legal certainty for schemes unsure of their classification.
International organisations under regulation 2(5) include entities like the United Nations, World Bank, or European institutions. These organisations often maintain their own pension arrangements that qualify for special treatment under UK tax law.
The employment date requirement (question 18) serves multiple purposes beyond simple record-keeping. It helps establish whether the employment relationship predates or postdates the pension transfer, influencing both the legitimacy of occupational scheme transfers and potential tax implications.
Critical Acknowledgements That Bind Your Future
The final section of APSS263 transforms from information gathering to legal commitment, with acknowledgements that create binding obligations extending far beyond the initial transfer.
Early Access Warnings
Question 21 addresses one of the most contentious aspects of overseas pension transfers: early access to funds. UK pension rules generally prohibit access before age 55, but some overseas schemes offer earlier withdrawal options. Acknowledging such access triggers enhanced scrutiny and potential tax charges.
This question has caught many transferees unprepared, particularly those attracted to overseas schemes specifically for their flexibility. The form forces explicit acknowledgement, preventing later claims of ignorance about UK tax implications.
Ongoing Tax Liability Commitments
Question 22's multiple acknowledgements create a comprehensive web of ongoing obligations. By signing, you accept that:
- Unauthorised payment charges may apply if the transfer doesn't meet recognition criteria
- Future QROPS payments may trigger UK tax liability regardless of your residence status
- Transfer charges may apply in certain circumstances
- Active cooperation with HMRC becomes a legal obligation, including providing future information and paying any taxes due
These commitments extend indefinitely, creating potential tax liabilities that can surface years after the initial transfer. The undertaking to pay tax and provide information means HMRC can pursue you internationally for compliance.
Navigating Submission Practicalities
Unlike many HMRC forms available through online portals, APSS263 typically requires physical completion and submission through your scheme administrator. This paper-based process reflects the form's role as an intermediary document rather than a direct HMRC submission.
Your scheme administrator becomes the critical link in this process, requiring the completed form before proceeding with any transfer arrangements. They must verify the information against their records and may request supporting documentation for unclear entries.
Timing Coordination Challenges
The 60-day deadline creates coordination challenges between multiple parties: the transferring scheme, the receiving QROPS, and potentially international advisers or employers. Some members find themselves rushing to complete the form while still finalising overseas arrangements, leading to incomplete or inaccurate submissions.
Scheme administrators cannot accept provisional or incomplete forms, meaning any missing information restarts the 60-day clock from when you submit a corrected version. This reality makes thorough preparation essential before beginning the formal process.
Long-Term Implications and Ongoing Obligations
Completing APSS263 marks the beginning, not the end, of your relationship with UK tax authorities regarding your overseas pension. The form creates a permanent record linking you to the transferred funds, establishing HMRC's basis for future tax claims regardless of your residence status.
The overseas transfer charge regime can apply not just to the initial transfer but to subsequent payments from the QROPS, particularly if you remain within certain geographic regions or if the receiving scheme loses its QROPS status. These reportable events can trigger tax liabilities years after your initial transfer.
Members often underestimate the administrative burden this creates. HMRC may request updates on your circumstances, details of payments received from the QROPS, or verification of continued scheme compliance. The undertaking signed on the form legally binds you to provide such information throughout your lifetime.
For those considering multiple transfers or complex international pension arrangements, each APSS263 submission creates additional compliance obligations. The cumulative effect can result in significant ongoing administrative responsibilities that persist long after the pension funds have been transferred and invested overseas.
Digital Submission Requirements and Technical Standards
The APSS263 form submission process has evolved significantly with HMRC's digital transformation initiatives. Pension scheme administrators must now navigate specific technical requirements when submitting member information electronically, which has become the standard method for most established schemes.
Electronic submissions require adherence to HMRC's XML schema specifications, which dictate the precise format and structure of data transmission. The current schema version supports enhanced data validation, reducing common submission errors that previously led to processing delays. Administrators must ensure their pension administration software generates XML files that comply with the latest schema - typically updated annually following consultation periods with industry stakeholders.
File size limitations apply to electronic submissions, with individual files capped at 100MB. Larger schemes with extensive member databases may need to split submissions across multiple files, each containing a maximum of 100,000 member records. The submission reference number system allows administrators to link related files, ensuring HMRC can reconstruct complete scheme data accurately.
Authentication protocols require administrators to use Government Gateway credentials specific to their scheme's Pension Scheme Tax Reference (PSTR). Multi-factor authentication has become mandatory for schemes with over 1,000 members, reflecting enhanced security measures introduced following the 2021 cybersecurity review. Administrators should maintain separate credentials for different schemes under their management to avoid cross-contamination of sensitive member data.
The digital acknowledgement system provides real-time confirmation of successful submissions, including a unique transaction reference number that administrators should retain for audit purposes. Failed submissions generate specific error codes that pinpoint data formatting issues, missing mandatory fields, or validation failures. Common error codes include 'E001' for invalid National Insurance numbers, 'E015' for date format inconsistencies, and 'E032' for pension input amount discrepancies.
Backup submission methods remain available for schemes experiencing technical difficulties. The contingency paper submission route requires prior approval from HMRC's Pension Schemes Services team and typically adds 4-6 weeks to processing times. Emergency submissions during system outages follow established protocols outlined in HMRC's business continuity guidance, with temporary extensions granted on a case-by-case basis.
Member Data Privacy and GDPR Compliance Framework
Pension scheme administrators handling APSS263 submissions must navigate complex data protection obligations under the UK GDPR and Data Protection Act 2018. The form contains extensive personal data, including financial information, employment history, and benefit calculations that require careful handling throughout the submission process.
Legal basis for processing member data through APSS263 submissions primarily relies on legal obligation (Article 6(1)(c) UK GDPR), as schemes must comply with statutory reporting requirements under the Finance Act 2004. However, administrators must also consider legitimate interests provisions when processing data for related administrative purposes, such as benefit calculations or member communications about tax implications.
Data minimisation principles require administrators to submit only information specifically requested in the APSS263 form structure. Additional member data held within pension administration systems should not be included in submissions unless explicitly required by HMRC guidance. This principle extends to historical data, where administrators must distinguish between current year reporting requirements and historical information that may be retained for other regulatory purposes.
Member notification requirements vary depending on the scheme's existing privacy notices and the specific circumstances of data collection. Most occupational pension schemes can rely on existing privacy notices that cover regulatory reporting obligations. However, personal pension schemes or those with international members may need enhanced notifications explaining cross-border data transfers to HMRC systems.
Data retention policies for APSS263 submissions must align with both pension scheme regulations and data protection requirements. HMRC retains submitted data according to its published retention schedule, typically seven years from the end of the relevant tax year. Scheme administrators should maintain parallel retention schedules that consider member rights to data portability and erasure, while recognising that certain pension data must be retained for benefit calculation purposes regardless of individual preferences.
International data transfer considerations arise when scheme administrators use cloud-based systems or outsourced services located outside the UK. The UK's adequacy decisions and international data transfer mechanisms must be properly documented, particularly when sensitive pension data transits through systems in non-adequate jurisdictions during the submission process.
Breach notification protocols require administrators to assess whether APSS263 submission errors constitute personal data breaches under UK GDPR definitions. Technical submission failures typically don't qualify as breaches, but unauthorised access to member data during transmission or processing requires immediate assessment and potential notification to both the Information Commissioner's Office and affected scheme members.
Cross-Border Pension Arrangements and International Compliance
The APSS263 form presents particular complexities for pension schemes with international dimensions, reflecting the UK's evolving position in global pension arrangements post-Brexit. Schemes covering members across multiple jurisdictions must navigate overlapping reporting obligations while ensuring compliance with both UK requirements and foreign regulatory frameworks.
European pension schemes with UK members face dual reporting challenges under both HMRC requirements and EU regulations. The form's member identification fields accommodate various national identifiers beyond National Insurance numbers, including European social security numbers and tax identification numbers from other jurisdictions. However, administrators must ensure primary reporting occurs through the APSS263 system for UK tax purposes, regardless of parallel obligations elsewhere.
Transfer value reporting becomes particularly complex for international arrangements. Cross-border transfers require detailed documentation within the APSS263 framework, including currency conversion methodologies and exchange rate dates. HMRC accepts transfers reported in foreign currencies, provided administrators include contemporaneous GBP equivalent values calculated using recognised exchange rate sources such as HMRC's published monthly rates or major financial institutions' daily rates.
Double taxation treaty provisions significantly impact reporting requirements for international pension arrangements. Members covered by specific treaty articles may qualify for modified reporting obligations, particularly regarding benefit accrual rates and contribution limits. The APSS263 form includes specific fields for treaty claim references, allowing administrators to flag cases requiring specialist tax treatment during HMRC processing.
Qualifying Recognised Overseas Pension Schemes (QROPS) face enhanced reporting obligations through the APSS263 framework when receiving transfers from UK registered schemes. The form captures detailed transfer information, including member residence status, receiving scheme jurisdiction, and ongoing compliance monitoring requirements. QROPS administrators must demonstrate continued qualifying status through annual confirmations linked to their APSS263 submissions.
Immigration status changes affecting scheme members create dynamic reporting obligations throughout the tax year. The form accommodates mid-year residence changes, requiring administrators to track members' UK tax status and adjust reporting accordingly. Non-resident members may qualify for reduced reporting requirements, but administrators must maintain documentation supporting residence determinations and be prepared to provide additional information if HMRC queries specific cases.
Employer-sponsored schemes with international operations must coordinate APSS263 reporting across multiple jurisdictions while avoiding duplicate or contradictory submissions. The form's employer reference fields link to UK PAYE systems, but international employers may need special arrangements with HMRC to establish appropriate reporting structures. Secondment arrangements and international assignments create particular complexity, requiring careful tracking of members' UK tax obligations throughout their overseas service.
Anti-avoidance provisions targeting international pension arrangements require enhanced disclosure through the APSS263 system. Schemes involved in complex international structures must provide additional information about related entities, fund flows, and potential tax avoidance arrangements. The form includes specific disclosure fields that trigger enhanced HMRC scrutiny and potential investigation procedures for arrangements that may circumvent UK tax obligations.