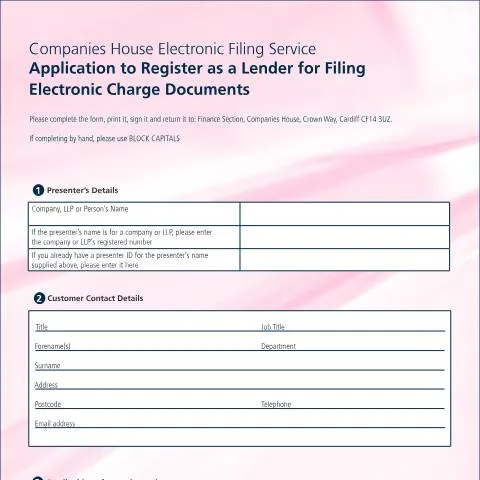
Securing Electronic Lender Status: The Gateway to Direct Charge Document Filing
When a financial institution or commercial lender operates within the UK's corporate landscape, the ability to file charge documents swiftly and efficiently becomes paramount to securing interests and maintaining competitive advantage. The Application to Register as a Lender for Filing Electronic Charge Documents represents Companies House's formal gateway for qualifying organisations to access direct electronic filing capabilities, bypassing traditional intermediary processes that can delay critical security registrations.
This specialised registration pathway acknowledges the distinct operational needs of lenders who regularly register charges against company assets. Unlike standard presenters who might file occasional documents, registered lenders gain streamlined access to the electronic filing infrastructure, enabling them to protect their interests with greater speed and autonomy. The application process involves both technical authentication setup and financial creditworthiness assessment, reflecting Companies House's dual focus on system security and payment reliability.
The significance extends beyond mere administrative convenience. In commercial lending scenarios where timing can determine priority ranking among competing charges, the ability to file electronically within hours rather than days can prove financially decisive. This registration therefore represents a strategic business tool rather than simply another bureaucratic requirement.
Qualifying Entities and Commercial Prerequisites
The application targets a specific cohort within the financial services sector, though eligibility extends beyond traditional high-street banks. Qualifying applicants typically include:
- Commercial banks and building societies maintaining active lending portfolios
- Asset-based lending specialists and invoice factoring companies
- Equipment finance providers and vehicle leasing organisations
- Private equity firms and institutional investors with direct lending operations
- Alternative finance platforms operating business lending functions
- Specialist trade finance providers and commodity financiers
Companies House applies practical volume thresholds when assessing applications. Organisations must demonstrate an intention to file at least 10 chargeable documents annually, ensuring the electronic filing infrastructure serves genuinely active participants rather than occasional users. This requirement reflects both system efficiency considerations and the administrative overhead involved in maintaining individual lender accounts.
The business profile assessment encompasses multiple dimensions. Years in operation provides stability indicators, while annual turnover and employee numbers demonstrate organisational capacity. Companies House particularly scrutinises applicants' main business activities, ensuring alignment with legitimate lending operations rather than peripheral financial activities that might generate insufficient filing volumes.
Navigating the Multi-Stage Authentication Architecture
Upon successful application approval, Companies House implements a sophisticated three-tier authentication system designed to balance accessibility with security. Understanding this architecture proves crucial for organisations planning their electronic filing implementation.
| Authentication Component | Primary Function | Security Level | Usage Context |
|---|---|---|---|
| Presenter ID | Organisation identification | Public reference | All electronic submissions |
| Presenter Authentication Code | Access verification | Confidential credential | System login and validation |
| Lender Authentication Code | Charge-specific authorisation | Restricted access | Charge document filing only |
The delivery methodology reflects security protocols established across government digital services. Credentials arrive via separate postal communications to the registered address, preventing single-point interception risks. This staggered delivery typically occurs within 5-10 working days of application approval, though applicants should factor potential delays during peak processing periods.
The lender authentication code represents the system's most restricted access level, specifically designed for charge document submissions. This segregation ensures that even if general presenter credentials become compromised, charge filing capabilities remain protected through the additional authentication layer.
Dissecting the Application Framework: Section-by-Section Analysis
The application form's structure reflects Companies House's systematic approach to gathering both identificational and commercial intelligence. Each section serves specific verification purposes while building a comprehensive organisational profile.
Presenter Details and Contact Architecture
Section 1 establishes the primary contact framework, with particular emphasis on email infrastructure capable of supporting ongoing service communications. The 80-character limit on email addresses reflects system database constraints, occasionally requiring organisations with lengthy domain structures to establish dedicated abbreviated contact addresses.
Companies House distinguishes between individual and corporate presenters through the company registration number field. Limited liability partnerships must provide their LLP registration number, while sole traders and partnerships operate under individual presenter arrangements. This distinction affects subsequent account management and liability frameworks.
Credit Account Assessment and Commercial Profiling
Section 4's commercial assessment extends beyond basic creditworthiness into operational compatibility evaluation. The business type classification influences both credit terms and ongoing account monitoring procedures. Public sector organisations typically receive preferential assessment criteria, reflecting reduced default risks associated with government-backed entities.
Expected monthly business values require realistic projection rather than aspirational estimates. Companies House cross-references these projections against industry benchmarks and applicant business profiles, with significant discrepancies potentially triggering additional verification requirements or application delays.
Existing customer relationships provide valuable assessment shortcuts. Organisations maintaining active Companies House Direct accounts or postal search arrangements benefit from established payment histories and verified contact details, often accelerating approval processes.
Trade Reference Requirements and Verification Protocols
The dual trade reference requirement serves multiple verification functions beyond simple creditworthiness confirmation. References must demonstrate genuine commercial relationships rather than perfunctory professional connections. Optimal references include:
- Major suppliers with established payment histories exceeding 12 months
- Professional services providers handling significant account values
- Technology vendors supporting core business operations
- Property management companies for substantial rental arrangements
Individual applicants enjoy exemption from trade reference requirements, reflecting the practical challenges of obtaining commercial references for sole trader operations. However, such applicants face enhanced scrutiny of their business profiles and expected filing volumes.
Payment Infrastructure and Account Management Options
The application encompasses multiple payment methodologies, each carrying distinct operational implications and cost structures. Understanding these options enables informed decisions aligned with organisational cash flow patterns and administrative preferences.
Credit account arrangements provide the most streamlined operational experience, particularly for high-volume filers. Monthly invoicing cycles align with standard business accounting practices, while consolidated billing simplifies expense allocation and budget management. However, credit accounts require minimum annual commitments and ongoing creditworthiness maintenance.
Alternative payment methods—credit/debit cards and PayPal—offer greater flexibility for occasional users or organisations preferring transaction-by-transaction payment approaches. These methods avoid credit assessment requirements but sacrifice the operational efficiency advantages of pre-established account arrangements.
The monthly business value projections directly influence credit limit determinations and payment term allocations. Conservative estimates risk inadequate credit facilities, while excessive projections may trigger enhanced verification requirements or guarantee requests.
Electronic Filing Integration and Operational Implementation
Successful registration opens access to Companies House's dual electronic filing channels: Web-Filing for direct browser-based submissions and Software Filing for integration with third-party applications. Each channel serves distinct operational requirements and technical capabilities.
Web-Filing provides immediate accessibility through standard internet browsers, requiring no additional software installations or technical integrations. This channel suits organisations with occasional filing requirements or those preferring manual submission control over automated processes.
Software Filing enables integration with existing practice management systems, charge management databases, and automated workflow tools. This channel particularly benefits:
- High-volume lenders processing dozens of charges monthly
- Organisations operating sophisticated case management systems
- Multi-location operations requiring centralised filing coordination
- Entities maintaining automated charge monitoring and renewal systems
The authentication codes function across both channels, ensuring consistent access regardless of chosen filing methodology. Organisations can operate hybrid approaches, using Web-Filing for urgent submissions while maintaining Software Filing for routine bulk processing.
Regulatory Framework and Compliance Obligations
Registration as an electronic lender operates within the broader regulatory framework governing charge registrations under the Companies Act 2006. The electronic filing privilege carries corresponding compliance obligations extending beyond simple form submission accuracy.
Data protection requirements under UK GDPR and the Data Protection Act 2018 apply throughout the electronic filing process. Registered lenders must implement appropriate security measures for authentication credential storage and ensure authorised personnel limitations align with data protection principles. Credential sharing or inadequate access controls can result in registration suspension or termination.
The terms and conditions accompanying registration establish ongoing obligations regarding minimum usage levels, payment compliance, and system usage protocols. Failure to maintain minimum filing volumes can trigger account review processes, while payment defaults may result in immediate access suspension pending resolution.
Companies House reserves discretionary authority over registration approval and ongoing account maintenance. This authority encompasses technical compliance monitoring, commercial relationship assessment, and system usage pattern evaluation. Registered lenders must therefore maintain not only technical compliance but also constructive ongoing relationships with Companies House administrative functions.
Strategic Implementation Considerations and Operational Planning
Successful electronic lender registration requires strategic planning extending beyond simple application submission. Organisations must consider internal process adaptations, staff training requirements, and integration with existing commercial procedures.
The transition from traditional postal filing to electronic submission often necessitates workflow redesign and responsibility reallocation. Key implementation considerations include:
- Authentication credential management and backup procedures
- Staff training on electronic submission protocols and error handling
- Integration planning with existing case management and client relationship systems
- Contingency procedures for system unavailability or technical difficulties
- Quality control processes ensuring submission accuracy and completeness
The registration timeline typically extends 2-4 weeks from application submission to full operational capability. This period encompasses application assessment, credit evaluation, authentication code generation, and system access provisioning. Organisations should factor this timeline into project planning and client communication strategies.
Ongoing relationship management with Companies House becomes increasingly important for registered lenders. Regular system usage, prompt payment compliance, and proactive communication regarding operational changes help maintain positive standing and ensure continued access to electronic filing privileges. The investment in registration and implementation therefore extends into long-term relationship maintenance and compliance monitoring.
Understanding the Different Types of Charges and Registration Requirements
The complexity of charge registration extends beyond simply completing Form MR01. Different types of charges carry distinct registration requirements, documentation standards, and potential complications that lenders must navigate carefully.
Fixed Charges vs Floating Charges: Critical Distinctions
Fixed charges attach to specific, identifiable assets at the time of creation—such as particular machinery, property, or equipment. These charges take immediate priority and require precise asset identification in your registration documents. When registering a fixed charge, you must provide detailed descriptions that would allow a third party to locate and identify the secured asset without ambiguity.
Floating charges, conversely, hover over a class of assets that may change in the ordinary course of business—typically stock, debtors, or cash. These charges only crystallise when specific trigger events occur, such as the appointment of an administrator or breach of loan conditions. The registration documentation must clearly define the class of assets covered and any restrictions on the company's ability to deal with those assets.
Specialist Charge Types Requiring Additional Consideration
Certain charges demand heightened attention during registration. Charges over intellectual property, for instance, may require concurrent registration with the Intellectual Property Office for patents or trade marks. Aircraft charges necessitate registration with the Civil Aviation Authority, whilst ship mortgages require Maritime and Coastguard Agency involvement.
Charges securing revolving credit facilities present particular challenges. The charge document must accommodate future advances whilst ensuring the security remains enforceable. This often requires careful drafting of "all monies" clauses and consideration of how future lending will interact with the original charge registration.
Cross-Border and International Complications
When charges involve assets located outside England and Wales, or when dealing with overseas companies, additional registration requirements may apply. Assets in Scotland require registration with the Register of Inhibitions, whilst Northern Irish assets need registration with the Department for the Economy. European assets may trigger requirements under various national registration systems, each with distinct deadlines and procedures.
Foreign companies establishing charges over UK assets face particular complexity. Whilst Companies House registration may still be required, the interaction with the company's home jurisdiction registration requirements demands careful legal analysis to ensure enforceability in all relevant territories.
Managing Registration Deadlines and Rectification Procedures
The 21-day registration deadline represents one of the most unforgiving aspects of UK charge registration. Missing this deadline doesn't merely create administrative inconvenience—it can render an otherwise valid security interest void against liquidators, administrators, and other creditors.
Calculating the 21-Day Period Accurately
The deadline runs from the date of charge creation, not the date of loan drawdown or security documentation execution. For charges created outside the UK, determining the creation date requires careful analysis of the governing law and local requirements. Weekend and bank holiday extensions don't apply to this deadline, making precise calculation essential.
When charges are created by deed, the creation date typically aligns with the execution date. However, charges arising from statutory provisions or court orders may have different effective dates. Charges securing future advances present additional complexity, as each advance may constitute a separate charge creation requiring individual consideration of the registration timeline.
Late Registration Applications: Court Procedures and Prospects
When the 21-day deadline has passed, only a court order can achieve registration. Applications under section 873 of the Companies Act 2006 must demonstrate that the failure to register was inadvertent, that no prejudice would arise to existing creditors, and that registration serves the public interest.
The court considers various factors when evaluating late registration applications. These include the length of delay, the reasons for non-registration, whether other creditors have extended credit in reliance on the apparent absence of charges, and the company's financial position. Longer delays face increasing judicial scepticism, particularly where the company has experienced financial difficulties since the original deadline.
Successful applications typically involve relatively short delays with clear explanations—such as postal delays, administrative errors, or genuine misunderstandings about registration requirements. The court may impose conditions on registration, such as restrictions on the charge's priority or requirements for additional creditor notifications.
Amendment and Rectification of Existing Registrations
Errors in registered charge particulars can be corrected through Companies House's rectification procedures, but the scope for amendments remains limited. Factual errors—such as incorrect asset descriptions or charge amounts—may be correctable through administrative procedures. However, substantive changes to charge terms typically require fresh registration of varied charges.
When seeking rectification, provide clear evidence of the error and its correction. Companies House may require statutory declarations or other supporting documentation to verify amendment requests. Remember that third parties may have relied on the originally registered particulars, potentially limiting rectification options where prejudice could arise.
Post-Registration Compliance and Ongoing Obligations
Successful charge registration marks the beginning, not the end, of compliance obligations. Registered lenders must maintain accurate records, monitor charge status changes, and ensure proper discharge procedures when security is released.
Monitoring and Maintaining Charge Priority
Charge priority generally follows registration order, but this principle carries numerous exceptions and complications. Subsequent charges may achieve superior priority through various mechanisms, including statutory preferences, purchase money security interests, or crystallisation of earlier floating charges.
Regular monitoring of the company's charge register helps identify potential priority conflicts before they become problematic. New registrations may indicate financial stress, additional borrowing, or changes in the company's capital structure that could affect your security position. Some lenders implement automated monitoring systems to track new registrations affecting their borrowers.
Negative pledge clauses in loan documentation provide contractual protection against subsequent charges, but enforcement depends on the specific wording and circumstances. These clauses don't automatically invalidate later charges but may provide grounds for acceleration or other remedies under the loan agreement.
Satisfaction and Discharge Procedures
When loans are repaid or security is no longer required, proper discharge procedures protect both lender and borrower interests. Form MR04 facilitates charge satisfaction registration, but timing and accuracy remain crucial to avoid complications.
Partial discharges require particular care, especially where charges secure multiple facilities or revolving credit arrangements. The discharge documentation must clearly identify which obligations are being released whilst preserving security for continuing liabilities. Ambiguous partial discharges can create uncertainty about the scope of remaining security.
Companies may apply for charge satisfaction registration without lender cooperation in limited circumstances, but such applications face closer scrutiny and potential objection procedures. Lenders should respond promptly to any satisfaction applications they consider inaccurate or premature.
Insolvency and Enforcement Considerations
Properly registered charges provide significant advantages in insolvency scenarios, but enforcement requires careful navigation of statutory procedures and potential challenges. Floating charges face particular scrutiny, including potential invalidity periods and prescribed part requirements that may reduce recovery prospects.
The prescribed part provisions require floating charge holders to set aside portions of realisations for unsecured creditors, subject to statutory maxima and company net property thresholds. These provisions don't affect fixed charges but can significantly impact floating charge recoveries, particularly for smaller companies.
Enforcement procedures vary depending on charge type and secured assets. Property charges may facilitate Law of Property Act receiver appointments or possession proceedings, whilst charges over shares might enable voting control or dividend interception. Each enforcement route carries distinct procedural requirements and potential complications requiring specialist legal advice.