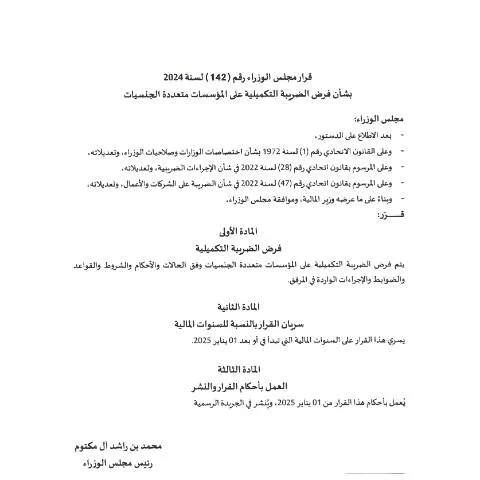
Navigating the Arabic Cabinet Decision No. (142) of 2024: Understanding the Top-Up Tax on MNEs
The introduction of the Top-Up Tax on Multinational Enterprises (MNEs) as outlined in the Arabic Cabinet Decision No. (142) of 2024 is a significant development in the UAE's fiscal landscape. Stakeholders, especially foreign corporations operating within UAE jurisdictions, need to grasp the intricacies of this tax regulation. This official document is a crucial element for compliance and understanding the wider implications for MNEs.
Decoding the Objectives and Scope of the Decision
The Arabic Cabinet Decision No. (142) aims to align UAE's tax policies with international standards by implementing a top-up tax that ensures that MNEs pay a minimum level of tax on their profits. Here’s what you should know about the objectives:
- International Alignment: The UAE seeks to comply with the OECD's Base Erosion and Profit Shifting (BEPS) initiative to prevent tax avoidance by multinational corporations.
- Enhanced Revenue Generation: The top-up tax is designed to bolster the UAE's revenue streams, ensuring that substantial profits generated by MNEs contribute fairly to the economy.
- Fair Competition: By establishing a minimum tax level, the UAE aims to create a level playing field for local businesses against their multinational counterparts.
Who is Required to File the Top-Up Tax Application?
The filing of the top-up tax application is not merely a bureaucratic necessity; it is vital for ensuring compliance with the law. All MNEs operating in the UAE that meet the following criteria must submit the form:
- MNEs with consolidated revenues exceeding AED 3.15 billion.
- MNEs that operate in jurisdictions with a tax rate lower than the minimum effective tax rate set by the UAE.
- Entities involved in cross-border transactions must also be aware of their obligations to disclose relevant financial information.
Navigating the Form: A Step-by-Step Breakdown
Completing the official form associated with the top-up tax requires precision and clarity. Below, we dissect the critical sections of the form:
| Form Section | Description | Common Pitfalls |
|---|---|---|
| Taxpayer Information | Details regarding the MNE, including name, registration number, and contact details. | Ensure that all details match official documents to avoid discrepancies. |
| Financial Data | Submission of the MNE's financial statements, including revenue, profit margins, and applicable expenses. | Misreporting or omitting significant financial data could lead to penalties. |
| Adjustment Calculations | Calculating the top-up amount based on profits and existing tax payments. | Incorrect calculations can result in underpayment or disputes with tax authorities. |
| Declaration and Signature | A declaration confirming the accuracy of the provided information, including appropriate signatures. | Failure to provide a valid signature may nullify the submission. |
Submission Process: From Preparation to Filing
Once the form is completed, understanding the submission process is critical to avoiding penalties. Here’s a chronological overview of what to expect:
- Document Assembly: Gather all required documents, including financial statements and any prior tax filings.
- Electronic Submission: Submit the form through the official Emirates ID portal or the relevant federal system.
- Confirmation Receipt: Ensure you receive a confirmation of submission; this is your proof of compliance.
- Follow-Up: Monitor the status of your application via the online portal to confirm that it is being processed.
- Review Period: The tax authority has a designated review period; ensure you are available for any potential queries.
Understanding Your Obligations and Rights
Filing for the top-up tax is not just about compliance but understanding your rights and obligations as a taxpayer:
- Right to Appeal: If you disagree with the tax authority's assessment, you have the right to appeal within a specified timeframe.
- Obligation to Maintain Records: MNEs must keep comprehensive records of financial transactions and tax filings for a minimum of five years.
- Disclosures for Transparency: MNEs are required to disclose any related party transactions as part of the filing process.
Timeline and Future Implications for MNEs
Marking critical dates on your calendar is vital for compliance. The timeline involves:
- Effective Date: The top-up tax is applicable to financial years beginning on or after January 1, 2025.
- Filing Deadlines: MNEs must file their tax applications within 12 months of the end of their financial year.
- Subsequent Assessments: Tax authorities may conduct audits, which could lead to adjustments based on MNEs' reported data.
Special Considerations for Foreign Entities and Complex Cases
For foreign entities operating in the UAE, navigating the top-up tax requirements demands careful attention to detail. Here are some critical points:
- Tax Treaties: Review any existing double taxation treaties (DTTs) which may impact tax liabilities.
- Permanent Establishment Status: Determine if your operations in the UAE constitute a permanent establishment, which could have tax implications.
- Involvement of Local Agent: Consider appointing a local tax advisor to assist with compliance and filing in the UAE.
Potential Consequences of Non-Compliance
The ramifications of failing to meet the filing requirements can be severe:
- Financial Penalties: Late submissions or inaccuracies may incur fines based on the severity of the non-compliance.
- Business Reputation: Non-compliance can affect relationships with stakeholders and investors.
- Legal Ramifications: Continued disregard can lead to more severe legal actions from tax authorities.
In summary, the Arabic Cabinet Decision No. (142) of 2024 is a pivotal component of the UAE’s evolving tax framework. By understanding the nuances involved in the top-up tax application process, MNEs can ensure compliance and minimize risks associated with non-compliance. The proactive engagement in this process not only upholds legal obligations but contributes to the transparency and integrity of the UAE’s fiscal system.
Understanding Cabinet Resolution No. (142) for Multinational Corporations
The Cabinet Resolution No. (142) of 2024 regarding the imposition of supplementary taxes on multinational enterprises marks a significant development in the UAE's taxation landscape. This resolution aims to align the UAE's tax policies with international standards, specifically those set forth by the OECD (Organisation for Economic Co-operation and Development), particularly in relation to Base Erosion and Profit Shifting (BEPS). The supplementary tax imposed under this resolution is designed to ensure that large multinational corporations contribute fairly to the UAE's economy while maintaining a competitive business environment.
Implications for Businesses and Compliance Requirements
For multinational corporations operating within the UAE, understanding the implications of Cabinet Resolution No. (142) is crucial. The resolution outlines specific compliance requirements that these businesses must adhere to, including the necessity to accurately report their income, expenses, and tax liabilities. Failure to comply can result in substantial penalties, including fines and potential legal actions initiated by the Federal Tax Authority (FTA).
Corporations are required to maintain detailed documentation that supports their tax filings, particularly concerning cross-border transactions. This includes transfer pricing documentation which demonstrates compliance with the arm's length principle. The FTA has emphasized the importance of transparency in order to mitigate risks associated with tax avoidance strategies employed by multinational entities.
Potential Exceptions and Special Considerations
While Cabinet Resolution No. (142) establishes a general framework for the taxation of multinational corporations, there are potential exceptions that these businesses should be aware of. Certain sectors, such as education, health, and infrastructure, may have specific tax incentives or exemptions that could be applicable, encouraging investment in these critical areas. Additionally, smaller multinational corporations with lower revenue thresholds might qualify for simplified compliance procedures or reduced tax rates.
It's also essential for affected businesses to stay informed about updates and changes to the tax framework, as the UAE government continues to refine its approach to taxation. Engaging with tax advisors who possess expertise in UAE tax laws and international tax treaties can provide vital insights and assist in navigating complex tax obligations.